strike at port

German port strikes averted, but Rhine disruption deepens

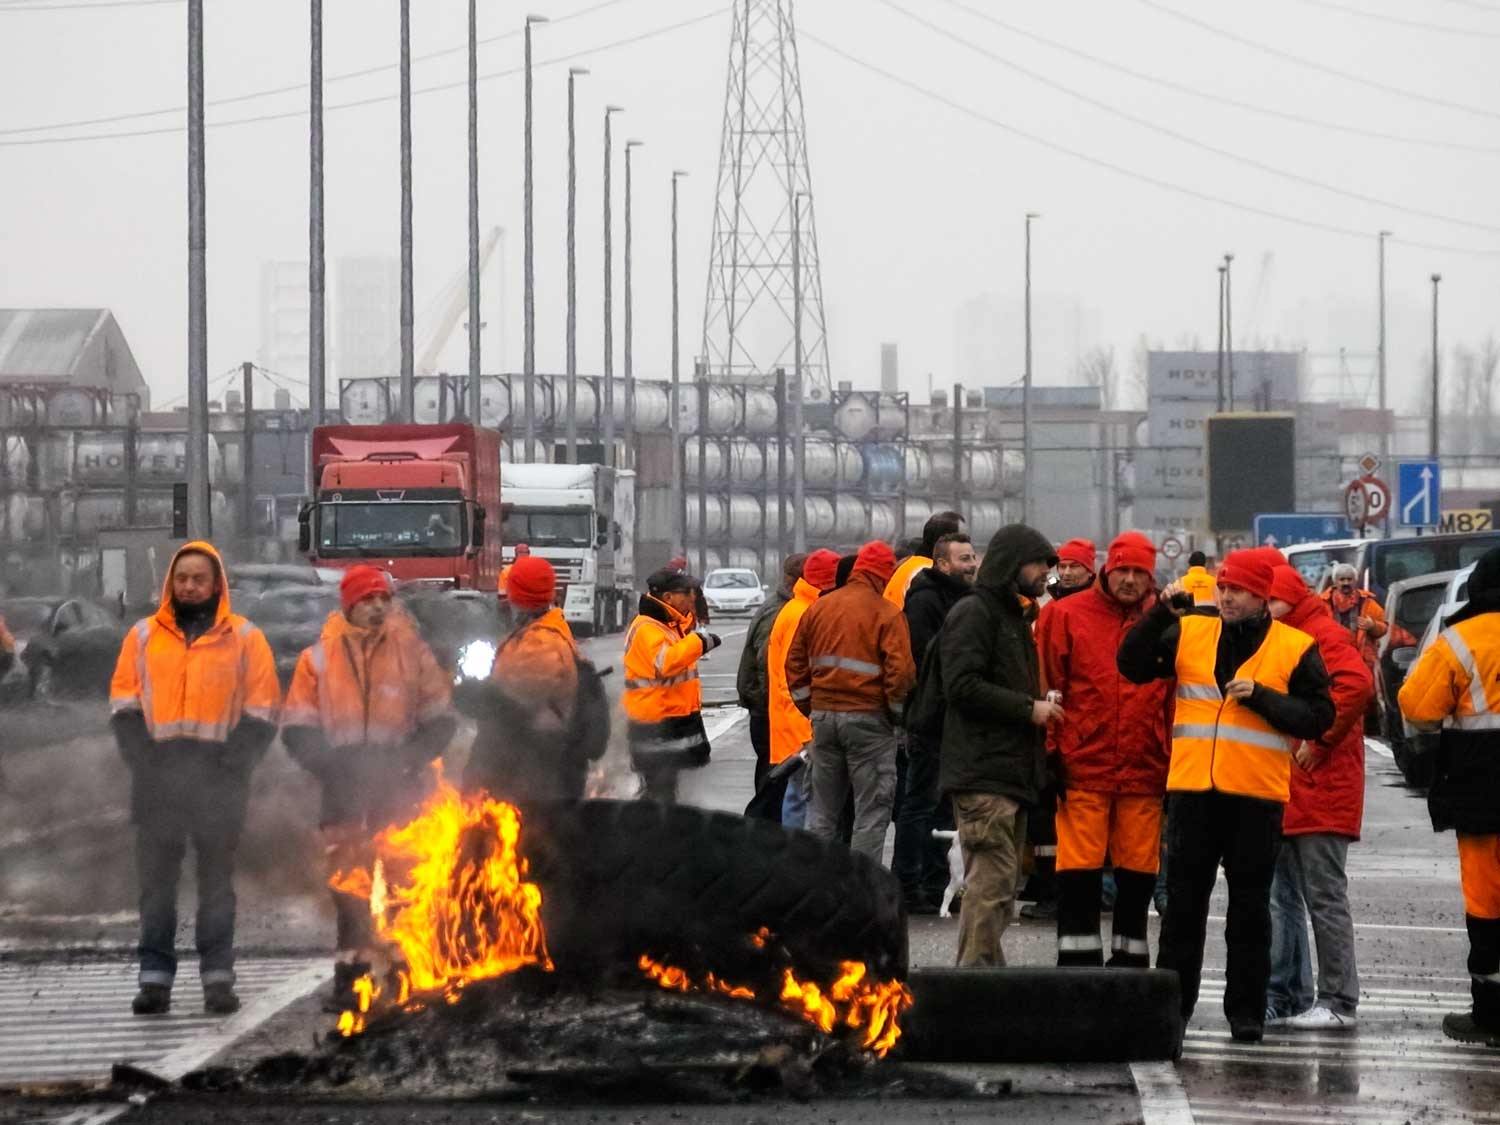
German dockworkers have accepted a new pay agreement, averting widespread port strikes, but record-low Rhine water levels continue to disrupt inland freight movements, increasing costs and threatening North European supply chains.

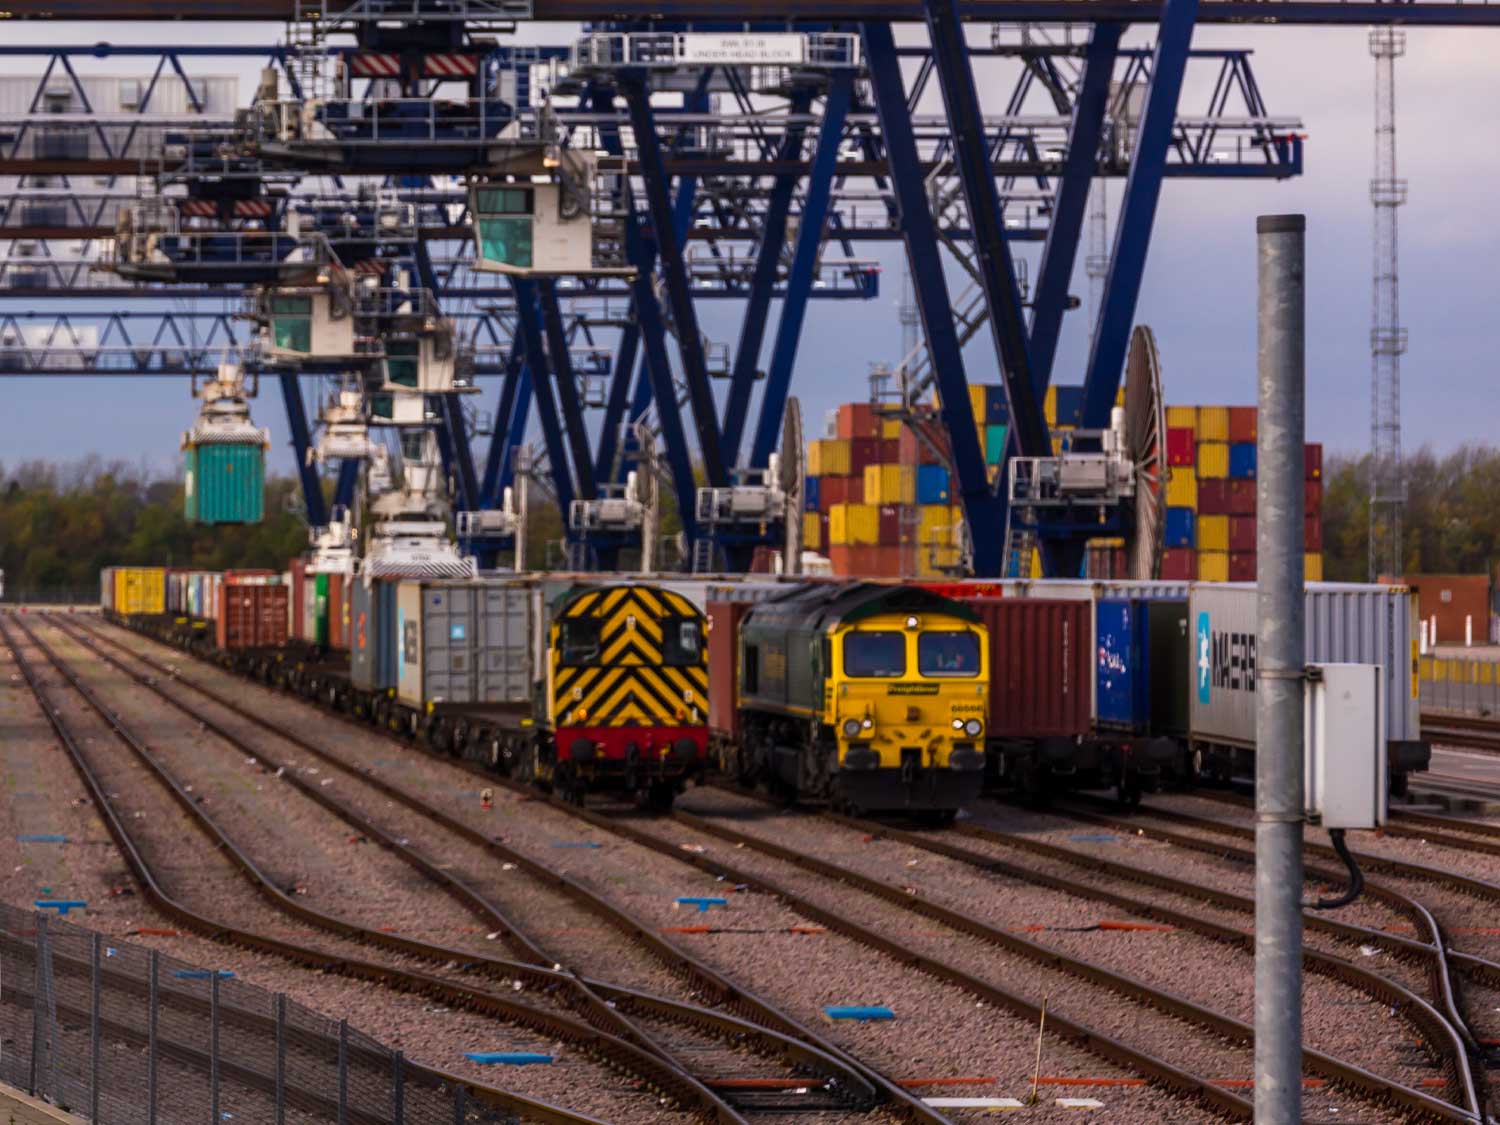
North European importers have avoided another potential disruption after German dockworkers accepted revised employment terms, reducing the immediate threat of industrial action at Hamburg, Bremerhaven and Wilhelmshaven.

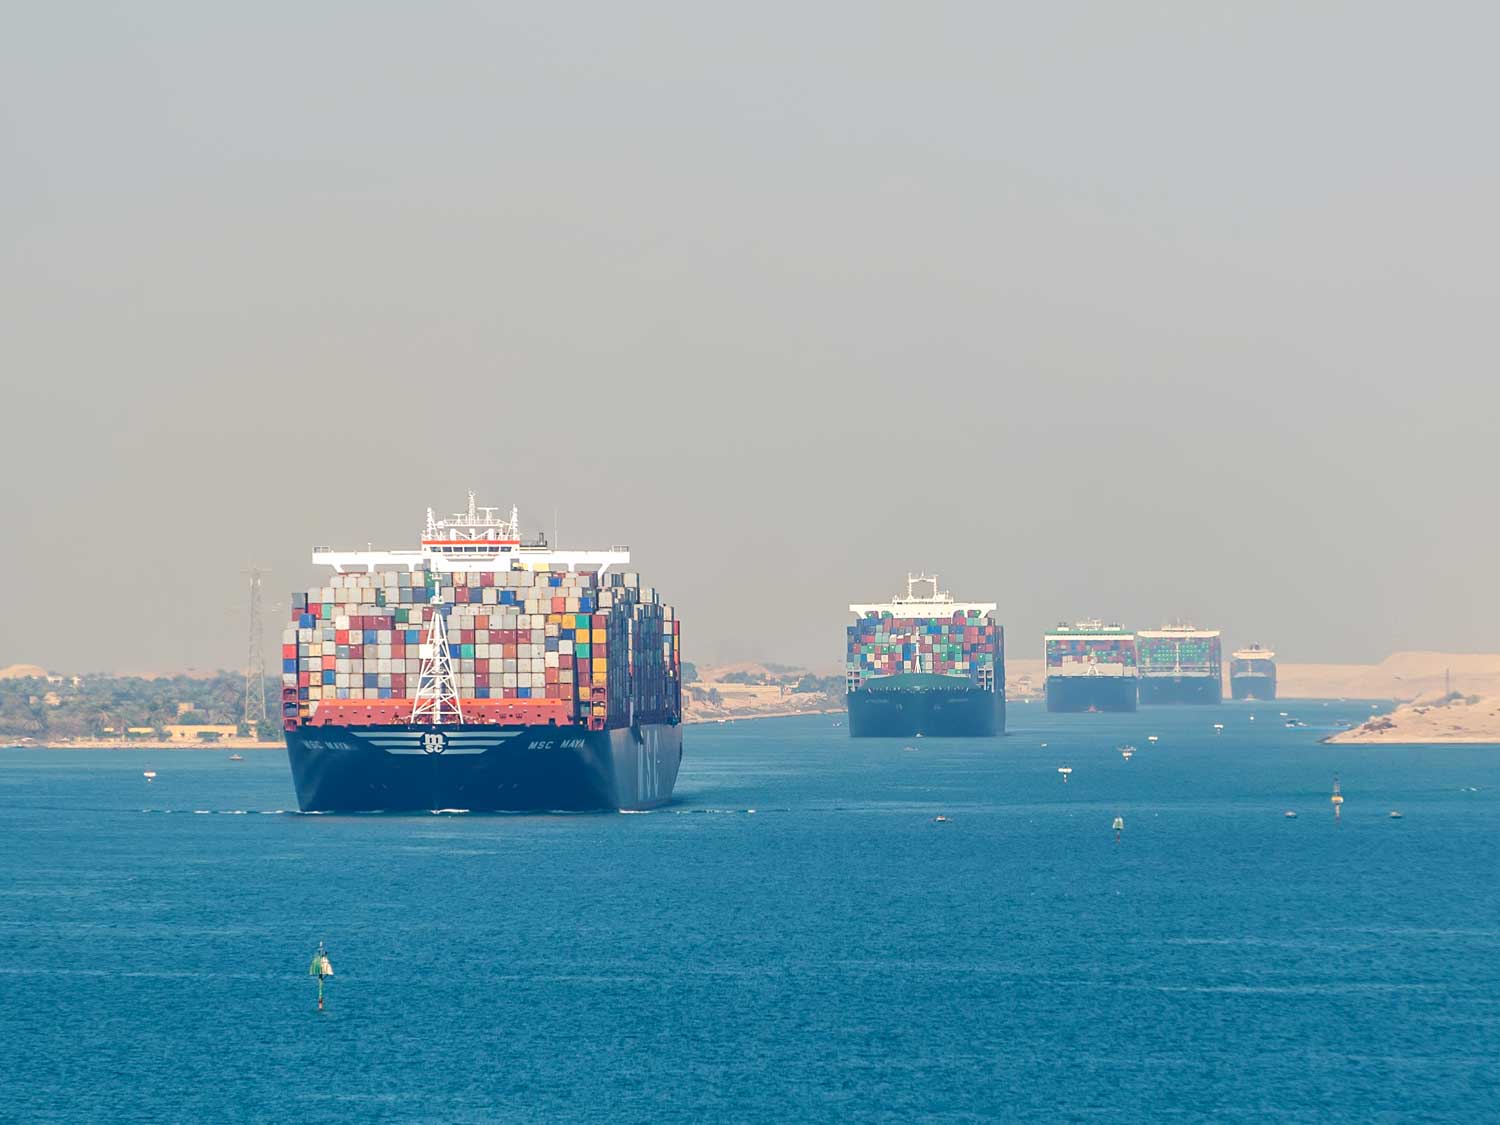
However, congestion remains at several terminals, while exceptionally low Rhine water levels are restricting barge operations between Germany's industrial heartland and the major container gateways of Rotterdam and Antwerp.

The result is a continuing challenge for European supply chains: even when ocean freight services and port operations improve, inland transport constraints can still delay cargo and increase costs.

German port agreement reduces strike risk

Germany's ver.di union accepted revised employment terms on 6 October, following several rounds of negotiations and earlier warning strikes.

The agreement covers approximately 11,000 workers across six German ports and includes a 3.4% wage increase over 12 months.

Although final approval from port employers remains outstanding, the agreement has significantly reduced the immediate threat of industrial action.

However, terminal congestion remains a concern. Bremerhaven's container yard utilisation has reached 90%, compared with 80–85% at Hamburg and approximately 65% at Wilhelmshaven.

Vessel waiting times have improved since early September, but high terminal utilisation leaves limited flexibility to absorb further disruption.

Rhine restrictions threaten inland connections

The Rhine presents a more persistent challenge. Exceptionally low water levels have restricted barge movements along one of Europe's most important inland freight corridors, connecting German industrial centres with Rotterdam and Antwerp.

At Kaub, a critical navigation point, water levels fell to just 6cm on the gauge during August, the lowest recorded since measurements began in 1880.

Barges have been forced to operate with substantially reduced loads, while some vessels have been unable to complete their journeys.

The scale of the disruption is significant. A single 1,500-tonne barge can carry the equivalent of approximately 60 lorry loads, placing additional pressure on road and rail networks when river transport becomes unavailable.

Congestion is also affecting barge operations, with average waiting times reaching 36 hours at Antwerp and 56 hours at Rotterdam.

The severity of the situation was reinforced over the weekend of 10–11 October, when four inland vessels ran aground near Ludwigshöhe, prompting additional restrictions on vessel movements near Mainz.

Although all four vessels were subsequently refloated, the incidents underline the continuing risks facing inland shipping.

Low-water surcharges increase transport costs

Restricted barge capacity is also increasing inland transport costs. Shipping lines and barge operators have revised low-water surcharges to reflect the additional expense of operating vessels with reduced loads.

Surcharge structures link charges to water levels at Duisburg-Ruhrort, Kaub and Cologne.

As river levels fall, charges increase progressively, with the most severe restrictions potentially adding more than €1,500 per container to inland transport costs.

At particularly low levels, operators may be unable to guarantee container movements at all.

Alternative road and rail services can help maintain cargo flows, but limited capacity and increased demand may introduce further delays and expense.

A container arriving on schedule at Rotterdam, Antwerp or a German gateway offers little benefit if its onward movement is delayed by restricted inland capacity.

Keep your European supply chain moving

Metro's ocean freight and European logistics specialists combine carrier relationships, local market intelligence and inland transport expertise to help customers maintain reliable cargo movements.

From assessing alternative gateways and inland routes to coordinating road, rail and multimodal transport, Metro can identify practical options to minimise disruption and protect delivery commitments.

Don't let inland disruption undermine your shipping plans. Talk to Metro's freight specialists about your upcoming European shipments and the transport options that can keep your cargo moving.
Metro model truck 1440x1080 1

Road freight resilience starts before the truck arrives

UK haulage is entering a period in which access to the right vehicle, route and transport option could become increasingly important. For shippers, that makes planning and flexibility just as important as the rate agreed for an individual movement.

More than half of UK HGV drivers are aged between 50 and 65, while fewer than 2% are under 24. Replacing an ageing workforce brings recruitment, training, insurance and employment costs at the same time as operators manage wider pressure on vehicle operating expenses.

That does not mean the UK is heading inevitably towards a nationwide shortage of trucks. But it is going to make availability more variable by location, vehicle type and periods of peak demand.

For shippers, the response is to look beyond simply finding a truck when one is needed for UK or international movements and consider the strength, flexibility and resources behind their transport solution.

More ways to keep freight moving

Access to multiple transport options provides an important buffer when individual parts of the market tighten.

Metro combines its own commercial fleet with a wider UK and European road freight network, giving customers access to dedicated domestic transport, groupage, less-than-truckload (LTL) and full-truckload (FTL) solutions.

Dedicated vehicles can operate on fixed routes, with GPS tracking providing visibility throughout the journey. Different equipment, security and service options also allow the transport solution to be matched more closely to the cargo, delivery environment and required transit time.

Metro’s UK road freight teams are strategically located close to major manufacturing and transport hubs, supporting both domestic movements and international connections.

That capability extends across Europe, with established groupage services connecting customers with France and Germany, including the industrially important Ruhr region, with further services into the Netherlands, Poland, Iberia and Turkey. Frequent departures and established partner networks provide further options for both inbound and outbound freight.

This breadth matters when availability changes. Rather than depending on one mode of road transport or a narrow pool of vehicles, shippers can combine dedicated, groupage, LTL and FTL services according to shipment size, urgency and destination.

Plan capacity, not individual movements

The other side of road freight resilience is using available capacity efficiently.

Booking transport at the final stage of a shipment can leave logistics teams with fewer choices if the required vehicle or departure is already constrained. Earlier visibility of inbound and outbound requirements creates more opportunity to plan collections, consolidate freight, secure equipment and select alternative services.

It can also help businesses avoid treating domestic or European haulage as an isolated final step.

A container arriving at a UK port, an urgent movement into Germany or several smaller consignments moving into continental Europe all create different transport requirements. Connecting those movements with the wider supply chain makes it easier to choose the right solution before capacity becomes critical.

That could mean consolidating smaller shipments into groupage, moving time-sensitive cargo on a dedicated vehicle, using LTL where greater flexibility is available or securing FTL capacity earlier for larger movements.

The objective is not simply to source the lowest rate for today’s shipment. It is to create enough options to keep freight moving efficiently as demand, availability and operating costs change.

For UK and European shippers, the resources behind a road freight provider are therefore becoming increasingly important. Its own fleet, access to additional capacity, range of service options, network coverage and ability to adapt routes when circumstances change.

Metro combines its own commercial fleet with an extensive UK and European road freight network, giving customers the flexibility to move from dedicated vehicles to groupage, LTL and FTL solutions as requirements change. 

With strategically located teams, MVT supply chain management platform, GPS-tracked services and strong connections across key European markets, we can build road freight solutions around your cargo, keeping goods visible, capacity accessible and supply chains moving.

factory emissions

EU supply-chain rules may be easing but shipper expectations are changing

The EU is reducing some sustainability and due-diligence obligations, but that does not necessarily mean businesses will need less supply-chain information. For shippers, the capabilities of their logistics partners could become increasingly important.

For years, businesses have been preparing for a more demanding era of European supply-chain regulation, with greater emphasis on sustainability, due diligence and visibility beyond their immediate suppliers.

Now Brussels is changing direction. The EU’s Omnibus simplification programme is reducing the scope of some requirements, delaying implementation and cutting the amount of sustainability information companies must report.

For shippers, particularly those outside the revised thresholds, that should reduce the direct administrative burden.

But something important has already changed. Large organisations have invested in systems and processes to understand their supply chains in far greater detail, while sustainability, procurement and logistics teams have become accustomed to collecting information that was rarely requested a decade ago.

Those expectations are unlikely simply to disappear.

Brussels reduces the regulatory burden

The Corporate Sustainability Due Diligence Directive (CSDDD) has been substantially scaled back, focusing requirements on the largest businesses (>5,000 employees and net t/o >€1.5bn) and pushing implementation back to July 2029.

Sustainability reporting is also being simplified, with significant reductions in mandatory datapoints intended to lower reporting costs.

Importantly for supply chains, the EU has sought to limit the extent to which large organisations can pass excessive reporting demands down to smaller suppliers.

That should reduce unnecessary bureaucracy, but there is an important distinction between information companies are legally required to collect and the information they choose to obtain to manage risk, sustainability and supply-chain performance.

The demand for supply-chain data is already established

Early sustainability reporting provides an indication of how far corporate practices have already moved.

Deloitte’s analysis of 200 early adopters found particularly extensive reporting among consumer businesses. More than 90% disclosed emissions associated with purchased goods and services, while 94% reported emissions from upstream transport and distribution.

Industrial businesses were also incorporating Scope 3 emissions into climate targets and transition planning.

That matters for logistics because much of the information required to understand those emissions sits outside the shipper's own organisation.

Consider a manufacturer outsourcing European distribution to a freight forwarder. The forwarder may use several regional carriers, which could in turn subcontract individual movements to smaller hauliers.

The shipper may have a commercial relationship with one logistics provider while the physical movement involves several organisations.

Increasingly, businesses want to understand what happens further down that chain.

Which carrier moved the shipment? Which route and transport mode were used? Were subcontractors involved? What emissions were generated? Are appropriate compliance checks in place? Can the underlying information be verified?

Those questions have value beyond regulatory reporting. They can support procurement, corporate governance, customer commitments, risk management and decisions about how supply chains should be designed.

The forwarder's role is changing

This has implications for how shippers select logistics partners.

Price, capacity and service will remain fundamental, but increasingly they may form only part of the assessment, as visibility, data and compliance become more critical.

Price + capacity + service + visibility + data + compliance

A forwarder that can move cargo efficiently but struggles to provide reliable information about the underlying movement may become less attractive to businesses with sophisticated governance or sustainability requirements.

The strongest logistics partners will increasingly connect physical freight management with technology, supplier oversight and usable data.

That changes the forwarder's role from simply arranging transport to helping customers understand and control increasingly complex supply chains.

Better data can support better decisions

There is also a danger that greater transparency simply creates more information. The real value comes when shippers can use that information.

Emissions data provides a good example. Knowing the carbon footprint of an individual shipment supports reporting, but consistent data across modes, routes and origins can also help businesses compare alternatives and identify where operational changes could reduce emissions.

Metro's MVT ECO platform measures CO₂ equivalent emissions at consignment level across transport modes and routes, using recognised logistics emissions methodologies.

This gives customers the ability to examine emissions across their freight activity rather than relying solely on broad estimates, supporting Scope 3 reporting as well as longer-term supply-chain planning.

The same principle applies more broadly: forwarder technology should not simply produce data because somebody has asked for it. It should help shippers make better decisions.

Procurement may move faster than regulation

Perhaps the most important change will therefore come through procurement rather than legislation.

Large businesses do not need regulation to require particular standards from logistics providers. They can incorporate them into RFQs, supplier codes, operating procedures and contracts.

Requirements developed by multinational businesses can then spread through the market as other organisations adopt similar procurement standards.

It means even companies unaffected by CSDDD or CSRD requirements may ultimately benefit from logistics infrastructure originally developed in response to them.

Better carrier governance, reliable emissions measurement, stronger data and improved visibility have operational value whether or not a regulator asks for them.

Choosing logistics partners for what comes next

The EU's simplification programme should make compliance more proportionate for many European businesses.

But reducing regulation does not reverse the broader movement towards more transparent and accountable supply chains.

For shippers, that makes the capabilities sitting behind a freight rate increasingly important.

The forwarders best equipped for the future will not simply provide competitive transport. They will combine networks and operational expertise with the systems, processes and data that give customers greater visibility and control.

For businesses reviewing logistics partners, the question may therefore be shifting from “Can you move our freight?” to “Can you help us understand, control and demonstrate how our freight is moved, while reporting on emissions?”

Metro combines international freight expertise with supply-chain technology and emissions visibility through solutions including MVT ECO, helping customers turn increasingly sophisticated data requirements into practical supply-chain insight.

Survey EU

Businesses target European growth despite customs barriers

UK businesses remain positive about their prospects in Europe, but customs complexity, compliance costs and uncertainty over future trading arrangements may limit the potential for faster growth.

That is the picture emerging from Metro’s latest customer survey, which asked businesses how they expect their EU trade to develop during 2026-27 and what would make cross-border trade easier.

The survey followed Metro’s recent review of the UK’s evolving international trade relationships, including ongoing discussions designed to improve elements of the UK-EU trading environment.

While negotiations between the UK and EU continue, the responses suggest businesses are not waiting for political agreements before pursuing growth. Instead, many are already looking at new products, markets and logistics strategies, while seeking practical ways to reduce the friction associated with European trade.

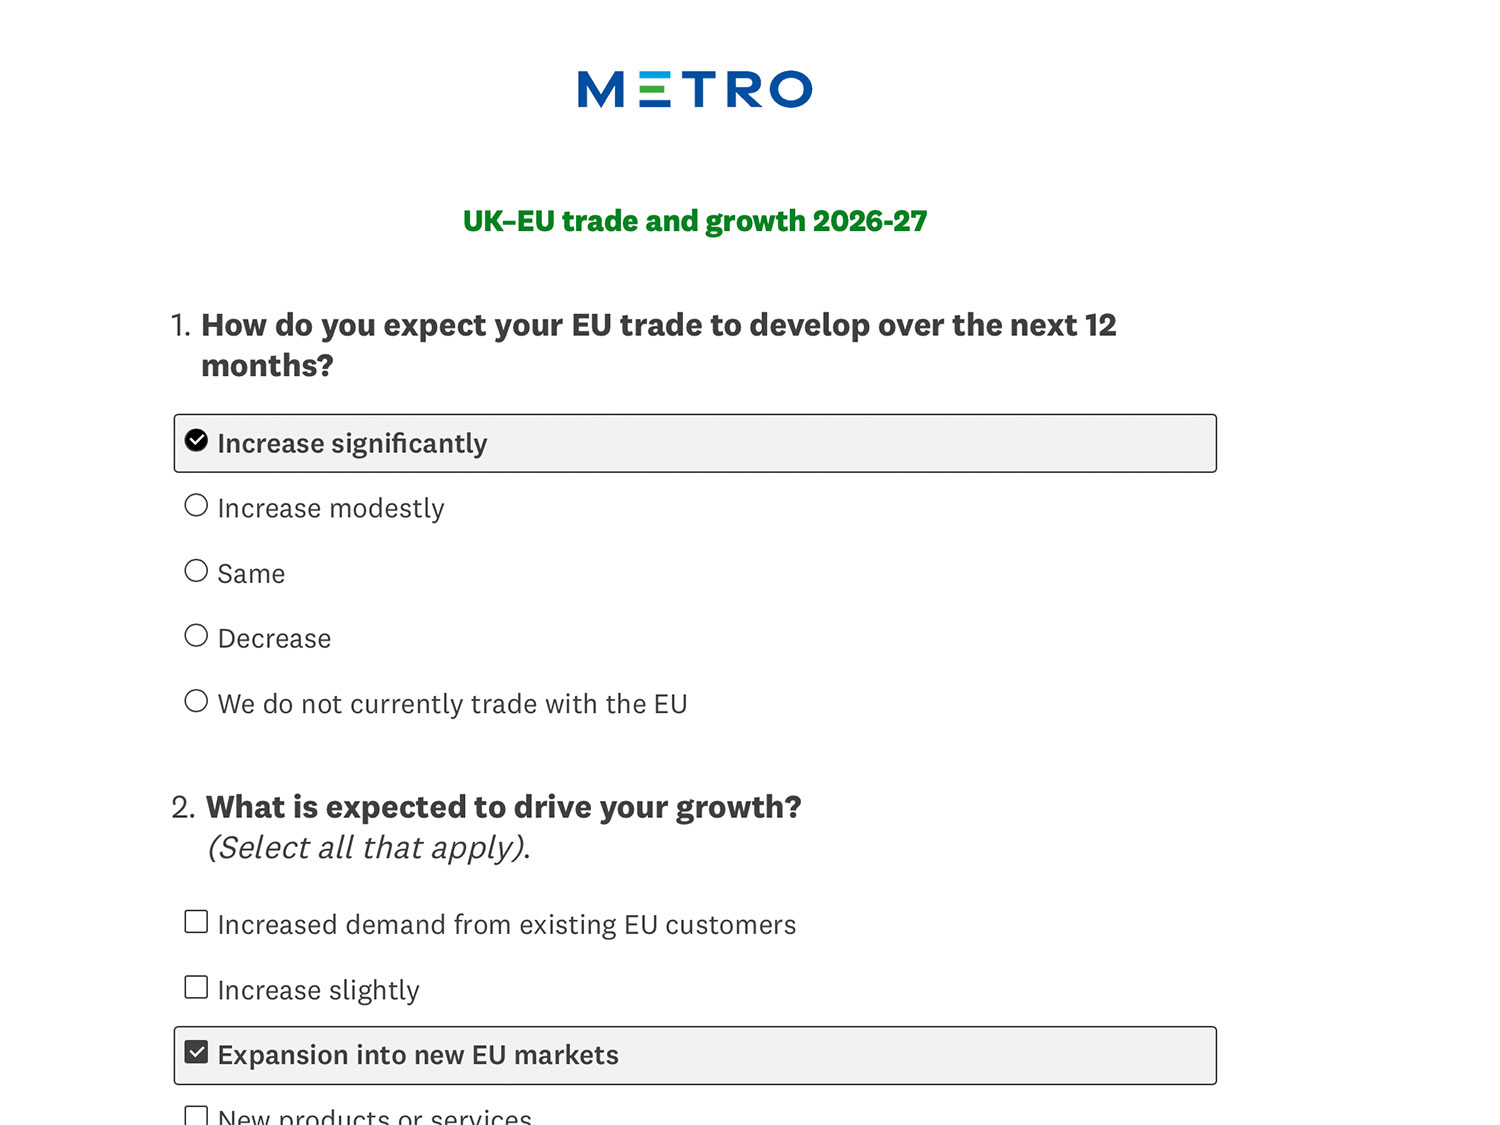
Almost three quarters expect EU trade to grow

The strongest signal from the survey is confidence.

More than 72% of respondents expect their EU trade to increase over the next 12 months, evenly divided between those anticipating significant growth and those expecting a more modest increase.

This is significant because the relationship has not become operationally simple. Companies continue to deal with customs declarations, VAT considerations, border processes and differing regulatory requirements, but these obstacles do not appear to have materially weakened their appetite to trade.

Respondents expecting growth are not primarily relying on established customers buying more.

Almost two-thirds identified new products or services as a growth driver, making this by far the most selected response. That distinction matters.

European growth appears increasingly linked to active business development rather than organic increases in existing trade. New products and markets can create more complex supply chains, placing greater emphasis on customs, VAT, transport and inventory planning.

Road remains dominant, but businesses are open to alternatives

Accompanied road freight remains the most widely used option, with 80% of respondents currently using it, but they are also using or considering a much broader mix of solutions.

Short-sea shipping already has over 60% penetration, while unaccompanied road freight is established among almost 50% of respondents. Rail and intermodal stand out because interest in considering these services (35%) is considerably higher than the current 18% usage.

Accompanied road freight may remain the default solution for many UK-EU movements, but businesses increasingly benefit from being able to switch between modes and accompanied or unaccompanied, depending on cost, capacity, urgency and border conditions.

Customs friction dominates customer concerns

When respondents were asked what would most improve their ability to trade efficiently with the EU, one issue stood well above the others, with 82% selecting fewer customs formalities and border delays.

Cost and regulatory certainty were the next largest concern, with 55% selecting lower transport and compliance costs, while the same proportion wanted greater clarity over future UK-EU trade rules.

More than a third highlighted simpler VAT and fiscal-representation arrangements.

Together, these findings suggest businesses are less concerned about whether European opportunities exist than about the administrative and financial complexity involved in exploiting them.

That includes avoiding customs errors, preventing unnecessary delays, establishing the correct VAT arrangements and understanding how regulatory changes will affect future supply chains.

More than a quarter of respondents identified simpler food and drink certification requirements as one of the changes that would improve EU trade.

Negotiations over sanitary and phytosanitary standards are intended to reduce some of the inspections, certificates and border requirements affecting agri-food movements.

Compliance support is the service customers value most

Perhaps the most decisive result came when businesses were asked which logistics services would make it easier to grow or operate within the EU. 80% selected customs clearance and compliance support.

Alternative road, short-sea or intermodal transport solutions ranked second at 40%, followed by fiscal representation at 30%.

If customs formalities are the principal obstacle, businesses naturally place the greatest value on expertise capable of removing that obstacle.

For a company entering a new EU market, getting classification, declarations, origin, documentation, VAT and fiscal obligations right from the outset can be just as important as selecting the right transport service.

What the findings mean for successful European trading

Taken together, the survey points towards several practical priorities for businesses targeting EU growth.

Build customs into the commercial strategy. Consider classification, origin, documentation and importer responsibilities before entering a market, rather than when goods are ready to move.

Look at total landed cost. Freight is only one component; customs administration, VAT, compliance, inventory and border delays can all affect profitability.

Maintain modal flexibility. Accompanied road remains important, but unaccompanied, short-sea and intermodal alternatives can provide valuable options as cost, capacity and requirements change.

Plan expansion market by market. New products and new markets can introduce different customs, VAT, regulatory and logistics requirements that need to be understood from the outset.

Watch UK-EU negotiations, but do not wait for them. Future agreements may reduce friction, but businesses can already improve European trade through better customs management, routing and supply-chain planning.

Customs, compliance, cost and regulatory uncertainty remain prominent concerns. Businesses best positioned for growth will be those that treat logistics and customs as part of their European market strategy rather than simply an operational requirement.

Metro combines European freight solutions with customs expertise and supply-chain support, helping businesses assess routes, manage cross-border requirements and build flexible solutions as their European trade develops.

As UK-EU arrangements continue to evolve, that combination of compliance, flexibility and forward planning can help turn confidence in European markets into sustainable growth.

EMAIL Andrew Smith, Metro’s Managing Director.