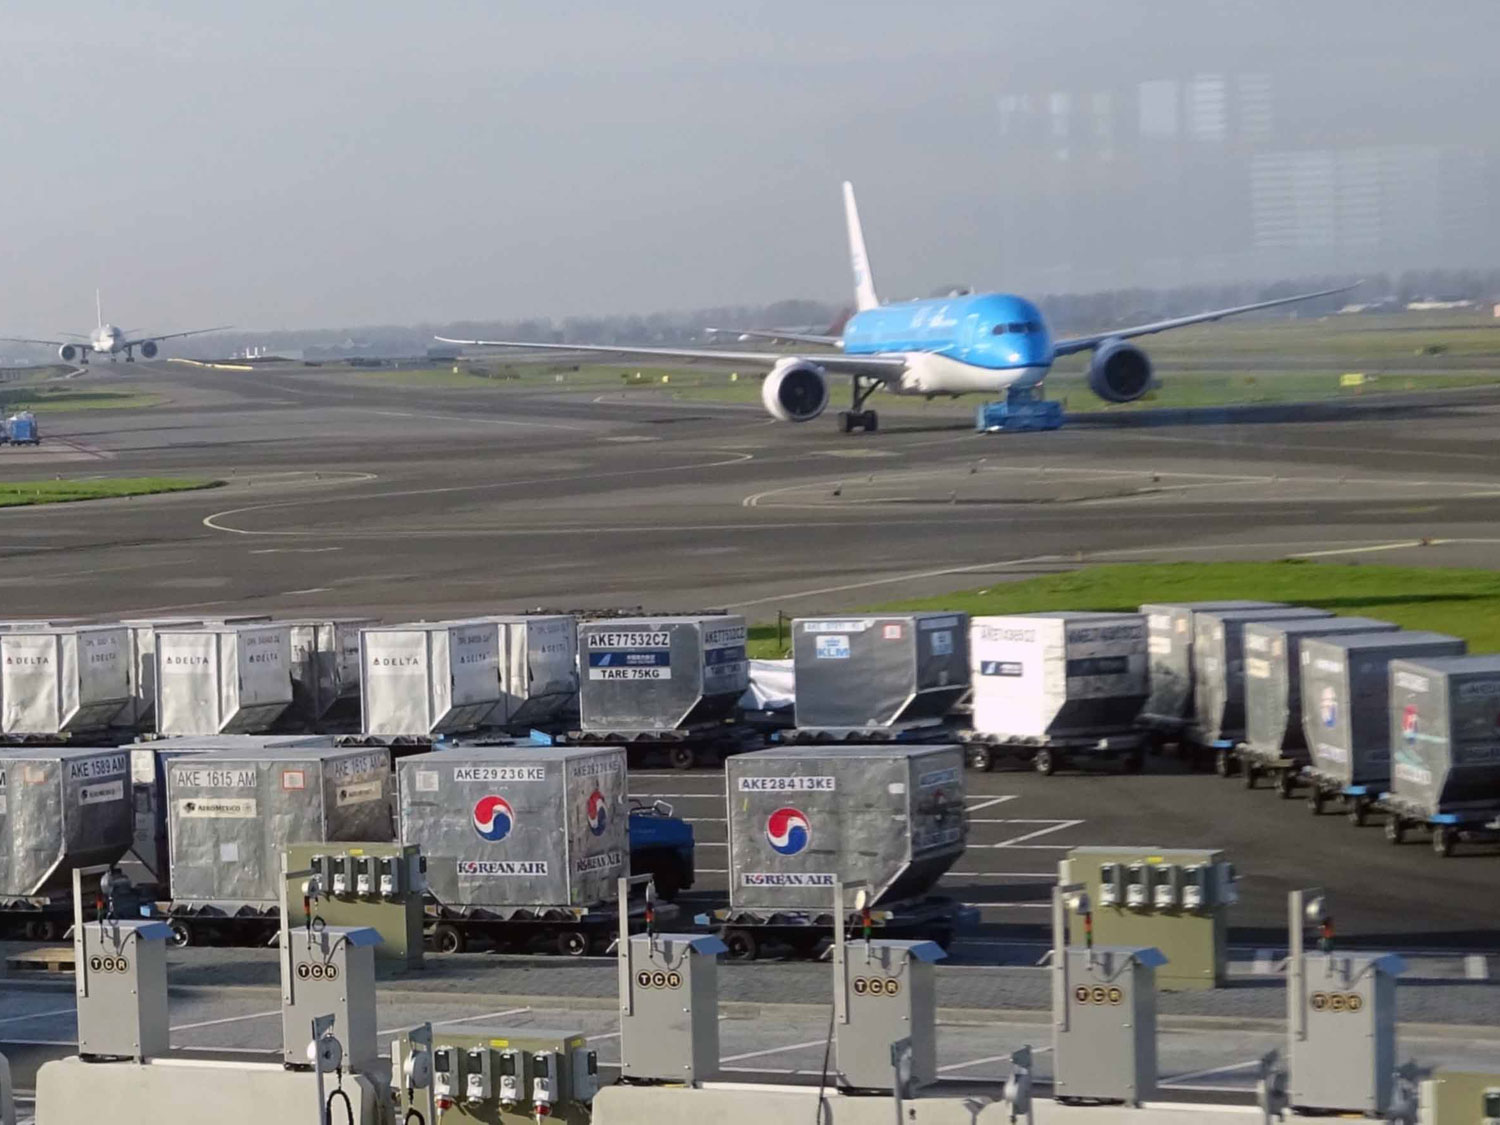
ULD on tarmac

Air freight market tightens ahead of autumn peak

Air freight enters the traditional peak-season build-up with a finely balanced market, as capacity reductions and resilient pricing create the potential for rapid tightening when Asian export demand accelerates.

The usual late-September surge may still be several weeks away, but UK importers have good reason to start planning now.

Asia–Europe demand softened during August, yet rates have shown little corresponding weakness. Airlines and freighter operators are adjusting capacity as cargo flows change, while higher fuel costs and stronger demand on alternative trade lanes are providing additional support.

That leaves limited spare capacity to absorb the traditional autumn increase – particularly if ocean freight disruption pushes urgent shipments towards air.

Softer demand is not delivering cheaper capacity

Asia Pacific–Europe chargeable weight fell 5% week on week and 14% year on year in week 33, continuing the softer trend evident since late June.

Changing e-commerce flows have contributed to the decline. China–Europe volumes were 8% lower year on year in week 32, while Hong Kong–Europe traffic fell 29%.

Despite that weakness, Asia Pacific–Europe spot rates remained flat in week 33 after rising 1% the previous week. China was particularly resilient, recording a 6% increase despite lower volumes.

The explanation lies partly on the supply side. Asia Pacific capacity contracted 2% in week 33 after declining 1% the previous week, limiting the downward pressure on rates.

Freighter deployment may tighten the market further. Stronger transpacific demand provides operators with an incentive to allocate aircraft towards the US, potentially reducing the capacity available for European cargo as peak season approaches.

China shows how quickly conditions can change

Recent disruption around Shanghai illustrates the vulnerability of available capacity.

Typhoon Dolphin caused more than 1,000 flight cancellations and contributed to an 8% weekly reduction in chargeable weight from Shanghai, while Shanghai–Europe volumes fell 7%.

The immediate disruption has eased, but severe weather and congestion across Chinese ocean gateways remain relevant to the air freight outlook. When container schedules become unreliable, urgent and time-sensitive cargo can quickly switch from ocean to air.

Even a relatively small modal shift can have a disproportionate effect on air freight capacity and pricing.

Golden Week could mark the turning point

The next significant test comes around China's Golden Week.

Factories traditionally accelerate production before the holiday, followed by another increase as operations resume and backlogs clear. October also brings the start of the main pre-Christmas replenishment cycle.

Demand then typically intensifies through November as retailers and e-commerce businesses prepare for Black Friday, Cyber Monday and Christmas.

This year, however, the market enters that period with capacity already responding closely to demand. That could make the transition from today's relatively balanced conditions to a tighter market particularly rapid.

Fuel costs, severe weather, changing freighter deployment and disruption to ocean services provide additional variables.

The opportunity is before the peak

For shippers, softer August volumes could offer a useful planning window rather than a reason to wait for lower rates.

Businesses with visibility of their autumn requirements can secure allocations earlier, consider alternative origins and gateways, and decide which shipments genuinely require premium air services.

Booking ahead of cargo-ready dates will become increasingly important as demand builds, particularly from China and other major Asian export markets. Flexible routing can also provide valuable alternatives when individual gateways or direct services tighten.

The key consideration is not simply today's air freight rate, but the availability of the right capacity when cargo needs to move.

Metro combines extensive Asian origin coverage with global airline relationships, flexible routing and multiple service levels to keep UK supply chains moving when peak-season capacity tightens. 

Share your autumn forecasts with Metro now and we can secure the capacity, routing and service strategy your cargo needs before the peak takes hold.

EMAIL Andrew Smith, Metro’s Managing Director.
India industrial revolution 1440x1080 1

India’s sourcing growth creates pressure at both ends of the supply chain

UK businesses sourcing from India face rising logistics costs before and after production, as more expensive Asian imports combine with tight westbound capacity and strong India–Europe demand.

India continues to strengthen its position as a manufacturing and sourcing alternative for UK and European businesses. But the cost of moving goods through the supply chains supporting that growth is rising.

The pressure starts well before finished products leave India. Many manufacturers rely on machinery, components, chemicals, electronics and other inputs imported from China and neighbouring Asian markets. Freight costs on those inbound routes have risen sharply, increasing the cost base for Indian production.

At the same time, strong exports are tightening India–Europe container capacity and pushing westbound freight costs higher.

For UK buyers, that creates a potential double freight squeeze, with logistics inflation entering the product cost upstream before another layer is added on the journey to Europe.

Asian imports into India become more expensive

The first pressure point is emerging on eastbound services into India.

During August, Shanghai–Nhava Sheva spot rates have almost doubled compared with July, while Shanghai–Chennai rates have increased by around 60%. Costs from other Asian origins, including Singapore, have also risen significantly.

Strong seasonal imports ahead of India's festival period are contributing to demand, while congestion at major Asian hubs has disrupted schedules and tightened available capacity.

For Indian importers, the impact extends beyond freight rates. Changing schedules and less predictable transit times make it harder to manage inbound inventory and maintain reliable production flows.

Higher freight feeds into manufacturing costs

The significance for UK buyers comes from China's deep integration into Indian manufacturing.

Rising transport costs for the raw materials and components feeding Indian factories may initially be absorbed through manufacturer margins. If elevated costs persist, however, some will inevitably feed into production costs and finished-product pricing.

That creates a supply-chain exposure that may be difficult to see when procurement decisions focus primarily on the factory price.

An Indian-made product can already contain significant logistics costs before it enters a container for its journey to the UK.

Strong exports tighten the westbound market

The second pressure point is India–Europe shipping.

Indian containerised exports to Europe reached an estimated 518,000 TEU during the first half of 2026, with stronger-than-expected demand creating a pronounced capacity squeeze.

Westbound rates increased again during August and are approaching levels last experienced around four years ago. Space has become increasingly difficult to secure, with some leading India–Europe services selling out several weeks ahead and additional spot capacity appearing only as carriers release allocations.

The problem is not simply growing demand. Available capacity has struggled to keep pace.

Blank sailings, congestion and rolled cargo at Nhava Sheva and Mundra are reducing effective space, while some capacity has been redirected towards growing Latin American flows using Indian ports for transhipment.

For cargo owners, guaranteed space can therefore command a premium, while less flexible shipments face greater rollover and delay risks.

Look beyond the supplier price

India's manufacturing scale and expanding trade relationships continue to make it an important sourcing market. But the changing freight environment reinforces the need to assess the complete landed cost of sourcing there.

A product assembled using Chinese or other Asian components may now carry substantially higher inbound logistics costs. Moving the finished goods from India to the UK then adds a second layer of freight inflation.

For lower-margin or freight-intensive products in particular, those combined costs could materially affect sourcing economics.

Timing matters too. With strong westbound bookings and constrained capacity, waiting for cheaper freight could leave importers competing for even tighter space.

Businesses can reduce that exposure by understanding upstream supply flows, consolidating shipments where appropriate and planning westbound capacity earlier.

Manage the whole supply chain, not just the final leg

The growing relationship between Chinese inputs, Indian manufacturing and European demand means these movements cannot always be managed effectively in isolation.

Metro can connect the complete Asia–India–UK supply chain, providing visibility from upstream suppliers through Indian production and onward to the UK. 

With extensive Indian based capabilities, global carrier relationships, consolidation and alternative routing options, we can identify where cost and capacity pressures are building and act before they reach your bottom line. EMAIL Andrew Smith, Metro’s Managing Director, to learn about protecting your landed cost from origin to destination.

Shanghai Hongqiao Airport 1440x1080 1

Regional airfreight demand and capacity diverge

The global airfreight market is becoming increasingly difficult to predict through headline averages. While worldwide volumes remain above last year’s levels, conditions are diverging sharply between individual origins and trade lanes as de-minimis regulation, technology demand, weather disruption and capacity shifts reshape cargo flows.

For UK, European and US shippers, this means the availability and cost of airfreight increasingly depend on exactly where cargo originates and which carrier networks it uses. Asia may appear relatively balanced overall, while individual gateways can experience much tighter capacity or rapidly changing rates.

The latest WorldACD data reinforces that picture. Global tonnage fell 4% in the latest reporting week, but remained 1% higher year on year, while individual Asian origins recorded movements ranging from double-digit growth to double-digit declines. 

Asia–Europe adjusts to e-commerce changes and shifting capacity

Asia–Europe is undergoing a significant adjustment following changes to the EU’s treatment of low-value e-commerce shipments.

The introduction of a €3 charge on packages valued below €150 at the beginning of July has affected one of air cargo’s most important sources of recent growth. By week 32, China–Europe e-commerce volumes were 8% lower year on year, while Hong Kong–Europe volumes were down almost 30%.

Overall Asia Pacific–Europe tonnage fell, yet rates moved in the opposite direction on some important lanes, with Asia Pacific–Europe spot pricing increasing 1%, led by a 6% increase from China and 3% from Hong Kong.

This apparent contradiction reflects changes in available capacity. Freighter capacity previously deployed for e-commerce traffic appears to be moving between markets, allowing pricing to strengthen even as overall volumes soften.

Weather is adding another variable. Typhoon Dolphin caused more than 1,000 flight cancellations in Shanghai, contributing to an 8% week-on-week decline in total air cargo from the gateway. Disruption to Chinese seaports could subsequently generate some modal shift from ocean to air as businesses try to recover delayed shipments.

“Airfreight is becoming much more localised,” says Phil Morris, Metro’s Head of Airfreight. “A regional average can suggest that capacity is plentiful, but that may not reflect what is happening at an individual origin. Shippers increasingly need to look at the cargo mix, available capacity and conditions at specific gateways rather than relying on the headline market.”

Transpacific technology demand creates localised pressure

The transpacific market presents a different picture. Asia Pacific–US tonnage declined 4% week on week in early August and spot rates fell 3%, suggesting a relatively balanced market at regional level. But significant variations sit beneath those figures.

Japan–US volumes increased 12% in a single week, while Taiwan and Indonesia’s volumes were down around 10%. High-value technology cargo is also supporting demand from Japan, South Korea, Taiwan, Thailand and Vietnam.

AI servers, semiconductors, electronics and associated data-centre infrastructure are particularly important because these products are high-value, time-sensitive and often linked to fixed deployment schedules. Airfreight can therefore remain the preferred mode even when ocean capacity is available.

That demand can have consequences for businesses outside the technology sector. Cargo moving through the same airports, using the same freighter capacity or competing for uplift during concentrated production periods can encounter tighter availability and firmer pricing.

“For shippers, it is important to understand what else is moving from their origin,” Phil adds. “A surge in one high-value vertical can tighten an airport very quickly. That makes early conversations about capacity and alternative routings particularly valuable, especially as we approach Q4.”

Further typhoon activity across Asia could amplify these localised pressures if flight cancellations or airport disruption coincide with peaks in technology exports.

Transatlantic capacity remains comparatively accessible

The transatlantic market currently offers a more stable environment, with capacity generally available as the summer passenger schedule provides substantial belly-hold space.

WorldACD data shows North America–Europe volumes fell 5% over the latest two-week comparison, while European exports to North America increased 3%. This creates different conditions depending on direction rather than a single transatlantic trend.

The current availability provides an opportunity for shippers with flexible requirements, but the position could change as passenger schedules transition from summer to winter and belly capacity reduces.

The broader lesson is that airfreight has moved away from a market where one global trend reliably describes conditions everywhere. Regulation is reshaping e-commerce demand, technology is concentrating demand around particular Asian origins, weather can remove capacity with little warning and seasonal passenger schedules continue to influence individual corridors.

Shippers can respond by separating genuinely time-critical freight from cargo with greater delivery flexibility, securing capacity earlier on constrained origins and maintaining alternative gateway and routing options.

Metro’s global airfreight network gives shippers the visibility and flexibility to respond to these increasingly localised conditions. Our airfreight teams monitor capacity, rates, weather disruption and demand at origin level, identifying where space is tightening and where alternative gateways, carriers or routings can provide an advantage. 

Whether you are moving cargo from Asia to the UK, Europe or US, or across the Atlantic, talk to Metro early so we can secure the capacity and routing that best protects your cost, transit time and delivery commitments.

To learn more, EMAIL Managing Director Andrew Smith today

Suez MSC vessel

Red Sea return gathers pace, but risks remain

Container shipping through the Red Sea and Suez Canal is gradually increasing as major carriers test a return to the shorter Asia–Europe route, potentially signalling an important change for global supply chains.

But this is far from a return to normal. Recent deadly attacks demonstrate that security conditions remain volatile, while carriers are assessing individual sailings carefully and retaining the option to divert around the Cape of Good Hope at short notice.

For shippers, the potential benefits of shorter transit times must therefore be weighed against continuing routing uncertainty, war-risk insurance costs and the possibility that a broader return to Suez could create new congestion elsewhere in the network.

Carriers cautiously increase Suez transits

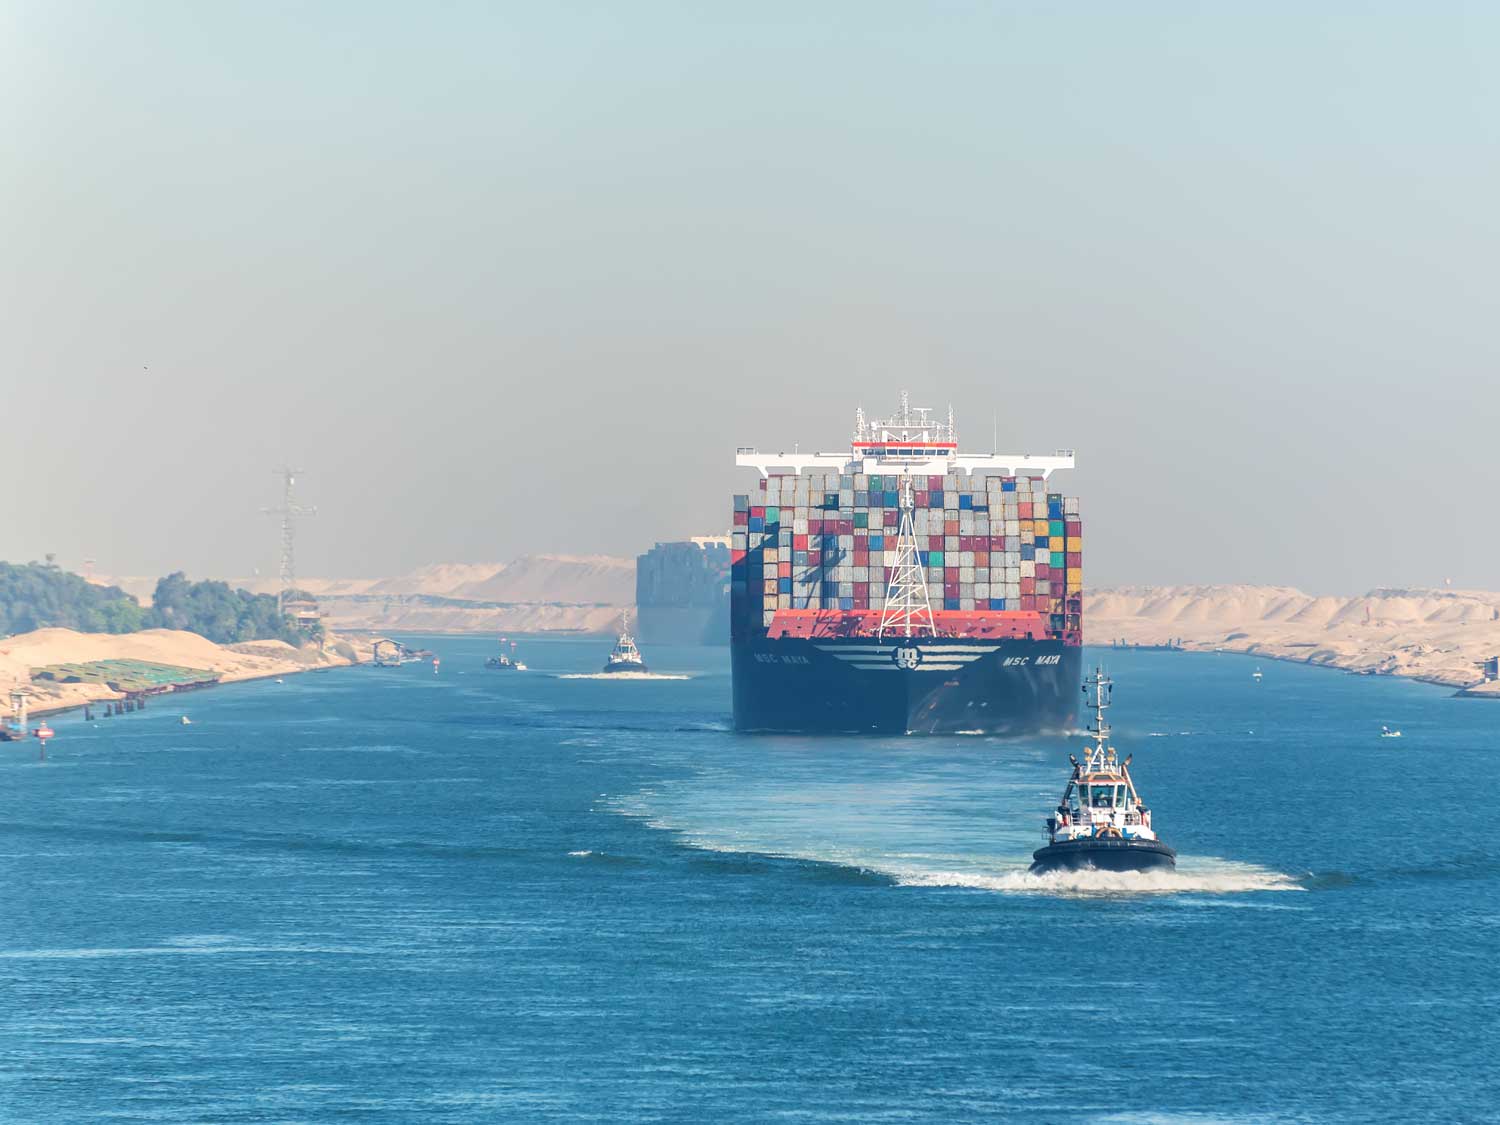
Maersk currently has four services passing through the Bab el-Mandeb Strait in both directions each week, equivalent to around one-third of its normal service pattern. The carrier believes current intelligence and security assessments support a gradual return, although every sailing remains subject to an individual risk assessment.

Hapag-Lloyd is taking a similarly cautious approach and expects any increase in Suez services to happen progressively rather than through an immediate network-wide switch.

Other carriers are also adding capacity. Cosco has reopened bookings for Red Sea services and is preparing a Far East–Red Sea rotation through Bab el-Mandeb, while CMA CGM already operates several services using Suez. The Gemini network has also moved additional Asia–Mediterranean services back towards the Red Sea.

The operational attraction is significant. Restoring the Suez route reduces the additional sailing distance created by Cape diversions and could ultimately release vessel and container capacity into a market already experiencing equipment and space constraints.

That is particularly relevant following severe weather disruption in China. Typhoon Dolphin closed operations at Ningbo and Shanghai during 7–8 August, leaving more than 2.4 million TEU of capacity across networks affected by the shutdown and subsequent congestion. With backlogs potentially taking weeks to clear, shorter vessel rotations could help carriers make more effective use of constrained fleets and equipment.

However, recent traffic data highlights how quickly sentiment can change. Total Red Sea/Suez transits fell from 255 vessels to 222 in a week, as operators adopted a more cautious approach following the renewed Houthi attacks.

Security risk translates directly into costs

The biggest obstacle to a sustained return remains security. A deadly attack on a commercial vessel off Yemen in August reinforced the wider and continuing threat to shipping, while missile and drone attacks have maintained uncertainty around the Bab el-Mandeb corridor.

Carriers are consequently treating Red Sea routings as conditional rather than permanent. A deterioration in security could prompt individual sailings, entire services or wider networks to return to the Cape route with relatively little notice.

For cargo owners, that uncertainty has an important financial dimension. Standard marine cargo policies typically exclude war risks, meaning shipments entering designated high-risk areas may require specific endorsements. Current market indications suggest Red Sea war-risk cover can cost approximately 0.5% to more than 1% of insured cargo value per voyage. Carriers may also pass additional security and operating expenses to customers through specialised risk surcharges.

Insurance availability itself can vary according to the cargo, vessel and parties involved. Some underwriters may restrict or refuse particular risks, while routing changes need to be declared correctly to avoid potential coverage issues.

Shippers should therefore consider the total cost and risk of the routing, rather than assuming that a shorter Suez transit automatically produces a cheaper supply chain.

A return could create another wave of disruption

There is another complication. A large-scale return to Suez could initially increase congestion rather than improve schedule reliability.

Cape diversions have fundamentally altered vessel arrival patterns. Switching significant numbers of ships back to the shorter route would change those patterns again, potentially creating bunching as vessels reach European terminals earlier and in different sequences.

That is particularly important while European ports are already managing congestion and inland transport constraints that are heightened by limited barge availability. Carriers are therefore planning phased returns partly to avoid overwhelming terminals.

For shippers, the next phase of the Red Sea situation could consequently bring both opportunity and uncertainty. Shorter routings may improve transit times and eventually release capacity, but security assessments, insurance premiums, surcharges and rapidly changing schedules will remain important considerations.

Metro monitors carrier routings, security developments, insurance implications and schedule changes across the Red Sea, Suez and Cape alternatives, helping customers understand the true cost and operational impact of each option. With conditions capable of changing from one sailing to the next, talk to Metro before booking critical cargo so we can assess the routing, timing, cost and risk that best protect your supply chain.

To learn more, EMAIL Managing Director Andrew Smith today.