Ningbo

Asia–Europe freight rates rebound as carriers tighten capacity

Ocean freight rates on Asia–Europe trades are rising again after months of downward pressure, but contrasting market indicators and increasing blank sailings suggest the recovery is being driven as much by carrier capacity management as underlying cargo demand.

The Asia–Europe container market has entered a new phase of price volatility, with shipping lines attempting to strengthen freight rates ahead of November and the approaching annual contract negotiation season.

After an extended period of softening spot rates, October has delivered two consecutive weeks of increases. However, the recovery remains uneven, with conflicting freight indexes and relatively subdued demand raising questions about whether higher prices can be sustained.

For shippers, the immediate challenge is distinguishing between genuine market tightening and temporary price movements created by changes to available capacity.

Spot rates reverse their downward trend

Drewry's World Container Index recorded a 6% increase on Shanghai–Rotterdam and a 7% rise on Shanghai–Genoa in mid-October, reversing several weeks of declining prices. 

The recovery continued into the following week, with Shanghai–Rotterdam increasing another 3% and Shanghai–Genoa rising 5% in the assessment published on 22 October.

Across the two weeks, this represents cumulative increases of approximately 9% and 12% respectively.

The broader Drewry index increased 2% in the latest assessment, reflecting firmer pricing across several major east–west trades.

However, not every benchmark supports the same interpretation and while Drewry recorded rising Asia–Europe rates in mid-October, another freight index reported a 7% decline on Asia–North Europe.

Different methodologies, reporting periods and underlying transactions explain some of the divergence, but the contrasting readings reinforce the absence of a consistent recovery across the market.

Shipping lines withdraw capacity to support prices

With demand showing limited signs of significant acceleration, carriers are turning increasingly to capacity management.

Drewry reported eight blank sailings scheduled on Asia–Europe services for the week beginning 26 October, compared with two the preceding week.

The broader outlook confirms that capacity adjustments will continue through November.

Across the major east–west trades, 56 sailings are expected to be cancelled between weeks 44 and 48, representing approximately 8% of the 714 scheduled departures.

Asia–Europe and Mediterranean services account for 54% of these cancellations, making them the principal focus of carrier capacity management.

Although 92% of scheduled services are still expected to operate, cancellations can have a disproportionate effect on individual departure weeks, ports and carrier networks.

For shippers, this creates a familiar contradiction: substantial overall vessel capacity alongside restricted availability on particular services.

Blank sailings can also concentrate cargo onto fewer vessels, increasing the risk of rollovers and schedule disruption.

November rate increases face a demand test

Alongside withdrawing capacity, shipping lines are introducing higher Freight All Kinds (FAK) rates.

New pricing announced for mid-October targeted increases across North Europe and Mediterranean destinations, although some offers were subsequently revised downwards.

Further increases have been announced for 1 November, with Mediterranean targets generally higher than those for North Europe.

Shipping lines are attempting to establish firmer pricing ahead of annual contract discussions, but without a sustained increase in cargo volumes, higher rates may prove difficult to maintain.

The coming weeks will therefore test whether capacity withdrawals can support the recovery or whether additional available space and competitive pricing will limit further increases.

Operational developments could also influence the balance between capacity and demand.

Asian port congestion has shown signs of improvement, with vessel waiting times at Shanghai falling from 97 hours in week 38 to 38 hours in week 42.

This improvement should help restore schedule efficiency and release vessel capacity previously absorbed by delays.

What this means for shippers

The latest developments suggest that Asia–Europe freight rates will remain volatile through the remainder of 2026. Recent increases have been supported by carrier capacity management and pricing initiatives, but subdued demand and discounted offers suggest that further fluctuations are likely.

Service reliability remains just as important as pricing, with blank sailings reducing departure options and increasing the risk of cargo being rolled. Meanwhile, improving Asian port operations and the gradual return of services through the Suez Canal could release additional capacity, changing the balance between supply and demand.

Shippers should therefore assess available services, booking windows and delivery requirements alongside freight rate movements, rather than relying solely on headline market indexes.

Metro: Turning market volatility into better shipping decisions

When freight rates fluctuate and carriers adjust capacity, the lowest quoted price is not always the best shipping solution.

Metro combines established relationships with leading ocean carriers, global freight procurement expertise and extensive origin and destination capabilities to help customers make informed decisions across Asia–Europe trades.

Our teams monitor carrier schedules, capacity withdrawals, freight pricing and port conditions, identifying alternative services, gateways and consolidation opportunities when market conditions change.

Whether you're reviewing November bookings, preparing for 2027 contract negotiations or looking to improve schedule reliability, Metro can help you balance competitive pricing with dependable capacity and delivery performance.
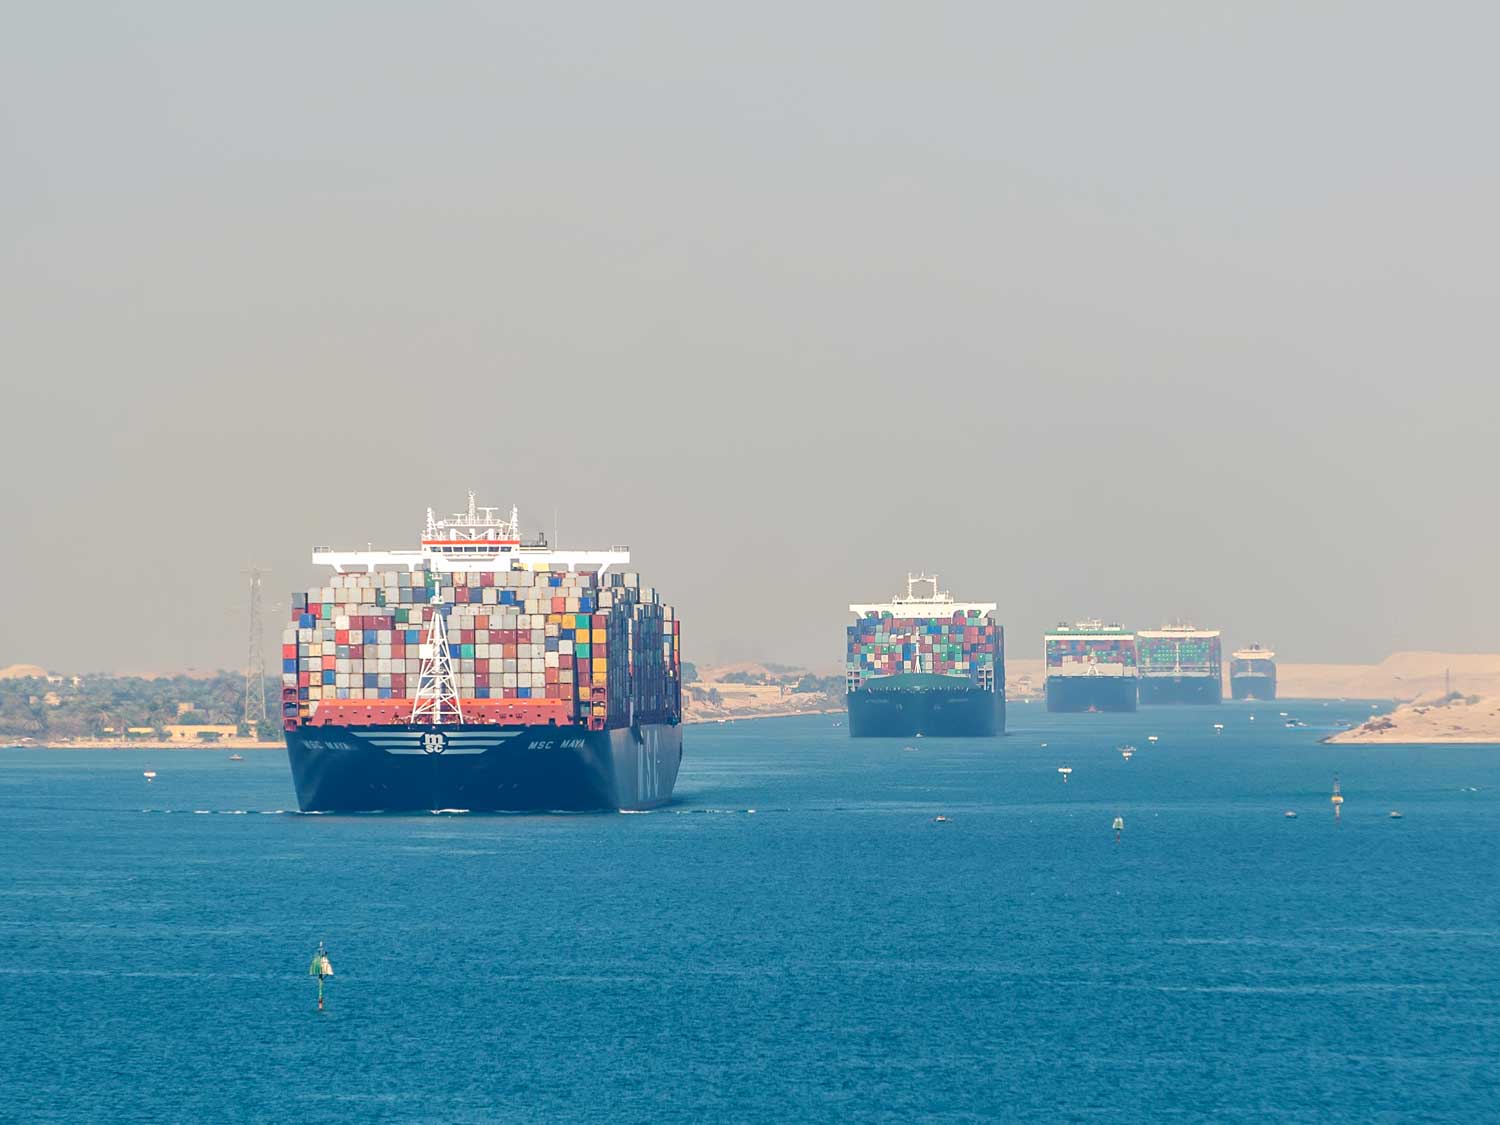
Suez convoy

Suez Canal return gathers pace

Nearly two-thirds of Far East–Europe container shipping capacity is now operating through the Red Sea and Suez Canal, marking a significant shift away from Cape of Good Hope diversions, although security concerns and changing service rotations mean the return remains uneven.

After almost three years of widespread diversions around southern Africa, container shipping is progressively returning to one of the world's most important trade corridors.

Major shipping lines have restored Suez transits across a growing number of Asia–Europe services, with the recovery now extending to selected routes connecting Asia and the US East Coast.

The transition could shorten delivery times, reduce fuel consumption and eventually release substantial vessel capacity. However, mixed routings, ongoing security assessments and potential congestion at European ports mean the benefits will not be immediate or consistent across every service.

Nearly two-thirds of Asia–Europe capacity returns

The scale of the recovery is becoming increasingly clear.

63%
Far East–Europe capacity using the Red Sea
70%
Far East–Mediterranean capacity
58%
Far East–North Europe capacity
24 of 46
Direct Far East–Europe services transiting the Red Sea

Analysis of the ten largest container shipping networks shows that approximately 5.5 million TEU of the 8.7 million TEU deployed between the Far East and Europe is now assigned to services using the Red Sea.

The Mediterranean trades are leading the recovery, with around 70% of capacity back on Suez routings, compared with 58% on Far East–North Europe services.

However, the return is not uniform.

Some services use the Suez Canal westbound towards Europe but continue to route eastbound voyages around the Cape of Good Hope.

This approach allows carriers to reintroduce shorter routings selectively while retaining flexibility if regional security conditions deteriorate.

Major carriers accelerate their return

The shift has gathered momentum since the summer, with several major shipping groups progressively restoring services.

MSC resumed Suez transits in August and now operates 11 loops through the waterway, representing approximately 2.2 million TEU of deployed capacity.

Maersk and Hapag-Lloyd have also expanded their use of the route, with nine alliance services representing around 1.76 million TEU.

CMA CGM maintained a presence through the Suez Canal during the disruption and has subsequently expanded its operations, while COSCO and OOCL have restored six services with combined deployed capacity of approximately 1.27 million TEU.

The Premier Alliance has also begun returning selected services, adding further momentum.

With some networks operating through Suez in both directions, others retaining Cape diversions, and several using different routes for outbound and return voyages, individual service patterns remain important when assessing transit times and reliability.

Weekly Suez traffic continues to strengthen

The recovery is also evident in actual canal traffic. Containership transits increased from 54 in week 41 to 55 in week 42, extending a period of improving volumes.

The latest figures indicate that more carriers are progressively restoring services rather than relying solely on occasional voyages.

However, the canal remains well below its historical potential, and the return is taking place against a backdrop of continuing security concerns around the Red Sea and Bab-el-Mandeb Strait.

For shipping lines, the commercial advantages of Suez are substantial. Shorter voyages can reduce fuel consumption, lower operating costs and potentially allow carriers to maintain weekly services with fewer vessels.

With bunker prices remaining elevated, these savings provide a strong incentive to restore shorter routes wherever security assessments permit.

Asia–US East Coast services begin returning

The recovery is no longer confined to Europe. MSC and Zim have resumed Suez transits in both directions on their shared Asia–US East Coast service, marking a further development in the restoration of global shipping networks.

The first northbound sailing departed Singapore on 18 October, with arrival in New York–New Jersey expected on 18 November.

Other services connecting India and the Middle East with the US East Coast have also resumed Suez routings, although some continue to use the Cape of Good Hope in the opposite direction.

For shippers, the potential transit-time benefits vary considerably. Asia–Europe services returning to Suez have achieved average transit-time improvements of approximately seven days.

However, North American services have experienced mixed results, with some achieving modest savings and others recording longer overall transit times despite using the shorter canal route.

Port rotations, transhipment arrangements and congestion at intermediate gateways can offset the theoretical advantages of a shorter voyage.

Full return could happen in early 2027

Industry expectations increasingly point towards a broader restoration of Suez services during the first quarter of 2027.

However, this remains a scenario rather than a confirmed timetable.

Maersk has discussed the possibility of further service returns, but has emphasised that no definitive schedule has been announced and that future changes will depend on security conditions, operational planning and consultation with partners and customers.

The pace of recovery will also depend on the ability of ports and inland transport networks to accommodate changing vessel arrival patterns.

Rotterdam and Antwerp-Bruges are already experiencing challenges associated with overlapping schedules and fluctuating volumes as services transition between Cape and Suez routings.

A faster return could release significant effective vessel capacity into the market, potentially increasing pressure on ocean freight rates.

At the same time, changes to vessel rotations and arrival patterns could create temporary congestion, schedule disruption and equipment imbalances.

Changing ocean networks offer supply-chain opportunities

The return to Suez could reshape ocean freight costs, transit times and capacity availability. Making the most of these changes requires accurate market intelligence and the flexibility to respond.

Our teams monitor carrier routing decisions, vessel schedules, port conditions and freight rates, identifying opportunities to improve transit times, manage costs and maintain reliable delivery performance.

Whether you're reviewing Asia–Europe or trans-Pacific shipping arrangements, evaluating India–US connections or preparing for further network changes in 2027, Metro can help you understand the implications and identify practical alternatives.

Contact Metro to review your ocean freight strategy and take advantage of emerging routing, capacity and cost opportunities as the Suez Canal recovery gathers pace.

Forklift loading container

Asia–UK ocean market faces volatile October as capacity shifts

UK importers face an unusually volatile October as falling Asia–Europe freight rates collide with excess scheduled capacity, returning Suez services, short-notice blank sailings and continuing disruption across Asian ports.

Ocean carriers are attempting to halt a 12-week decline in Asia–Europe rates with increases planned for the second half of October. However, the traditional slowdown following China's Golden Week (1–7 October) could make those increases difficult to sustain unless carriers withdraw significant capacity.

For shippers, lower underlying demand may therefore bring temporarily cheaper freight but not necessarily more reliable supply chains.

Golden Week creates a capacity imbalance

Asia–North Europe scheduled capacity is unusually high. Around 1.5m TEU is scheduled across the four-week Golden Week period, 27% more than last year and 60% above pre-pandemic averages.

But those figures overstate the amount of genuinely new capacity entering the market.

Typhoon disruption and severe congestion at Chinese ports have pushed vessels significantly behind schedule. As delayed ships return to service alongside their normally scheduled counterparts, 12 double sailings are expected across Asia–Europe and Mediterranean services during the first two weeks of October.

At the same time, Golden Week factory closures will reduce export volumes.

The result could be a rapid shift from constrained effective capacity to temporary oversupply as delayed vessels return and cargo volumes fall.

Carriers are likely to respond with significant blank sailings, potentially announced at relatively short notice. That could leave mid-to-late October schedules particularly vulnerable to cancellations, rolled cargo and departure changes.

Suez return adds more effective capacity

The gradual return of Asia–Europe services to the Suez Canal adds another variable.

Faster Suez routings effectively release vessel capacity because ships can complete round voyages considerably faster than when sailing around the Cape of Good Hope.

Asia–North Europe services remain cautious, but the shift is gathering pace. Around 30% of backhaul capacity was using Suez during September, with this expected to reach approximately 40% in October.

Several additional services are now moving back to the canal, primarily to return delayed vessels to Asia more quickly following severe port congestion.

For UK importers, increased Suez utilisation could eventually support shorter transit times and greater capacity. In the immediate term, however, changing vessel rotations and the possibility of further network adjustments add even more uncertainty to schedules.

Security conditions in the Red Sea also remain fluid, meaning carriers retain the option of reverting to Cape routings if their risk assessments change.

Reliability remains the bigger concern

Freight rates from Asia to North Europe have been under pressure for some time, which is why carriers have announced increases for the second half of October in an attempt to reverse that trend.

But price is only part of the equation. Multiple typhoons in seven weeks created severe disruption at Shanghai, Ningbo-Zhoushan and Yantian, with berthing delays extending up to 14 days, with on-time performance on services falling to just 62% in August, while average delays for late Asia–Europe vessels reached five days.

Residual disruption is expected to continue through October as vessel bunching, accumulated container backlogs and post-Golden Week capacity adjustments work through the network.

The immediate risk for UK importers is therefore less about a shortage of nominal vessel capacity and more about whether booked capacity operates when expected.

European disruption adds another risk

Conditions at destination also require attention. German port workers are currently voting on authorisation for indefinite strike action after rejecting the latest employer wage offer. The ballot closes on 1 October, with Hamburg, Bremen, Bremerhaven and other major German ports potentially affected if industrial action follows.

German freight interests are already preparing for possible restrictions affecting terminal handling and pre- and on-carriage.

While this does not directly affect UK ports, significant disruption at major North European gateways could create wider network effects as carriers adjust rotations and cargo moves through alternative ports.

The transatlantic market is moving differently. Europe–US East Coast spot rates remain substantially above last year's levels, while carriers are managing winter capacity through blank sailings. This makes early allocation planning particularly important for exporters relying on North Atlantic services.

Flexibility will matter through Q4

October therefore presents an unusual combination for Asia–UK shippers.

Underlying rates are soft, substantial scheduled capacity is entering the market and shorter Suez routings are gradually restoring effective vessel supply. Yet congestion, poor schedule reliability and likely carrier capacity management mean the operational environment could remain unpredictable, with rates likely to harden.

Shippers should consequently avoid interpreting softer rates as a signal that the market has normalised.

Metro's established carrier relationships and extensive global network give our teams access to multiple services, routings and consolidation options across the Asia–UK trade. By monitoring capacity, schedules and gateway conditions, we can identify alternatives when blank sailings, congestion or network changes threaten planned movements.

Talk to Metro about your Q4 Asia–UK requirements and how alternative carriers, routings and consolidation options can provide greater flexibility as the market adjusts.

Aircraft and moon

Airfreight market strengthens as peak season nears

Global air cargo demand and rates are strengthening ahead of the traditional peak season, with rising volumes, firm pricing and higher fuel costs creating a more robust market as October begins.

The latest TAC Index and WorldACD data point to increasing momentum as the industry moves towards its busiest months, although conditions continue to vary significantly by trade lane.

The global Baltic Air Freight Index gained a further 0.6% in the seven days to 28 September, extending a series of modest weekly increases and leaving rates nearly 22% above the same point last year.

Meanwhile, WorldACD recorded a fourth consecutive weekly increase in global chargeable weight in week 38, with tonnages rising 2% week on week and 8% year on year.

Demand builds across major origin markets

The underlying demand picture is increasingly positive. Asia Pacific remained one of the strongest contributors, with origin tonnages 11% higher year on year. North American volumes increased 14% week on week following the Labor Day dip and were 8% above last year's level, while European origin volumes were 6% higher year on year.

Rates are also substantially above 2025 levels. WorldACD's average worldwide full-market rate was 24% higher year on year in week 38, while average spot rates were 33% higher.

Asia Pacific spot rates were 30% above last year, with Europe up 29% and North America 34%.

TAC Index data for the following week suggests that firmness continued into the end of September, with its global index extending its year-on-year increase to 21.7%.

The backdrop is being reinforced by significantly higher fuel costs. TAC reported that jet fuel prices were 106% above their level a year earlier by 25 September, adding another source of upward pressure as the market approaches peak.

Asia markets gather momentum

Asia is likely to be central to the developing peak-season picture. TAC recorded a 3% weekly increase in its Hong Kong outbound index during the week to 28 September, taking it 20.6% above last year. Rates from India also increased strongly, while China-Europe pricing continued to firm as the market adjusted following changes affecting low-value parcel traffic.

WorldACD similarly recorded further increases in Asia Pacific-Europe spot rates during week 38, including gains from mainland China, Hong Kong, Japan and South Korea.

The transpacific remains particularly strong. Asia Pacific-US demand was 13% higher year on year, including significant growth from South Korea, Japan and China. Average spot rates on the trade were broadly stable week on week but approximately 40% above their level a year earlier.

The picture towards Europe is more mixed. China and Hong Kong volumes have yet to recover fully from the disruption that followed the removal of the EU de minimis exemption in July, but pricing has begun moving higher on several key origins.

Golden Week adds to peak-season pressure

Attention is now turning to China's National Day Golden Week (1–7 October), which follows closely behind the Mid-Autumn Festival (25–27 September) and compresses production, export handovers and freight planning into a short period.

Metro’s local partners are already reporting stronger general cargo demand from North China as shippers move goods before the holiday, while transpacific demand from Southern China is also increasing.

Available capacity and additional charter operations have so far helped contain more dramatic rate movements. However, the combination of recovering volumes, firm year-on-year pricing, higher fuel costs and the traditional Q4 uplift creates the potential for conditions to tighten further as October progresses.

Worldwide international capacity was only 4% higher year on year in week 38, compared with an 8% increase in tonnage. Capacity also remains constrained in some markets affected by geopolitical disruption, particularly the Gulf.

Early planning for the Q4 peak

The latest figures do not point to a uniform capacity squeeze, but they do suggest that the airfreight market is entering peak season from a considerably stronger position than a year ago.

With demand building, rates already elevated year on year and conditions varying sharply between origins and trade lanes, access to the right capacity at the right time will become increasingly important through the final quarter.

Metro's global airfreight network, carrier relationships and flexible routing options help customers secure capacity and respond quickly as market conditions change. 

If you have time-critical, high-value or peak-season shipments planned for Q4, talk to our airfreight team about protecting capacity and keeping cargo moving.