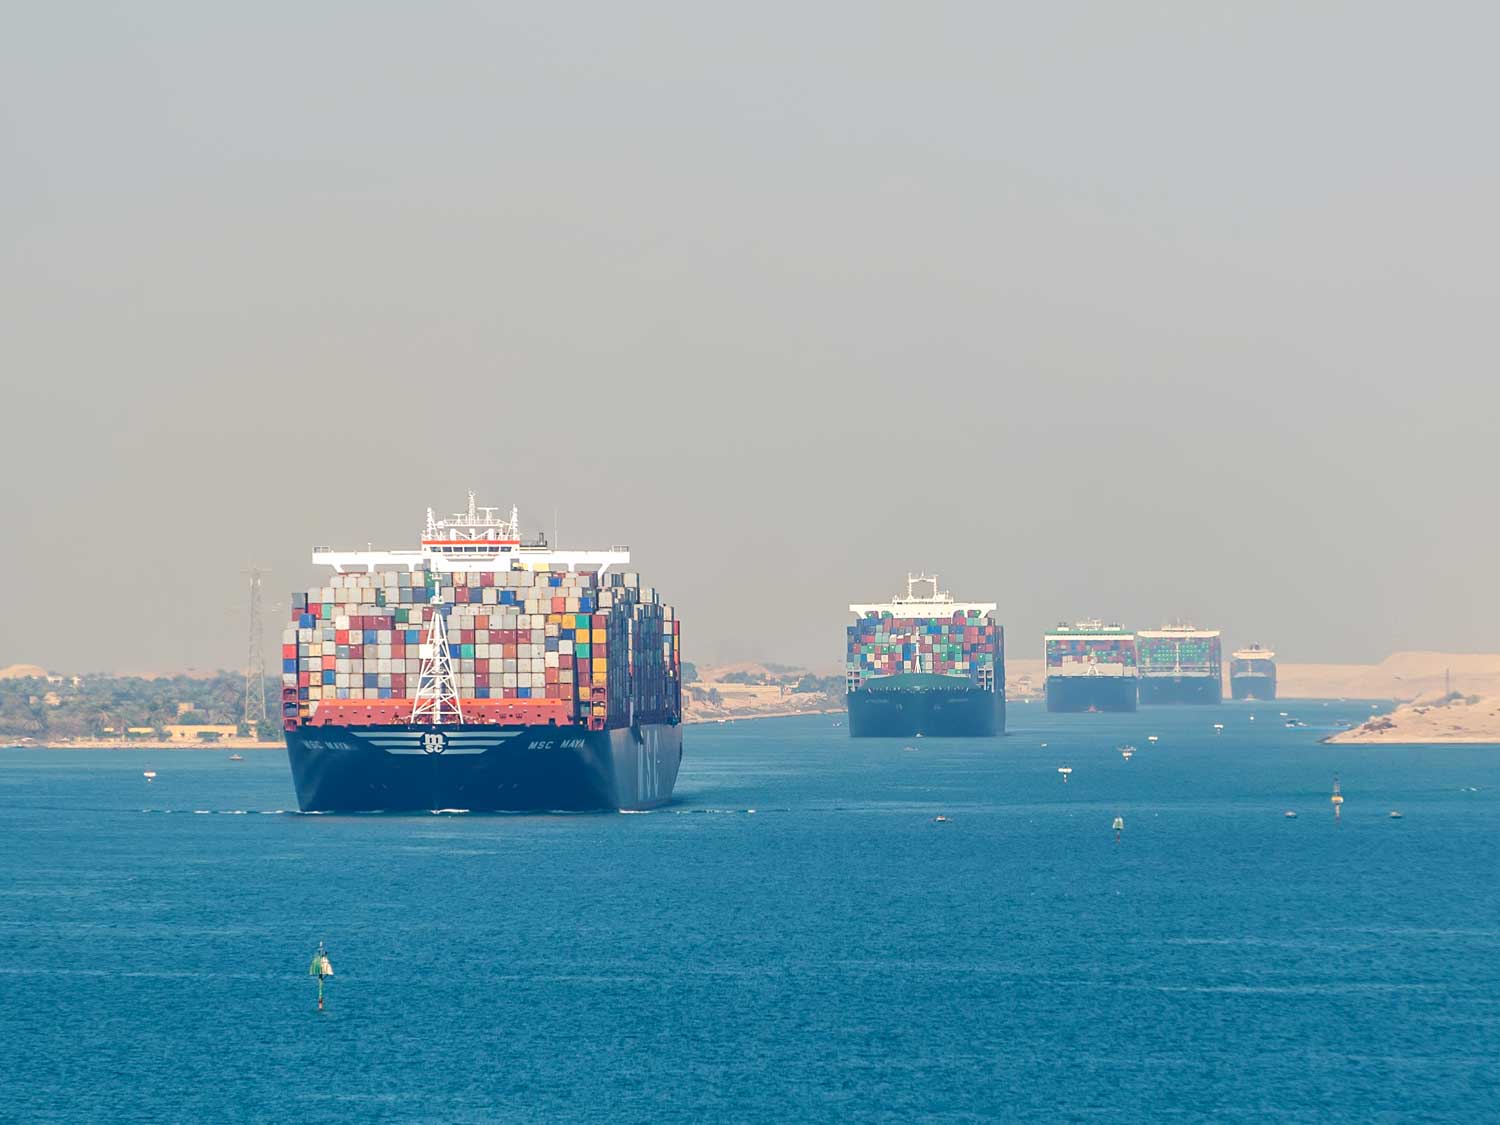
Suez convoy

Suez Canal return gathers pace

Nearly two-thirds of Far East–Europe container shipping capacity is now operating through the Red Sea and Suez Canal, marking a significant shift away from Cape of Good Hope diversions, although security concerns and changing service rotations mean the return remains uneven.

After almost three years of widespread diversions around southern Africa, container shipping is progressively returning to one of the world's most important trade corridors.

Major shipping lines have restored Suez transits across a growing number of Asia–Europe services, with the recovery now extending to selected routes connecting Asia and the US East Coast.

The transition could shorten delivery times, reduce fuel consumption and eventually release substantial vessel capacity. However, mixed routings, ongoing security assessments and potential congestion at European ports mean the benefits will not be immediate or consistent across every service.

Nearly two-thirds of Asia–Europe capacity returns

The scale of the recovery is becoming increasingly clear.

63%
Far East–Europe capacity using the Red Sea
70%
Far East–Mediterranean capacity
58%
Far East–North Europe capacity
24 of 46
Direct Far East–Europe services transiting the Red Sea

Analysis of the ten largest container shipping networks shows that approximately 5.5 million TEU of the 8.7 million TEU deployed between the Far East and Europe is now assigned to services using the Red Sea.

The Mediterranean trades are leading the recovery, with around 70% of capacity back on Suez routings, compared with 58% on Far East–North Europe services.

However, the return is not uniform.

Some services use the Suez Canal westbound towards Europe but continue to route eastbound voyages around the Cape of Good Hope.

This approach allows carriers to reintroduce shorter routings selectively while retaining flexibility if regional security conditions deteriorate.

Major carriers accelerate their return

The shift has gathered momentum since the summer, with several major shipping groups progressively restoring services.

MSC resumed Suez transits in August and now operates 11 loops through the waterway, representing approximately 2.2 million TEU of deployed capacity.

Maersk and Hapag-Lloyd have also expanded their use of the route, with nine alliance services representing around 1.76 million TEU.

CMA CGM maintained a presence through the Suez Canal during the disruption and has subsequently expanded its operations, while COSCO and OOCL have restored six services with combined deployed capacity of approximately 1.27 million TEU.

The Premier Alliance has also begun returning selected services, adding further momentum.

With some networks operating through Suez in both directions, others retaining Cape diversions, and several using different routes for outbound and return voyages, individual service patterns remain important when assessing transit times and reliability.

Weekly Suez traffic continues to strengthen

The recovery is also evident in actual canal traffic. Containership transits increased from 54 in week 41 to 55 in week 42, extending a period of improving volumes.

The latest figures indicate that more carriers are progressively restoring services rather than relying solely on occasional voyages.

However, the canal remains well below its historical potential, and the return is taking place against a backdrop of continuing security concerns around the Red Sea and Bab-el-Mandeb Strait.

For shipping lines, the commercial advantages of Suez are substantial. Shorter voyages can reduce fuel consumption, lower operating costs and potentially allow carriers to maintain weekly services with fewer vessels.

With bunker prices remaining elevated, these savings provide a strong incentive to restore shorter routes wherever security assessments permit.

Asia–US East Coast services begin returning

The recovery is no longer confined to Europe. MSC and Zim have resumed Suez transits in both directions on their shared Asia–US East Coast service, marking a further development in the restoration of global shipping networks.

The first northbound sailing departed Singapore on 18 October, with arrival in New York–New Jersey expected on 18 November.

Other services connecting India and the Middle East with the US East Coast have also resumed Suez routings, although some continue to use the Cape of Good Hope in the opposite direction.

For shippers, the potential transit-time benefits vary considerably. Asia–Europe services returning to Suez have achieved average transit-time improvements of approximately seven days.

However, North American services have experienced mixed results, with some achieving modest savings and others recording longer overall transit times despite using the shorter canal route.

Port rotations, transhipment arrangements and congestion at intermediate gateways can offset the theoretical advantages of a shorter voyage.

Full return could happen in early 2027

Industry expectations increasingly point towards a broader restoration of Suez services during the first quarter of 2027.

However, this remains a scenario rather than a confirmed timetable.

Maersk has discussed the possibility of further service returns, but has emphasised that no definitive schedule has been announced and that future changes will depend on security conditions, operational planning and consultation with partners and customers.

The pace of recovery will also depend on the ability of ports and inland transport networks to accommodate changing vessel arrival patterns.

Rotterdam and Antwerp-Bruges are already experiencing challenges associated with overlapping schedules and fluctuating volumes as services transition between Cape and Suez routings.

A faster return could release significant effective vessel capacity into the market, potentially increasing pressure on ocean freight rates.

At the same time, changes to vessel rotations and arrival patterns could create temporary congestion, schedule disruption and equipment imbalances.

Changing ocean networks offer supply-chain opportunities

The return to Suez could reshape ocean freight costs, transit times and capacity availability. Making the most of these changes requires accurate market intelligence and the flexibility to respond.

Our teams monitor carrier routing decisions, vessel schedules, port conditions and freight rates, identifying opportunities to improve transit times, manage costs and maintain reliable delivery performance.

Whether you're reviewing Asia–Europe or trans-Pacific shipping arrangements, evaluating India–US connections or preparing for further network changes in 2027, Metro can help you understand the implications and identify practical alternatives.

Contact Metro to review your ocean freight strategy and take advantage of emerging routing, capacity and cost opportunities as the Suez Canal recovery gathers pace.
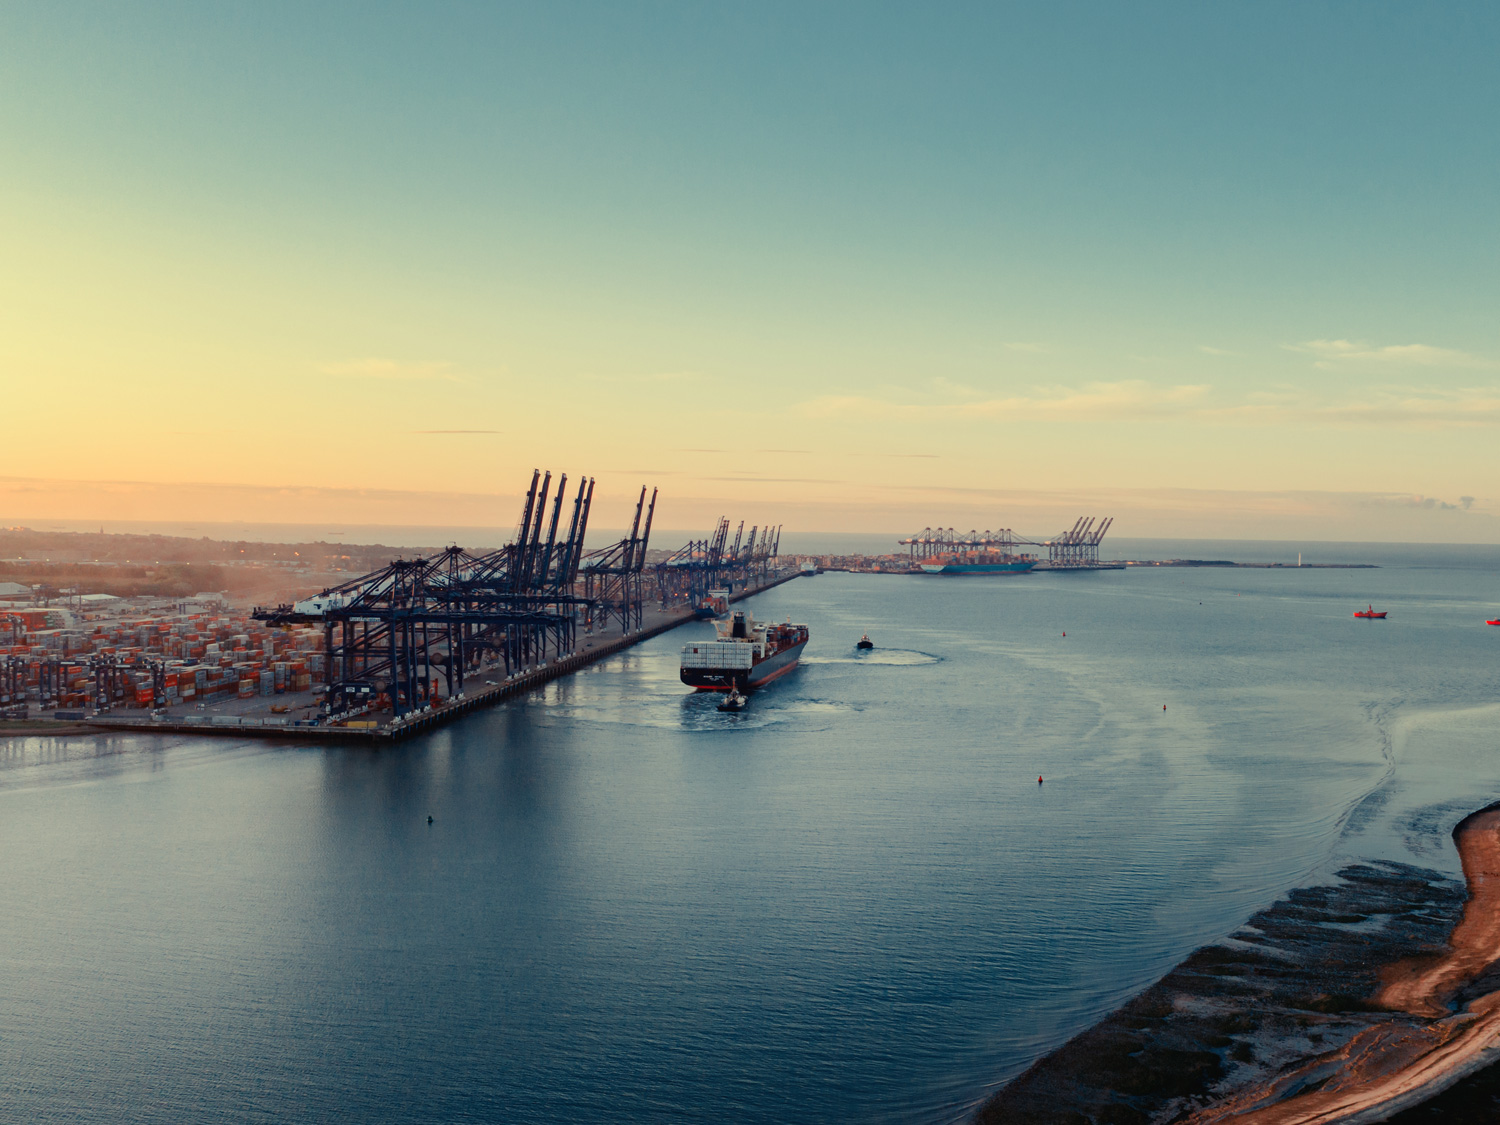
FXT at dawn

Global container trade breaks records as demand outpaces disruption

Global container volumes have reached another record high, with expanding trade flows across Asia, the Americas and Africa demonstrating the resilience of international commerce despite geopolitical uncertainty, rising transport costs and persistent shipping disruption.

Global container trade reached 17.46 million TEU in August 2026, surpassing July's previous record and marking the second consecutive month of unprecedented volumes.

The latest figures reveal an international trading environment that continues to expand despite considerable operational and economic challenges. Container volumes increased 3.7% compared with August 2025, while cumulative growth for the first eight months of 2026 reached 4.7%.

Looking further back, August volumes were 7.2% higher than in 2024 and 12.9% above 2023, highlighting the sustained expansion of containerised trade.

Asia drives growth as trade patterns evolve

The Far East remains the principal engine of global container trade, with exports increasing 8% year to date, equivalent to approximately 6.3 million additional TEU.

Every destination region recorded growth in imports from the Far East, with Sub-Saharan Africa and South and Central America delivering particularly strong percentage increases.

Sub-Saharan Africa also recorded the fastest overall import growth, up 13%, highlighting the growing importance of emerging consumer and industrial markets.

North American imports have returned to positive territory, increasing 2% year to date following a weaker start to 2026. Transpacific volumes are now 5% higher, supported by renewed demand for Far Eastern goods.

European exports have also stabilised after contracting earlier in the year, suggesting a gradual improvement in trading conditions.

However, growth remains uneven. Imports into the Indian Sub-Continent and Middle East declined 5%, while exports fell 10%, reflecting the significant disruption affecting regional trade flows.

These differences reinforce the importance of examining individual markets rather than relying on global averages when planning international supply chains.

Record volumes are adding to shipping costs

The strength of container demand has coincided with substantial freight pricing pressure.

The global container freight price index reached 117 points in August, its highest level since July 2024. The index has increased approximately 50% since January and stands 44% above August 2025.

The increase reflects more than cargo demand alone, with geopolitical disruption, longer vessel routings, congestion and constraints affecting major shipping corridors reducing the amount of vessel capacity effectively available to the market.

Ships diverted around the Cape of Good Hope spend longer completing voyages, while delays and congestion absorb capacity that would otherwise support additional sailings.

Consequently, even substantial investment in new vessels does not necessarily translate into improved availability or lower costs.

The distinction between the size of the global container fleet and the capacity that can actually be deployed remains fundamental to understanding freight market conditions.

Growth is continuing, but the outlook is changing

Despite August's record, there are early indications that the pace of expansion may be moderating.

Volumes increased just 0.5% compared with July, suggesting that the exceptional momentum seen during the middle of 2026 could be approaching a turning point.

Meanwhile, the global containership order-book represents more than 46% of the existing fleet, with substantial new capacity scheduled for delivery during 2027 and 2028.

This creates the prospect of a different market balance. If trade growth moderates while new vessels enter service, the additional capacity could place downward pressure on freight rates, particularly as more shipping services resume shorter routes through Suez.

However, the transition is unlikely to be uniform. Carrier capacity management, port congestion, regional demand and geopolitical developments will continue to influence individual trades, potentially creating significant differences between headline market trends and the conditions experienced by shippers.

For businesses planning ahead, the challenge is to distinguish between temporary disruption, underlying demand growth and longer-term changes in available capacity.

Connecting growing markets with global capability

As international container trade reaches new highs, businesses need more than access to shipping space. They need the expertise, relationships and visibility to take advantage of changing trade patterns while controlling costs and protecting delivery performance.

Metro combines established global carrier relationships, competitive ocean freight procurement and extensive international logistics capabilities with local expertise across major sourcing and destination markets.

Our expanding presence in India and the US strengthens our ability to support changing trade flows, while our ocean freight, consolidation, customs and inland transport services provide coordinated solutions from origin to final delivery.

Whether you're expanding into new markets, reviewing your freight strategy or preparing for the next shift in container shipping capacity, Metro can help turn changing global trade conditions into a competitive advantage.

Contact Metro to review your international shipping requirements and identify the routes, services and opportunities that best support your business.

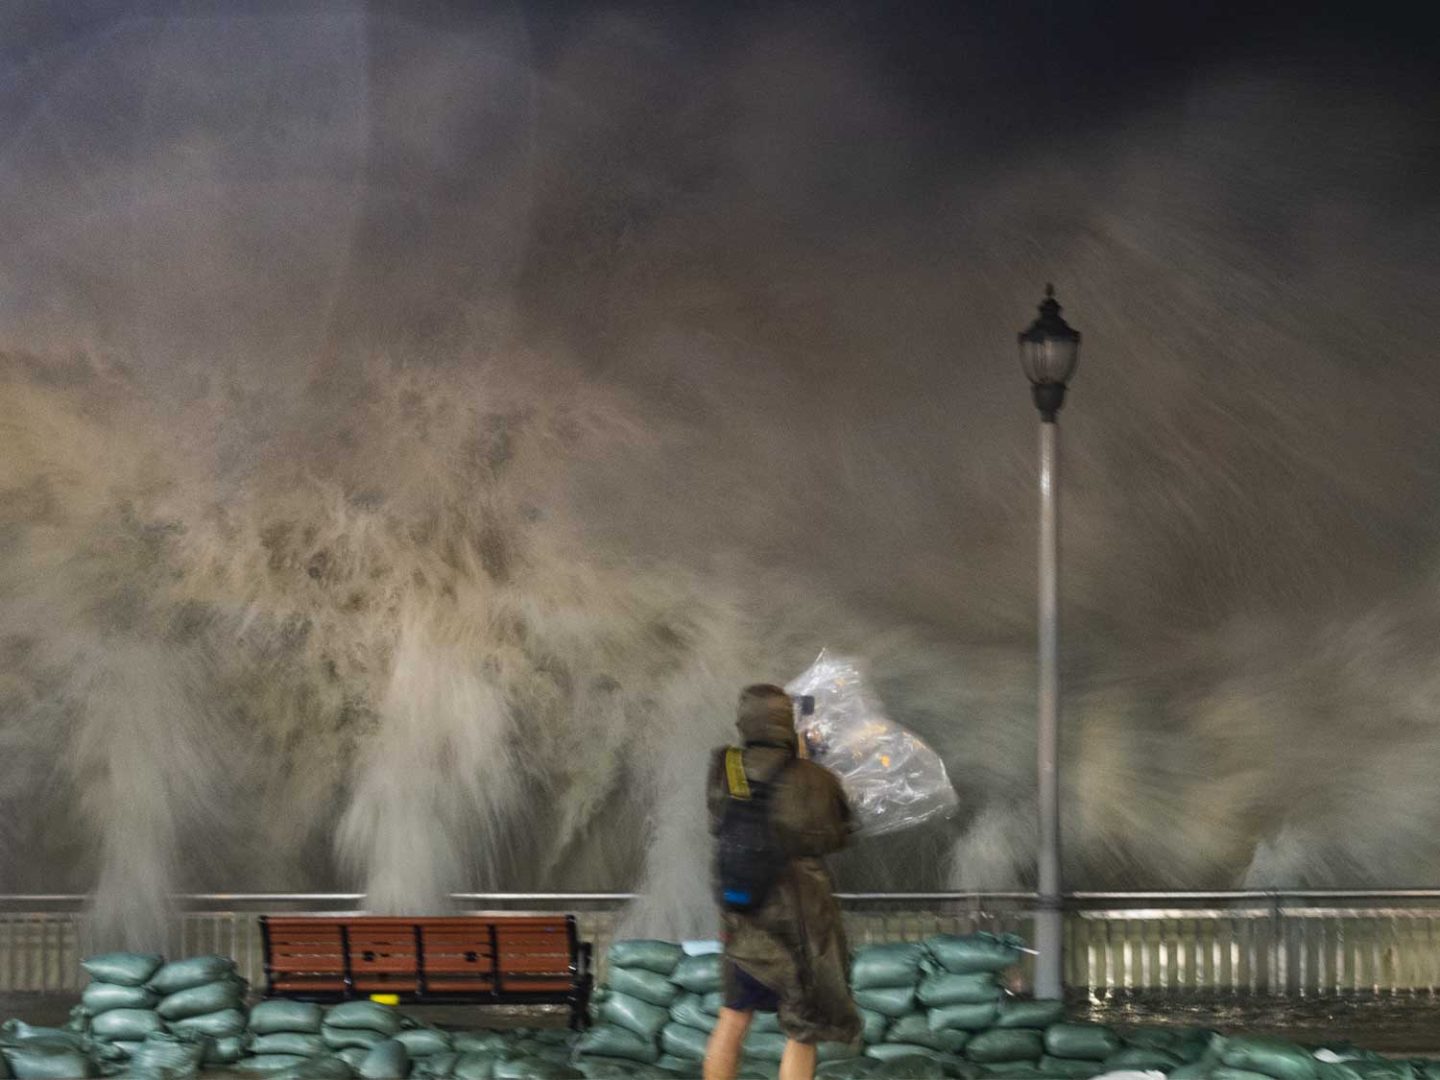
Typhoon HKG 1440x1080 1

Supply chain resilience moves from response to strategy

Supply-chain leaders meeting in London have highlighted a significant shift in priorities, as resilience, visibility and flexibility move from operational concerns to strategic business requirements.

Recent years have tested international supply chains through pandemic disruption, port congestion, geopolitical conflict, Red Sea diversions, changing trade policies and extreme weather.

But one of the clearest messages from Supply Chain LIVE: The London Summit 2026 was that businesses are moving beyond reacting to individual disruptions and increasingly designing supply chains that expect change.

Some 2,500 attendees gathered at London's QEII Centre, with discussions spanning resilience, artificial intelligence, sustainability, global trade and supply-chain orchestration.

Contributions from senior executives at Siemens, Tate & Lyle, Babcock International, Kongsberg Maritime and other organisations highlighted how supply-chain management is evolving from an operational function into a strategic business capability.

Supply chain has become a boardroom issue

Supply-chain management was once primarily judged through operational measures: cost, inventory, lead time and service. Those measures remain important, but supply-chain decisions now have wider commercial implications.

Availability can determine whether production continues. Sourcing decisions influence exposure to geopolitical and tariff risks. Transport costs affect margins, while sustainability performance increasingly depends on information from suppliers and logistics networks.

Speaking about supply chain as a strategic growth engine, Tate & Lyle's Chief Supply Chain Officer, Kim Faulkner, emphasised the importance of looking beyond operational metrics to understand the wider business outcomes they enable.

Similarly, discussions on global trade and logistics highlighted how business continuity and strategic decision-making have brought supply chain into the boardroom.

That reflects what Metro is seeing across international freight.

Businesses are no longer asking only how cheaply or quickly goods can move. They are considering what happens when a preferred route, carrier, supplier or transport mode becomes unavailable.

Resilience increasingly means having options

Recent disruption has demonstrated how quickly established transport patterns can change.

Red Sea diversions have absorbed significant container capacity, while Asian weather disruption and port congestion have affected vessel schedules and reduced effective capacity across shipping networks.

The result is an important distinction between capacity that theoretically exists and capacity actually available when and where shippers need it.

During the summit's discussion on supply-chain risk and resilience, Babcock International's Ewan Sime observed that many risks are not necessarily new, but the ways they emerge and affect businesses are changing.

This reinforces the need to prepare for different outcomes rather than attempt to predict every disruption.

Building resilience does not necessarily mean maintaining expensive inventory buffers or accepting permanently higher logistics costs.

It means creating alternatives before they become necessary.

Different carriers and gateways can provide options when services are disrupted. Consolidation can offer alternative routes to market, while airfreight can protect urgent shipments when ocean schedules become unreliable. Road, rail and multimodal solutions provide further flexibility.

More efficient routing, better utilisation and consolidation can also reduce unnecessary movements, supporting sustainability objectives while improving operational performance.

The challenge is identifying and developing these options before disruption occurs, rather than searching for solutions when capacity is already constrained.

Visibility has to lead to action

Technology featured prominently throughout the London summit, particularly artificial intelligence and supply-chain orchestration.

AI can process information faster, digital platforms improve visibility, and automation removes repetitive processes. But knowing where cargo is located is only the beginning.

The real value comes from combining information with the ability to act on it.

That distinction was reflected in Kongsberg Maritime's presentation, From Visibility to Resilience, where senior executive Rob Anthony emphasised the growing importance of adaptability and flexibility in responding to supply-chain risks.

A delayed vessel notification has limited value without an alternative. Identifying congestion matters more when another gateway can be considered. Anticipating tightening capacity becomes useful when space can be secured before conditions deteriorate.

International supply chains remain complex networks of carriers, ports, suppliers and transport providers operating across different countries and regulatory environments.

The summit also reinforced the continuing importance of people. Siemens' Alexander Tschentscher highlighted the essential role of people in delivering effective supply-chain operations, even as technology becomes more sophisticated.

When disruption occurs, established relationships, experience and local knowledge remain essential.

Metro's technology provides customers with greater visibility and control across international movements, while its operational teams combine market intelligence, carrier relationships and local expertise to identify changing conditions and potential alternatives.

Technology can highlight a problem. Experience and operational flexibility help resolve it.

Globalisation is changing rather than disappearing

Resilience is also influencing where businesses source and manufacture.

Companies are reassessing dependence on individual countries, suppliers and trade lanes, supporting increased interest in India, Turkey, North Africa and manufacturing closer to end markets.

But diversification does not necessarily mean de-globalisation. New manufacturing locations create new trade flows, often introducing additional logistics requirements and infrastructure challenges.

India provides a good example. Its expanding manufacturing and export economy offers significant opportunities, but rapid growth is also putting pressure on vessel capacity, container equipment and inland infrastructure.

Metro's expanding presence in India provides greater local visibility and connectivity as customers consider the country both as an alternative sourcing location and a growing consumer market.

The same principle applies elsewhere. Supply chains are becoming more geographically diverse, increasing the importance of local knowledge, reliable transport connections and coordination across international networks.

From reacting to disruption to designing for it

Perhaps the most significant change in supply-chain thinking is the recognition that disruption is no longer exceptional.

The causes may change – weather, geopolitics, congestion, tariffs or labour shortages – but volatility has become a recurring feature of international trade.

Businesses cannot predict every disruption, but they can improve their ability to respond through better information, earlier intervention and greater operational flexibility.

This is where Metro's long-standing investments in technology make a practical difference.

Through its digital MVT platforms, Metro gives customers greater visibility of international shipments, products flows, supply-chain performance and the intelligence needed to support more informed decisions.

Combined with Metro's global network, carrier relationships and experienced operational teams, that visibility helps customers identify emerging issues, assess alternatives and take action before disruption becomes a more significant problem.

For shippers, resilience is increasingly less about predicting the next problem and more about having the visibility, intelligence and flexibility to respond when it arrives.

Metro brings these capabilities together to help customers build more responsive, efficient and resilient international supply chains.

Lloyds Market Matters

Metro CEO joins Lloyds Bank to examine the changing global trade outlook

Metro CEO Grant Liddell joined Lloyds Bank’s Markets Matter briefing to examine how geopolitical disruption, changing sourcing strategies and rising transport costs are reshaping global supply chains and why underlying trade remains surprisingly resilient.

The Lloyds Bank’s Markets Matter series brings together its economists and market specialists with business leaders to give corporate and commercial clients practical insight into the economic, financial and operational issues affecting their businesses.

For its latest briefing, Navigating Markets Beyond Monetary Policy, Grant joined Lloyds Bank specialists to bring a logistics perspective to a discussion spanning interest rates, inflation, energy prices, government finances and the wider risks facing UK businesses.

With freight costs among the channels through which geopolitical disruption and higher energy prices can feed into inflation, the discussion turned to what Metro is seeing across international supply chains and how businesses are responding.

Global trade is proving resilient

Global logistics provides an unusually immediate barometer of international trade, and Grant highlighted the contrast between the economic headlines and what is actually moving through supply chains.

Global container volumes reached a record level during July, while containerised trade continued to grow year on year. Intra-Asia and Asian export trades have been particularly strong, despite tariffs, geopolitical tensions and changing sourcing patterns. 

The picture is not uniform. European demand remains relatively subdued compared with the US, Far East and some emerging markets, while India is experiencing particularly strong growth.

That demand has consequences. Freight operates as a highly responsive market, with rates capable of rising or falling rapidly as available capacity moves out of balance with cargo demand. Grant highlighted dramatic increases on some Indian ocean and airfreight trades this year, while transpacific ocean rates have returned towards levels last experienced during the pandemic. 

Those increases do not stop with the freight invoice. Components and raw materials frequently cross borders several times before a finished product reaches its customer. Higher transport costs can therefore enter the production process at multiple stages, creating an indirect inflationary effect as well as increasing the final cost of distribution. 

From just in time to ‘just given time’

One of Grant’s most interesting observations concerned the way businesses are responding to disruption.

The highly optimised just-in-time model used across many manufacturing and industrial sectors has become much harder to maintain as Red Sea diversions, geopolitical conflict, closed airspace and port congestion extend and destabilise transit times.

Grant described the reality as increasingly becoming “just given time” with businesses adapting their inventory and production strategies to supply chains where predictable lead times can no longer always be assumed. 

That change is also accelerating interest in alternative sourcing locations. India is attracting manufacturing in sectors including technology and electronics, while Metro customers are increasingly considering production in the UK and Europe. North Africa is becoming more prominent and Turkey has attracted manufacturing across garments, automotive and engineering.

Some businesses had already begun reducing their dependence on China before the pandemic. Subsequent disruption has pushed resilience and diversification much higher up the agenda.

Yet this does not necessarily mean less international trade. Goods may travel shorter distances or move by truck rather than deep-sea container or airfreight, while rapidly expanding intra-Asian trade demonstrates how changing manufacturing footprints can create new freight flows rather than eliminate them. 

Reliability becomes the critical supply-chain risk

Asked what businesses should be considering as they plan for 2027, Grant put reliability high on the list.

Strong demand is combining with congested ports, delayed vessels, weather disruption and geopolitical uncertainty. The resulting challenge is not simply securing a competitive freight rate, but ensuring components reach production lines and finished products reach markets when required. 

That reinforces a theme running throughout the Lloyds discussion.

Higher freight and energy costs matter, but their wider economic impact depends partly on how businesses respond: whether costs are absorbed, reflected in pricing, influence wage decisions or become embedded in future contracts.

For supply-chain managers, the equivalent challenge is building enough flexibility into sourcing, inventory and transport strategies to withstand disruption without creating excessive cost.

Suez could change the equation again

There are also reasons why the freight outlook could change during 2027.

Grant highlighted the increasing use of the Red Sea and Suez route by carriers serving Asia, with several lines already using the route regularly.

A wider return would release effective vessel capacity because ships would no longer require the additional 15+ days associated with Cape of Good Hope diversions. That could improve supply and place downward pressure on freight rates. 

But the outlook remains complicated by energy prices, aviation fuel costs and continuing geopolitical risk.

Near-shoring can provide another layer of protection, but changing a manufacturing footprint is neither quick nor straightforward. Establishing new suppliers and supply chains can take months or years.

The result, as Grant characterised it, is a mixed picture for 2027, and while significant risks remain businesses are actively changing how and where they source, manufacture and move products to manage them. 

Turning global risk into practical supply-chain decisions

Perhaps the clearest message from the discussion was that geopolitical and economic uncertainty has not stopped global trade. Instead, it is changing its routes, costs and priorities.

With businesses already planning for 2027, the discussion provides useful context for understanding how economic and geopolitical risks could affect costs, sourcing and supply-chain decisions in the months ahead.

Click HERE to catch up with the full Lloyds Banking Group Markets Matter recording.