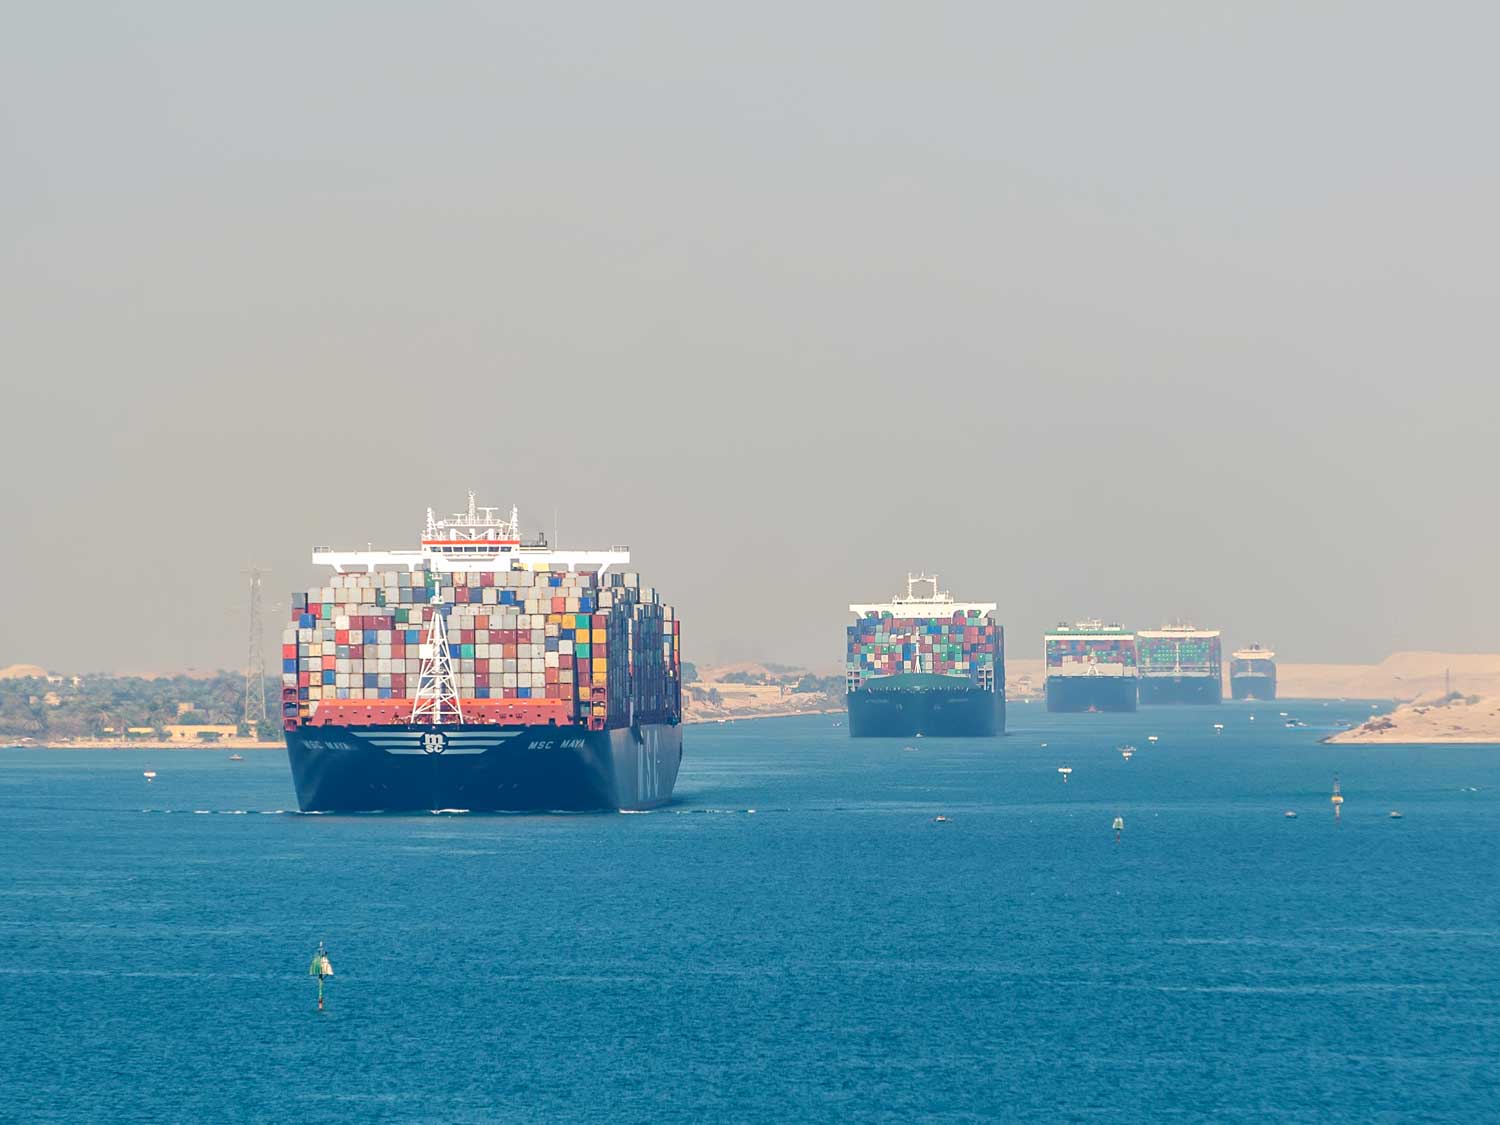
Suez convoy

Suez Canal return gathers pace

Nearly two-thirds of Far East–Europe container shipping capacity is now operating through the Red Sea and Suez Canal, marking a significant shift away from Cape of Good Hope diversions, although security concerns and changing service rotations mean the return remains uneven.

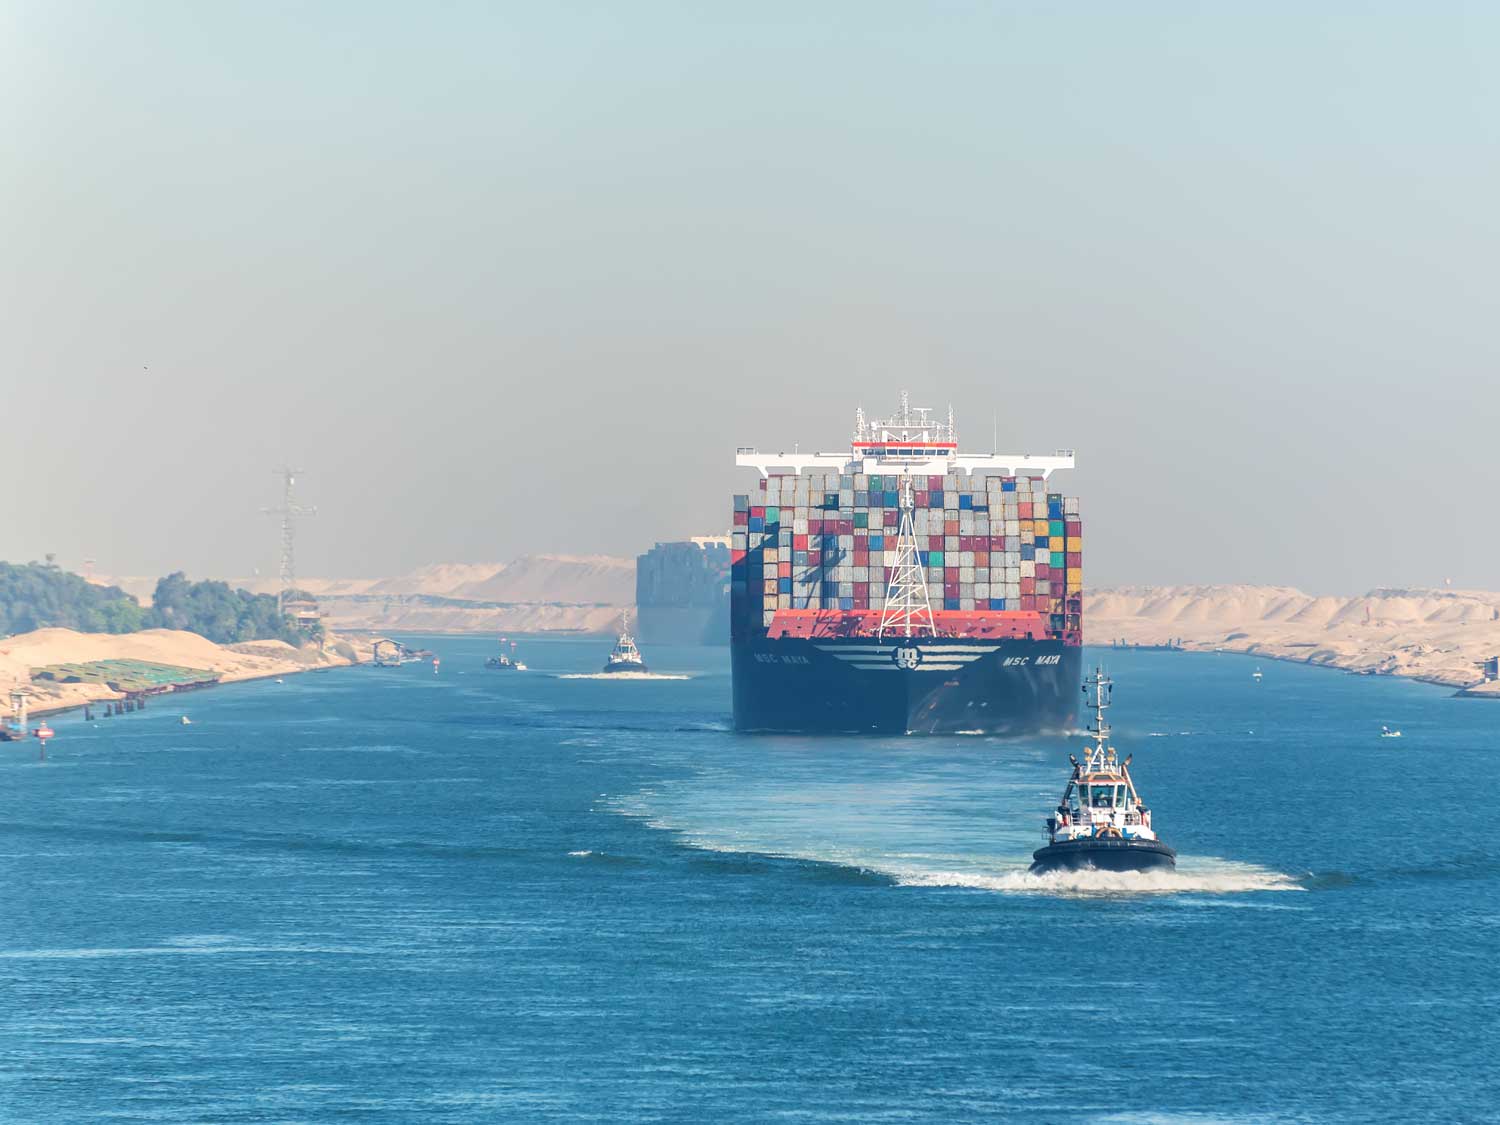
After almost three years of widespread diversions around southern Africa, container shipping is progressively returning to one of the world's most important trade corridors.

Major shipping lines have restored Suez transits across a growing number of Asia–Europe services, with the recovery now extending to selected routes connecting Asia and the US East Coast.

The transition could shorten delivery times, reduce fuel consumption and eventually release substantial vessel capacity. However, mixed routings, ongoing security assessments and potential congestion at European ports mean the benefits will not be immediate or consistent across every service.

Nearly two-thirds of Asia–Europe capacity returns

The scale of the recovery is becoming increasingly clear.

63%
Far East–Europe capacity using the Red Sea
70%
Far East–Mediterranean capacity
58%
Far East–North Europe capacity
24 of 46
Direct Far East–Europe services transiting the Red Sea

Analysis of the ten largest container shipping networks shows that approximately 5.5 million TEU of the 8.7 million TEU deployed between the Far East and Europe is now assigned to services using the Red Sea.

The Mediterranean trades are leading the recovery, with around 70% of capacity back on Suez routings, compared with 58% on Far East–North Europe services.

However, the return is not uniform.

Some services use the Suez Canal westbound towards Europe but continue to route eastbound voyages around the Cape of Good Hope.

This approach allows carriers to reintroduce shorter routings selectively while retaining flexibility if regional security conditions deteriorate.

Major carriers accelerate their return

The shift has gathered momentum since the summer, with several major shipping groups progressively restoring services.

MSC resumed Suez transits in August and now operates 11 loops through the waterway, representing approximately 2.2 million TEU of deployed capacity.

Maersk and Hapag-Lloyd have also expanded their use of the route, with nine alliance services representing around 1.76 million TEU.

CMA CGM maintained a presence through the Suez Canal during the disruption and has subsequently expanded its operations, while COSCO and OOCL have restored six services with combined deployed capacity of approximately 1.27 million TEU.

The Premier Alliance has also begun returning selected services, adding further momentum.

With some networks operating through Suez in both directions, others retaining Cape diversions, and several using different routes for outbound and return voyages, individual service patterns remain important when assessing transit times and reliability.

Weekly Suez traffic continues to strengthen

The recovery is also evident in actual canal traffic. Containership transits increased from 54 in week 41 to 55 in week 42, extending a period of improving volumes.

The latest figures indicate that more carriers are progressively restoring services rather than relying solely on occasional voyages.

However, the canal remains well below its historical potential, and the return is taking place against a backdrop of continuing security concerns around the Red Sea and Bab-el-Mandeb Strait.

For shipping lines, the commercial advantages of Suez are substantial. Shorter voyages can reduce fuel consumption, lower operating costs and potentially allow carriers to maintain weekly services with fewer vessels.

With bunker prices remaining elevated, these savings provide a strong incentive to restore shorter routes wherever security assessments permit.

Asia–US East Coast services begin returning

The recovery is no longer confined to Europe. MSC and Zim have resumed Suez transits in both directions on their shared Asia–US East Coast service, marking a further development in the restoration of global shipping networks.

The first northbound sailing departed Singapore on 18 October, with arrival in New York–New Jersey expected on 18 November.

Other services connecting India and the Middle East with the US East Coast have also resumed Suez routings, although some continue to use the Cape of Good Hope in the opposite direction.

For shippers, the potential transit-time benefits vary considerably. Asia–Europe services returning to Suez have achieved average transit-time improvements of approximately seven days.

However, North American services have experienced mixed results, with some achieving modest savings and others recording longer overall transit times despite using the shorter canal route.

Port rotations, transhipment arrangements and congestion at intermediate gateways can offset the theoretical advantages of a shorter voyage.

Full return could happen in early 2027

Industry expectations increasingly point towards a broader restoration of Suez services during the first quarter of 2027.

However, this remains a scenario rather than a confirmed timetable.

Maersk has discussed the possibility of further service returns, but has emphasised that no definitive schedule has been announced and that future changes will depend on security conditions, operational planning and consultation with partners and customers.

The pace of recovery will also depend on the ability of ports and inland transport networks to accommodate changing vessel arrival patterns.

Rotterdam and Antwerp-Bruges are already experiencing challenges associated with overlapping schedules and fluctuating volumes as services transition between Cape and Suez routings.

A faster return could release significant effective vessel capacity into the market, potentially increasing pressure on ocean freight rates.

At the same time, changes to vessel rotations and arrival patterns could create temporary congestion, schedule disruption and equipment imbalances.

Changing ocean networks offer supply-chain opportunities

The return to Suez could reshape ocean freight costs, transit times and capacity availability. Making the most of these changes requires accurate market intelligence and the flexibility to respond.

Our teams monitor carrier routing decisions, vessel schedules, port conditions and freight rates, identifying opportunities to improve transit times, manage costs and maintain reliable delivery performance.

Whether you're reviewing Asia–Europe or trans-Pacific shipping arrangements, evaluating India–US connections or preparing for further network changes in 2027, Metro can help you understand the implications and identify practical alternatives.

Contact Metro to review your ocean freight strategy and take advantage of emerging routing, capacity and cost opportunities as the Suez Canal recovery gathers pace.
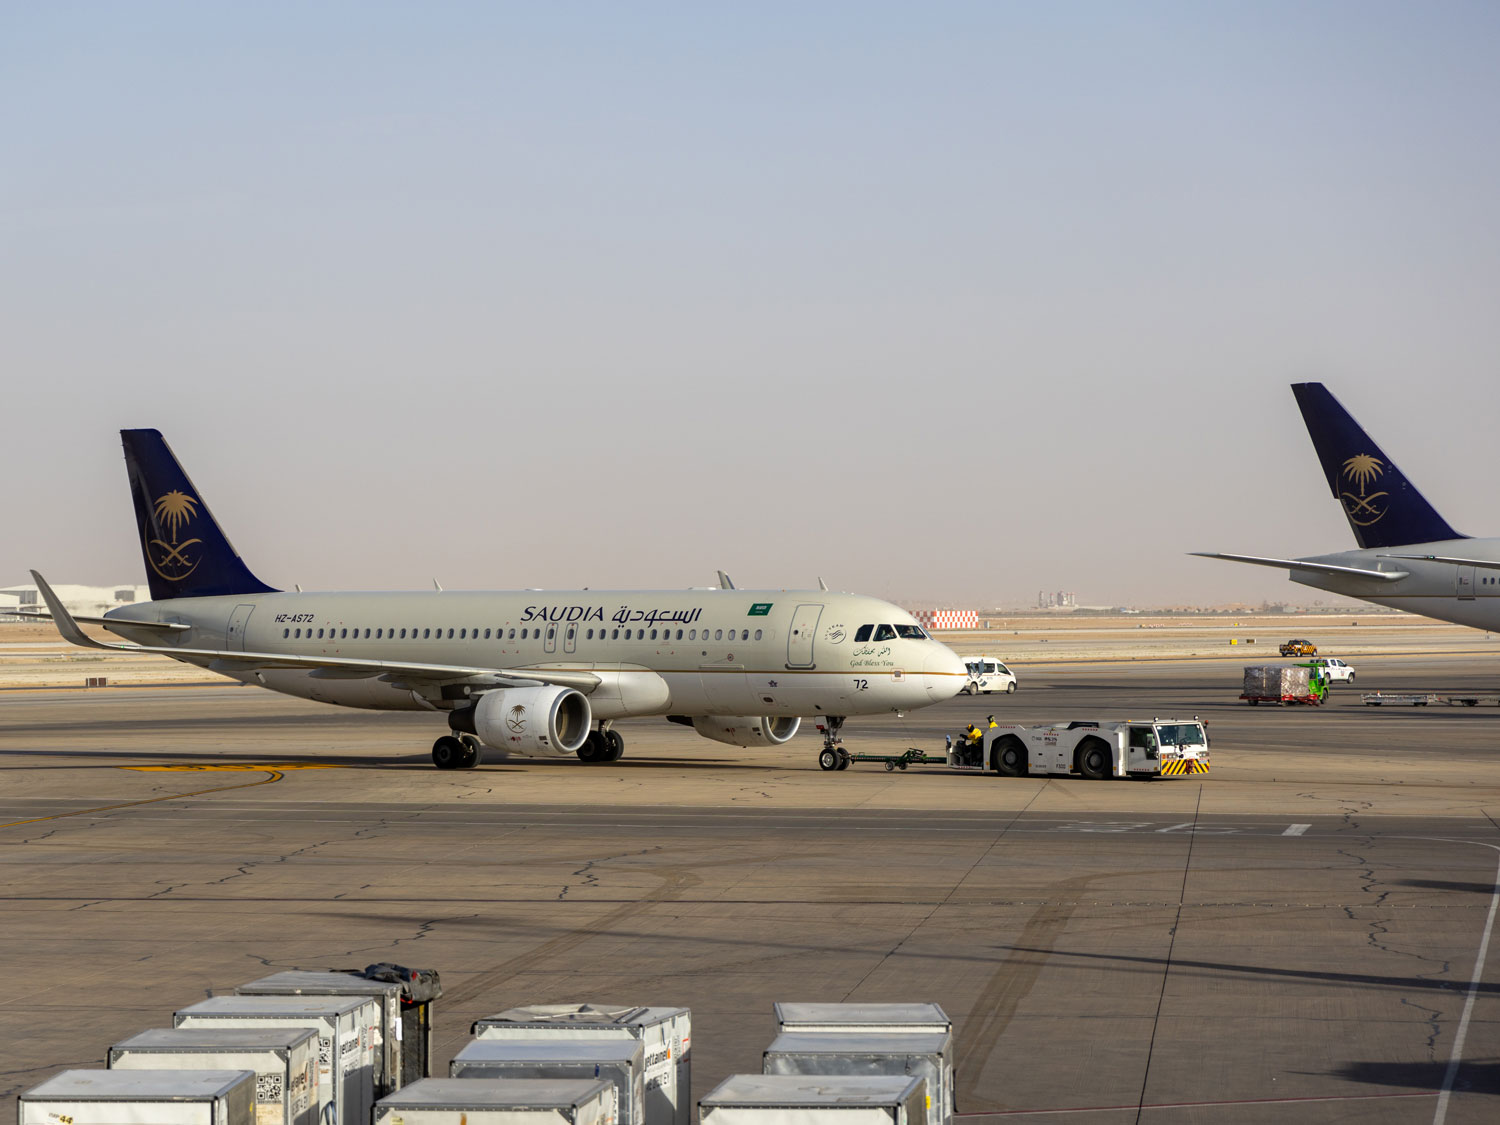
Saudia air

Airfreight demand and Middle East disruption tighten peak-season

Airfreight markets are entering the fourth-quarter peak season with demand strengthening, capacity tightening on key routes and renewed disruption in the Middle East adding pressure to airline networks and transport costs.

Global air cargo demand recovered strongly in September, with worldwide tonnages increasing 9% year on year, according to WorldACD. Growth was particularly strong across Asia Pacific and North America, where volumes increased 10%.

The recovery reflects continued demand for high-value and time-sensitive shipments, particularly equipment supporting artificial intelligence, data centres and semiconductor manufacturing.

However, the market is becoming increasingly uneven, with trans-Pacific demand accelerating, China–Europe volumes recovering only gradually and Middle East disruption affecting available capacity.

Peak-season demand strengthens despite temporary rate dip

Airfreight rates edged higher throughout September as shippers prepared for the traditional fourth-quarter peak.

Worldwide average rates increased 1% month on month and stood 25% above September 2025 levels, reflecting stronger demand, elevated fuel costs and continuing capacity constraints.

The Baltic Air Freight Index subsequently rose 5% in the week to 5 October before easing 2.1% during China's Golden Week holiday, when factory closures temporarily reduced export volumes.

Despite that decline, the index remained 24.3% higher year on year as the market entered its busiest quarter.

Capacity commitments are already influencing the outlook. Major e-commerce operators and businesses preparing product launches have secured peak-season space, while some large AI infrastructure customers have yet to finalise their requirements.

Additional bookings from these shippers could tighten available capacity and push rates higher during the coming weeks.

AI infrastructure drives trans-Pacific growth

The expansion of AI infrastructure has become a significant driver of air cargo demand, particularly between Asia and North America.

Large volumes of servers, semiconductors, data-centre equipment and energy storage systems are moving from manufacturing centres in Taiwan, South Korea, Vietnam and China to support US investment in digital infrastructure.

Trans-Pacific airfreight volumes increased 10% year on year in September, with outbound Asian load factors approaching 90%, despite airlines increasing capacity by approximately 10%.

The strength of demand is also influencing airline deployment decisions, with freighters being transferred from other routes to serve the trans-Pacific market.

WorldACD figures reinforce the trend, showing China–US air cargo tonnages increasing 17% year on year in September, while average spot rates rose approximately 30%.

Ocean freight disruption could add further pressure. Schedule reliability from Asia to the US West Coast reportedly fell from 56% in May to just 26% in September, increasing the potential for urgent shipments to transfer to airfreight.

Saudi attacks create further capacity uncertainty

Renewed attacks on Saudi Arabian airports have introduced another source of disruption as the peak season gathers pace.

Following strikes on Riyadh's King Khalid International Airport and other Saudi facilities, airlines suspended services and authorities imposed operational restrictions.

Initial data showed Riyadh's international outbound air cargo capacity falling 34% over 24 hours, with freighter capacity particularly affected.

Further attacks prompted an extended suspension of operations at Riyadh on 12 October, while Dammam International Airport also experienced disruption.

The immediate consequences extend beyond Saudi Arabia. Airlines operating between Asia and Europe have already been adjusting their networks following wider Middle East disruption, including the loss of established intermediate stops.

Alternative routings can increase flying times, introduce payload restrictions and reduce the effective capacity available to shippers.

With peak-season demand building, prolonged restrictions could intensify competition for available space, particularly on routes connecting Asia, the Middle East and Europe.

China–Europe recovery remains uneven

While trans-Pacific demand continues to strengthen, the China–Europe market presents a different picture.

Combined air cargo volumes from mainland China and Hong Kong to Europe fell 10% year on year in September, although this represented an improvement on declines of 14% in July and 15% in August.

The downturn reflects changes to EU treatment of low-value e-commerce imports, which have affected shipments from Hong Kong and southern China.

Hong Kong–Europe tonnages remained 24% below September 2025 levels, while mainland China recorded a more modest 2% decline.

Rates have reflected this divergence, with China–Europe average prices increasing approximately 9% year on year in September, compared with a 30% increase in China–US spot rates.

The figures highlight how demand, regulation and available capacity are creating increasingly different conditions across major airfreight corridors.

Planning ahead as capacity tightens

The fourth-quarter outlook points towards sustained demand, particularly on trans-Pacific routes, with further potential for rate increases as remaining peak-season capacity is committed.

Saudi Arabian disruption adds uncertainty to an already constrained market, while higher fuel costs and shifting airline networks could affect availability and pricing across other trade lanes.

For shippers, early planning, accurate forecasts and flexibility over routing and departure dates will be increasingly important.

Metro's global airfreight network, airline relationships and experienced operational teams help customers secure capacity, assess alternative routings and respond quickly when market conditions change.

Whether managing regular shipments, urgent requirements or time-critical cargo, Metro combines international buying power with local expertise and shipment visibility to keep supply chains moving.

Contact Metro's airfreight team to review your peak-season requirements, protect critical shipments and identify the most effective options before capacity becomes constrained.

The Suez strikes back

Suez returns as Middle East shipping risks intensify

Container lines are restoring services through the Red Sea and Suez Canal, promising shorter Asia–Europe transits and more effective capacity. But the security picture around the Middle East’s critical shipping chokepoints is becoming more complicated, not less.

More Asia–Europe services are returning to Suez after almost three years of widespread diversions around the Cape of Good Hope. Yet a successful Houthi land offensive has expanded the group’s control along Yemen’s Red Sea coastline and the Bab el-Mandeb Strait.

At the same time, the Strait of Hormuz remains effectively closed to regular container services, conflict continues across the region and alternative Gulf supply chains are operating at significantly higher cost.

For shippers, this is not a straightforward return to normal. It is a more fragmented Middle East shipping environment in which routes can reopen, tighten or change at short notice.

Suez is reopening but the risk has not gone away

Container lines have steadily increased their use of the Red Sea during 2026. Almost a quarter of deep-sea capacity originally diverted around southern Africa has returned to Suez, with around 213,000 TEU of weekly capacity now moving through the waterway.

The shift is particularly advanced between Asia and the Mediterranean. More than a third of September headhaul capacity on this trade is expected to use the Red Sea, compared with around 6% between Asia and North Europe.

That transition is accelerating. Maersk and Hapag-Lloyd are moving another four Gemini Cooperation services from the Cape route to Suez during September, while other major carriers have also restored selected services.

The attraction is clear. Suez cuts substantial distance from Asia–Europe voyages, shortening transit times and allowing carriers to use vessels more efficiently. A widespread return could ultimately release the equivalent of 8% of global containership capacity currently absorbed by longer Cape routings.

That additional effective capacity is already contributing to softer Asia–Europe pricing, particularly into the Mediterranean.

However, the strategic picture at the southern entrance to the Red Sea has changed.

Recent Houthi advances have extended the group’s territorial control along Yemen’s Red Sea coastline and include Mayyun Island, which sits in the Bab el-Mandeb Strait. This gives the Houthis an even stronger position around the gateway connecting the Gulf of Aden with the Red Sea.

For now, the group has indicated that international traffic can continue unimpeded, with its restrictions focused on Saudi shipping. Container vessels have also largely avoided direct attacks for more than a year, allowing carriers to conclude that selected Red Sea transits are currently viable. 

So Suez normalisation continues. But the underlying vulnerability has arguably increased. The Houthis have retained and potentially strengthened their ability to interfere with traffic through Bab el-Mandeb should their intentions or the wider conflict change.

Shippers forum question the return

That contradiction is causing concern among cargo owners, with The Global Shippers Forum questioning whether carriers are returning too quickly given the continuing instability and the Houthis’ close relationship with Iran.

GSF director James Hookham described the increasing number of Red Sea transits as potentially a “reckless gamble”, arguing that shippers need more information about the security assessments underpinning carriers’ decisions.

Carriers maintain that safety remains the determining factor and that decisions to transit the Red Sea follow extensive security assessments informed by international and regional security organisations, with a commitment to stop transiting if there were indications that container vessels were again being targeted.

The absence of attacks on container ships for more than a year provides some reassurance. But a renewed threat could quickly send services back around the Cape, absorbing vessel capacity and extending transit times. A sudden reversal during the September and October shipping period could also disrupt cargo moving ahead of Black Friday and Christmas.

Further east, the picture is very different

The Strait of Hormuz remains severely restricted for container shipping after more than six months of disruption. Container ships have represented only around 6% of recorded inbound and outbound vessel transits during the conflict, with regular liner services largely avoiding the waterway.

Recent developments have added to the uncertainty. Iran has expanded a vessel blacklist that can potentially expose designated ships to fines, detention or confiscation, while vessels involved in transhipment with listed tonnage could also face restrictions.

Attacks on vessels have reinforced the risks, while diplomatic efforts to establish a framework for future shipping through Hormuz have stalled.

For Gulf importers, this has already reshaped supply chains.

Cargo is increasingly using alternative gateways such as Jeddah and Khor al Fakkan before moving overland. Demand for these alternatives has pushed China–Jeddah spot rates around 256% higher than before the conflict, while China–Khor al Fakkan rates have increased almost 480%.

Overland transport is consequently becoming a more important part of regional logistics. Greater use of the TIR trucking system through Iraq is opening additional options for upper Gulf markets, with some journeys between Europe, Turkey, Iraq and the Gulf dramatically reducing transit times compared with disrupted maritime routes.

But landbridges are not a direct substitute for ocean capacity. They add handling, road transport and border requirements, while growing demand is putting pressure on available trucking capacity and costs.

The wider conflict also matters far beyond Middle East cargo. Rising oil and bunker prices have the potential to feed into fuel surcharges and shipping costs across global trade lanes.

For shippers, the question is no longer simply whether a particular route is open. It is how dependable that route will remain, what alternatives exist if conditions change and how quickly cargo can be switched when they do.

Metro monitors carrier networks, regional gateways and changing conditions across the Middle East to identify emerging risks before they reach your supply chain. 

With global ocean freight expertise, alternative routing options and joined-up origin-to-destination management, we can help you balance cost, transit time and resilience, to keep your cargo moving when routes or risk change.

Suez MSC vessel

Red Sea return gathers pace, but risks remain

Container shipping through the Red Sea and Suez Canal is gradually increasing as major carriers test a return to the shorter Asia–Europe route, potentially signalling an important change for global supply chains.

But this is far from a return to normal. Recent deadly attacks demonstrate that security conditions remain volatile, while carriers are assessing individual sailings carefully and retaining the option to divert around the Cape of Good Hope at short notice.

For shippers, the potential benefits of shorter transit times must therefore be weighed against continuing routing uncertainty, war-risk insurance costs and the possibility that a broader return to Suez could create new congestion elsewhere in the network.

Carriers cautiously increase Suez transits

Maersk currently has four services passing through the Bab el-Mandeb Strait in both directions each week, equivalent to around one-third of its normal service pattern. The carrier believes current intelligence and security assessments support a gradual return, although every sailing remains subject to an individual risk assessment.

Hapag-Lloyd is taking a similarly cautious approach and expects any increase in Suez services to happen progressively rather than through an immediate network-wide switch.

Other carriers are also adding capacity. Cosco has reopened bookings for Red Sea services and is preparing a Far East–Red Sea rotation through Bab el-Mandeb, while CMA CGM already operates several services using Suez. The Gemini network has also moved additional Asia–Mediterranean services back towards the Red Sea.

The operational attraction is significant. Restoring the Suez route reduces the additional sailing distance created by Cape diversions and could ultimately release vessel and container capacity into a market already experiencing equipment and space constraints.

That is particularly relevant following severe weather disruption in China. Typhoon Dolphin closed operations at Ningbo and Shanghai during 7–8 August, leaving more than 2.4 million TEU of capacity across networks affected by the shutdown and subsequent congestion. With backlogs potentially taking weeks to clear, shorter vessel rotations could help carriers make more effective use of constrained fleets and equipment.

However, recent traffic data highlights how quickly sentiment can change. Total Red Sea/Suez transits fell from 255 vessels to 222 in a week, as operators adopted a more cautious approach following the renewed Houthi attacks.

Security risk translates directly into costs

The biggest obstacle to a sustained return remains security. A deadly attack on a commercial vessel off Yemen in August reinforced the wider and continuing threat to shipping, while missile and drone attacks have maintained uncertainty around the Bab el-Mandeb corridor.

Carriers are consequently treating Red Sea routings as conditional rather than permanent. A deterioration in security could prompt individual sailings, entire services or wider networks to return to the Cape route with relatively little notice.

For cargo owners, that uncertainty has an important financial dimension. Standard marine cargo policies typically exclude war risks, meaning shipments entering designated high-risk areas may require specific endorsements. Current market indications suggest Red Sea war-risk cover can cost approximately 0.5% to more than 1% of insured cargo value per voyage. Carriers may also pass additional security and operating expenses to customers through specialised risk surcharges.

Insurance availability itself can vary according to the cargo, vessel and parties involved. Some underwriters may restrict or refuse particular risks, while routing changes need to be declared correctly to avoid potential coverage issues.

Shippers should therefore consider the total cost and risk of the routing, rather than assuming that a shorter Suez transit automatically produces a cheaper supply chain.

A return could create another wave of disruption

There is another complication. A large-scale return to Suez could initially increase congestion rather than improve schedule reliability.

Cape diversions have fundamentally altered vessel arrival patterns. Switching significant numbers of ships back to the shorter route would change those patterns again, potentially creating bunching as vessels reach European terminals earlier and in different sequences.

That is particularly important while European ports are already managing congestion and inland transport constraints that are heightened by limited barge availability. Carriers are therefore planning phased returns partly to avoid overwhelming terminals.

For shippers, the next phase of the Red Sea situation could consequently bring both opportunity and uncertainty. Shorter routings may improve transit times and eventually release capacity, but security assessments, insurance premiums, surcharges and rapidly changing schedules will remain important considerations.

Metro monitors carrier routings, security developments, insurance implications and schedule changes across the Red Sea, Suez and Cape alternatives, helping customers understand the true cost and operational impact of each option. With conditions capable of changing from one sailing to the next, talk to Metro before booking critical cargo so we can assess the routing, timing, cost and risk that best protect your supply chain.

To learn more, EMAIL Managing Director Andrew Smith today.