Cathay tailfins 1440x1080 1

Asia air freight enters autumn with momentum intact

Air cargo’s traditional summer slowdown has failed to significantly loosen the market, with resilient demand, constrained capacity and renewed growth on key ex-Asia lanes keeping pressure on space and pricing as autumn begins.

Global air cargo volumes were 6% higher year on year in August, following 5% growth in July. More recent data shows that momentum continuing into September, with worldwide chargeable weight in week 36 still 7% above the same period last year.

Asia remains central to that strength. High-tech exports, AI and data-centre equipment, manufacturing activity and e-commerce continue to support demand, while available lift has struggled to grow at the same pace.

The result is an ex-Asia market that is increasingly defined by individual origins and trade lanes rather than a single regional trend.

Capacity remains the critical constraint

Global air cargo capacity was flat year on year during August, pushing capacity utilisation three percentage points above August 2025 levels. Dedicated freighters are carrying much of the additional demand, with freighter traffic having increased almost 14% year on year in July.

Adding substantial new lift remains difficult. Delayed new aircraft deliveries and passenger-to-freighter conversion programmes are restricting expansion, while carriers have been quick to redeploy freighters towards stronger markets.

That flexibility became particularly visible following changes to European low-value import rules. Falling e-commerce traffic initially weakened China and Hong Kong–Europe volumes, prompting some freighter capacity to move towards the stronger transpacific market.

However, the European picture is now showing signs of stabilisation. China–Europe volumes returned to modest week-on-week growth during August, while Hong Kong–Europe traffic increased 6% in week 36, its third consecutive weekly rise. Mainland China volumes have also been growing by low single-digit percentages since early August.

This recovery is significant as the market moves beyond the summer period and towards the traditional fourth-quarter peak.

Ex-Asia pricing reflects a tighter market

Although global spot pricing has gradually eased from its earlier highs, it remained 24% above last year during August. The latest weekly figures also point to renewed upward pressure from Asia.

In week 36, Asia Pacific spot rates increased 3% week on week to Europe and 2% to the US. China and Thailand to Europe both rose 6%, while Taiwan increased 7%.

Across Asia Pacific as a whole, pricing to Europe stood 15% above last year, while rates to the US were 40% higher.

High-tech manufacturing hubs remain particularly firm. Recent year-on-year increases included around 25% from South Korea and Taiwan, 22% from Vietnam, 32% from Thailand and 42% from Malaysia.

The transpacific remains especially strong. AI-related equipment and other technology exports continue to support demand from Northeast and Southeast Asia, while China and Hong Kong volumes to the US have remained resilient despite significant changes to low-value import rules.

There are also signs that the initial shock from Europe's new e-commerce rules may be passing. China’s low-value exports to Europe fell sharply after the July changes, but the subsequent improvement in China and Hong Kong tonnage suggests the market is beginning to find a new balance.

That does not necessarily mean a conventional peak season is developing. Instead, shippers face a more fragmented market in which capacity can move quickly between corridors and individual origins can tighten independently.

Further pressure could come from fuel. Rising oil prices are increasing aviation fuel costs, creating the prospect of higher surcharges just as autumn demand begins to build.

For businesses moving time-sensitive cargo from Asia, the combination of resilient demand, limited capacity growth and rapidly changing trade-lane conditions makes early planning increasingly important.

Metro combines local expertise across Asia with global air freight buying power and real-time market intelligence to identify pressure before it reaches your supply chain. 

Whether you need secured capacity, alternative gateways, flexible routings or support through the autumn peak, our air freight specialists can build the right solution around your priorities and keep critical cargo moving.
Mundra Port

Container trade stays strong as disruption reshapes east–west markets

Global container trade is proving remarkably resilient, but record volumes mask a more complicated picture across the major east–west trades. Congestion, blank sailings and inland constraints are increasingly determining the conditions shippers experience.

July set a new monthly record for global container shipping, with 17.3 million TEU moved worldwide. Volumes were 4.5% higher than July 2025 and are running 5.1% ahead year to date.

That underlying strength matters. Despite geopolitical disruption, changing tariffs and widespread port delays, international containerised trade continues to grow.

But demand alone does not explain current freight conditions. Carrier capacity management, severe congestion at Asian ports and pressure on destination transport networks are creating increasingly different conditions by trade lane.

East–west markets move apart

The clearest divergence is between Asia–Europe and the transpacific.

Asia–Europe spot rates have continued to soften, with Shanghai–Rotterdam falling another 2% and Shanghai–Genoa 3% in the latest weekly data. The traditional peak appears to have passed, although congestion and blank sailings are preventing a more rapid correction.

Across the Pacific, the picture is very different. Transpacific demand strengthened as the US peak season extended later than initially expected, with west coast volumes rising 9% week on week in early September and east coast volumes increasing 3%.

Rates have consequently remained firm. Shanghai–Los Angeles increased another 2% in the latest week and Shanghai–New York 1%, following larger gains the previous week.

However, demand is only part of the explanation. Carriers are becoming increasingly active in managing available space through blank sailings, vessel rotations and capacity deployment as China’s Golden Week approaches.

Across the major east–west trades, around 11% of scheduled sailings between mid-September and mid-October are currently expected to be cancelled. More than half of those cancellations are concentrated on the eastbound transpacific, with a further third affecting Asia–North Europe and Mediterranean services.

The pace of change is significant. Announced blank sailings for the four weeks leading into Golden Week jumped almost 56% in just one week, and further cancellations remain possible as carriers adjust networks around the Chinese holiday.

The overall level remains manageable, with almost nine in ten scheduled sailings still expected to operate. But the acceleration in cancellations points to a more active phase of capacity management.

For shippers, softer demand will therefore not necessarily translate directly into lower rates or easier access to space. How aggressively carriers remove capacity before Golden Week and how quickly demand returns afterwards could determine the balance between available space and pricing through October.

Congestion is moving through the network

Capacity management is only one part of the east–west picture. Four successive typhoons have left major Chinese ports working through substantial backlogs.

Between early July and late August, almost 5.8 million TEU of vessel capacity arrived more than seven days late at Chinese ports, which is around three times the level recorded before the storms.

The impact on schedule reliability has been dramatic. According to figures from Sea-Intelligence, global reliability fell over 6% in July to 56.4%, its sharpest monthly deterioration in more than five years, while late vessels were arriving an average of over six days behind schedule.

Conditions became particularly challenging on east–west services during the typhoon period. Asia–Europe on-time performance fell to around 10%, while Asia–North America dropped to 23%.

Although congestion is gradually easing, the network has yet to recover fully. The combination of existing backlogs, the pre-Golden Week export push and subsequent factory closures could prolong disruption into October, with bunched vessel arrivals then feeding through to European and North American ports.

That is particularly relevant in the US, where pressure is already building beyond the quayside.

The National Drayage Spot Market Index is 8.2% higher year on year as driver availability, equipment constraints, terminal turn times and appointment availability tighten the market.

Import containers are waiting six to seven days on average for inland transport at some locations and up to 14 days at individual terminals. Pressure has been reported around Los Angeles/Long Beach, Houston, Chicago, Memphis, Savannah and other inland gateways.

For US importers, securing ocean space is therefore only one part of the challenge. Drayage and inland capacity need to be planned earlier, particularly when disrupted schedules result in several vessels and large volumes of cargo arriving within a compressed period.

India disruption continues beyond Mundra strike

The end of the 13-day dispute affecting empty container yards at Mundra has not brought an immediate return to normal operations.

The strike officially ended on 10 September, but Metro’s team in India continues to report around 5,000 containers delayed each day, with empty container flows particularly affected.

The scale of Mundra makes those continuing delays significant. The port accounts for around 35% of India’s container trade, so disruption can quickly affect equipment availability, exports and wider regional supply chains.

The situation also highlights India’s growing importance within international sourcing strategies as businesses diversify their supply chains and increase manufacturing and procurement activity across the subcontinent.

Metro India continues to scale strategically in response. The business is expanding across seven locations, creating a stronger platform for sourcing, consolidation, origin management and exports across the Indian subcontinent.

Overall, ocean markets remains stronger and more complicated than headline rate movements suggest. Global container volumes are setting records, but where carriers deploy capacity, how quickly Asian ports clear backlogs and whether inland networks can absorb arriving cargo will shape conditions through Golden Week and into October.

We may return to examine these developing themes in more detail, as the impact of Golden Week becomes clearer.

Metro combines global ocean freight buying power with local expertise across key origin and destination markets, including our expanding operation in India and established US network. We monitor capacity, blank sailings, port conditions, equipment availability and inland constraints throughout the journey, giving customers the intelligence and routing options to act before disruption reaches their supply chain.

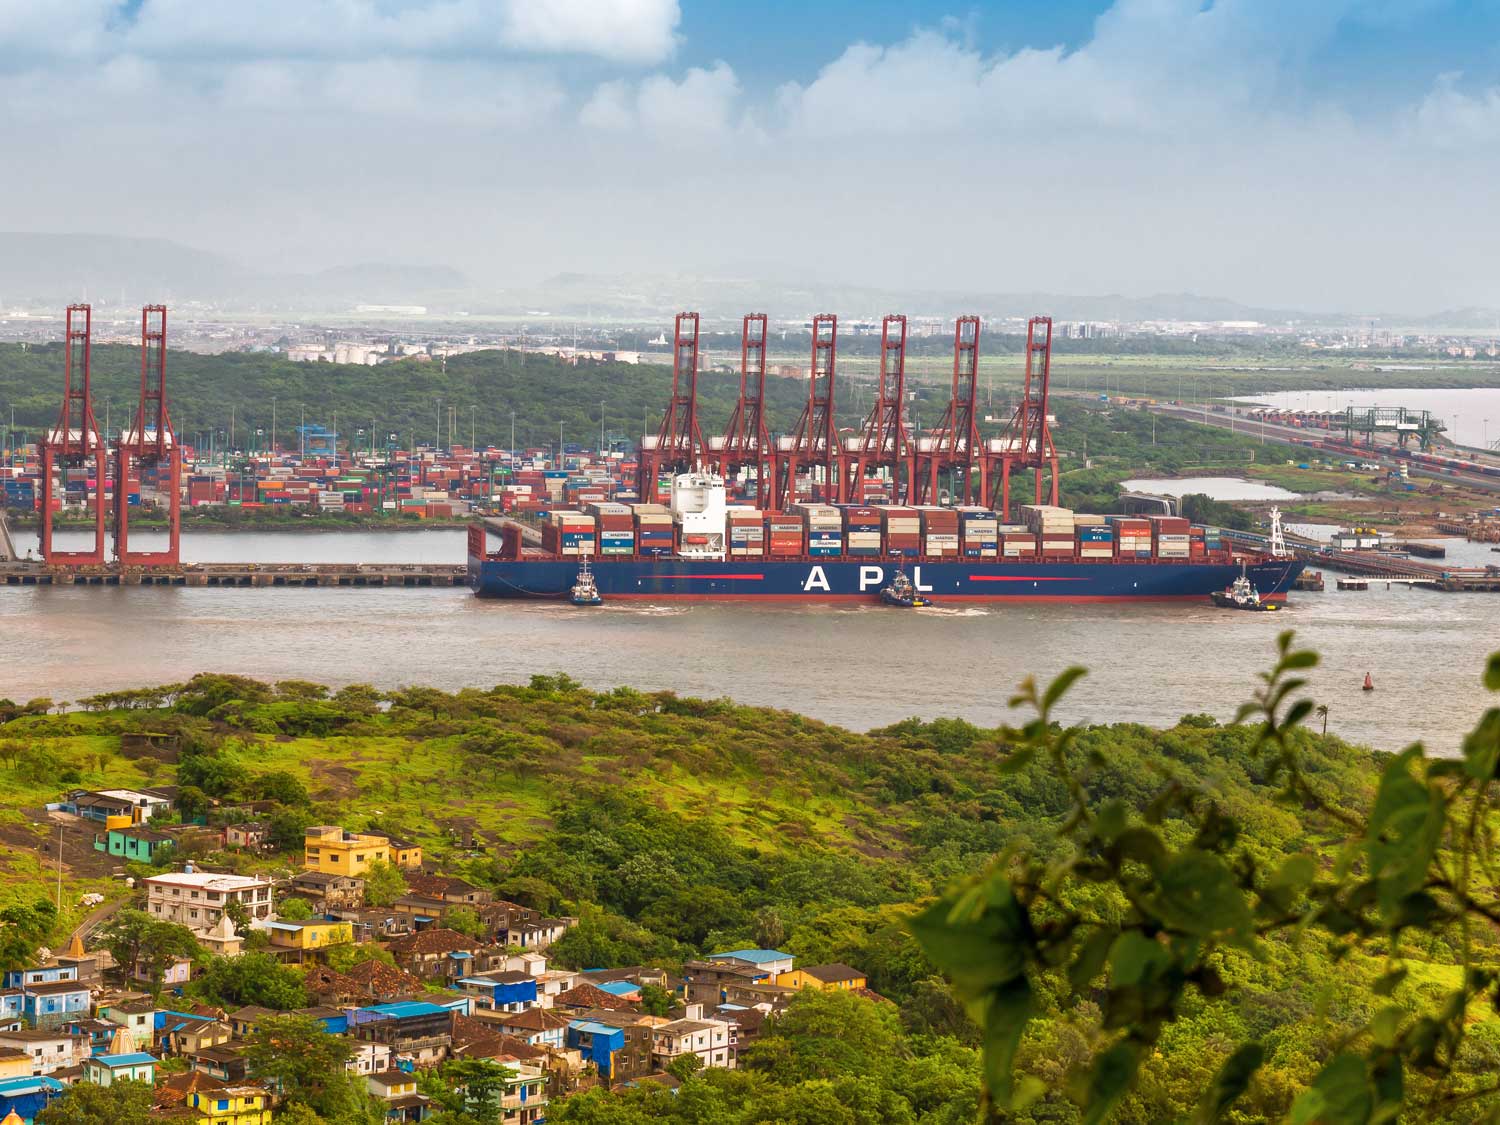
Image: Adapted from The port of Mundra in Gujarat by Felix Dance, via Wikimedia CommonsCC BY 2.0.

ULD on tarmac

Air freight market tightens ahead of autumn peak

Air freight enters the traditional peak-season build-up with a finely balanced market, as capacity reductions and resilient pricing create the potential for rapid tightening when Asian export demand accelerates.

The usual late-September surge may still be several weeks away, but UK importers have good reason to start planning now.

Asia–Europe demand softened during August, yet rates have shown little corresponding weakness. Airlines and freighter operators are adjusting capacity as cargo flows change, while higher fuel costs and stronger demand on alternative trade lanes are providing additional support.

That leaves limited spare capacity to absorb the traditional autumn increase – particularly if ocean freight disruption pushes urgent shipments towards air.

Softer demand is not delivering cheaper capacity

Asia Pacific–Europe chargeable weight fell 5% week on week and 14% year on year in week 33, continuing the softer trend evident since late June.

Changing e-commerce flows have contributed to the decline. China–Europe volumes were 8% lower year on year in week 32, while Hong Kong–Europe traffic fell 29%.

Despite that weakness, Asia Pacific–Europe spot rates remained flat in week 33 after rising 1% the previous week. China was particularly resilient, recording a 6% increase despite lower volumes.

The explanation lies partly on the supply side. Asia Pacific capacity contracted 2% in week 33 after declining 1% the previous week, limiting the downward pressure on rates.

Freighter deployment may tighten the market further. Stronger transpacific demand provides operators with an incentive to allocate aircraft towards the US, potentially reducing the capacity available for European cargo as peak season approaches.

China shows how quickly conditions can change

Recent disruption around Shanghai illustrates the vulnerability of available capacity.

Typhoon Dolphin caused more than 1,000 flight cancellations and contributed to an 8% weekly reduction in chargeable weight from Shanghai, while Shanghai–Europe volumes fell 7%.

The immediate disruption has eased, but severe weather and congestion across Chinese ocean gateways remain relevant to the air freight outlook. When container schedules become unreliable, urgent and time-sensitive cargo can quickly switch from ocean to air.

Even a relatively small modal shift can have a disproportionate effect on air freight capacity and pricing.

Golden Week could mark the turning point

The next significant test comes around China's Golden Week.

Factories traditionally accelerate production before the holiday, followed by another increase as operations resume and backlogs clear. October also brings the start of the main pre-Christmas replenishment cycle.

Demand then typically intensifies through November as retailers and e-commerce businesses prepare for Black Friday, Cyber Monday and Christmas.

This year, however, the market enters that period with capacity already responding closely to demand. That could make the transition from today's relatively balanced conditions to a tighter market particularly rapid.

Fuel costs, severe weather, changing freighter deployment and disruption to ocean services provide additional variables.

The opportunity is before the peak

For shippers, softer August volumes could offer a useful planning window rather than a reason to wait for lower rates.

Businesses with visibility of their autumn requirements can secure allocations earlier, consider alternative origins and gateways, and decide which shipments genuinely require premium air services.

Booking ahead of cargo-ready dates will become increasingly important as demand builds, particularly from China and other major Asian export markets. Flexible routing can also provide valuable alternatives when individual gateways or direct services tighten.

The key consideration is not simply today's air freight rate, but the availability of the right capacity when cargo needs to move.

Metro combines extensive Asian origin coverage with global airline relationships, flexible routing and multiple service levels to keep UK supply chains moving when peak-season capacity tightens. 

Share your autumn forecasts with Metro now and we can secure the capacity, routing and service strategy your cargo needs before the peak takes hold.

EMAIL Andrew Smith, Metro’s Managing Director.

Nhava Sheva

Customer Advisory: India and China Container Shipping Disruption

Container shipping markets in India and China are experiencing significant operational disruption, resulting in longer transit times, reduced schedule reliability, constrained equipment availability and rising freight costs.

Metro is working closely with shipping lines, terminals and inland partners to minimise disruption and identify practical alternatives for affected cargo. Customers are advised to plan shipments as early as possible and allow additional time throughout their supply chains.

India market update

The Indian container market is under sustained pressure across both export and import supply chains.

A combination of strong export demand, restricted carrier capacity, equipment shortages and ongoing congestion at key gateway ports is making vessel space increasingly difficult to secure. These conditions are contributing to vessel rollovers, revised sailing schedules, extended transit times, peak season surcharges (PSS) and highly volatile freight rates.

The India–US and Latin America trades remain under the greatest pressure, particularly for cargo moving to the US East Coast.

Freight rates and surcharges

Spot-market freight levels for India–US East Coast shipments are currently ranging from approximately USD 10,000–12,000 per 40HC, depending on port pairing, routing and available capacity.

Carriers continue to introduce Peak Season Surcharges for both spot and contract cargo. These charges increased through August, with further increases being announced for September.

On the India–US East Coast trade:

  • Average August PSS levels are around USD 5,000 per 40HC
  • Maersk has announced a PSS increase to USD 7,500 per 40HC, effective 1 September
  • Further PSS increases remain possible across other India export markets

Rate volatility is expected to continue into September as carriers maintain tight capacity controls and place further pressure on allocations.

Port congestion and equipment availability

Active monsoon conditions are affecting port operations and inland transport across India’s west coast. The disruption is expected to continue in the near term and may cause further delays to container movements, terminal operations, rail services and road transport around major gateways. 

Major Indian gateways, particularly Nhava Sheva/JNPT, continue to experience congestion caused by vessel bunching, terminal capacity pressure, rail delays and limited transport equipment availability.

Key gateways potentially affected include:

  • JNPT / Nhava Sheva: India’s busiest container gateway and a major export hub for US-bound cargo
  • Mundra: India’s largest private container port, handling significant volumes of US-bound exports
  • Hazira: An important feeder and export gateway for manufacturing cargo from Western India

Container availability, particularly for 40HC equipment, remains inconsistent at several export locations. This may delay booking confirmation and require longer lead times for exporters.

Customers should anticipate additional variability in shipment timing, particularly where cargo depends on inland positioning or feeder connections.

China port disruption

Typhoon Dolphin has created further disruption at Chinese ports following the impact of Typhoon Bavi just weeks earlier.

The storm brought heavy rain and strong winds to Zhejiang province before moving on as a tropical storm. Authorities have warned of continued risks from torrential rain, flooding and landslides, while flight cancellations and transport disruption have also affected the wider region.

Port and vessel impact

Temporary closures at Shanghai, Ningbo-Zhoushan and surrounding feeder ports disrupted cargo handling and vessel movements.

Current impacts include:

  • Vessels delayed, held at anchorage or diverted to alternative ports
  • Service schedules changing at short notice
  • Delays of 7–21 days remaining common on affected services, with some potentially longer
  • Ongoing congestion as terminals process accumulated cargo
  • Localised disruption to rail, road and barge transport, despite conditions gradually improving

Port productivity is beginning to recover in some locations, but congestion and schedule disruption are expected to persist while backlogs are cleared.

Metro will continue to monitor developments closely and work with carriers and partners to secure capacity, explore alternatives and keep customers informed of material changes.