El Nino

El Niño puts temperature-controlled supply chains under new pressure

Climate volatility is becoming an increasingly important cold-chain risk, as extreme temperatures, disrupted transport networks and the developing El Niño pattern threaten the reliability and cost of moving perishable goods.

For food and beverage supply chains, weather has always influenced production and logistics. What is changing is the frequency, severity and interconnected nature of that disruption.

Higher ambient temperatures put refrigeration equipment under greater strain, while floods, storms, drought and infrastructure disruption can extend transit times and increase the risk of temperature excursions. At the same time, changing weather patterns are affecting where food is produced and how it reaches major consumer markets.

El Niño could amplify those pressures through late 2026 and into 2027, just as Europe and North America become increasingly dependent on refrigerated imports from Latin America.

Cold-chain trade is shifting south

The geography of refrigerated container trade is changing. North-south reefer trades are growing faster than traditional east-west flows, with North America and Europe importing 1.49 million TEU of refrigerated goods from Mexico, Central America and South America during 2025 – an 8.9% increase year on year.

South America is becoming increasingly important for products ranging from fresh fruit and vegetables to meat. West Coast South America–North America reefer trade has grown 24% over five years, while Peru has emerged as an increasingly significant source of refrigerated imports.

That growing dependence means disruption to Latin American production or shipping can have consequences thousands of miles away.

El Niño could disrupt harvests and shipping

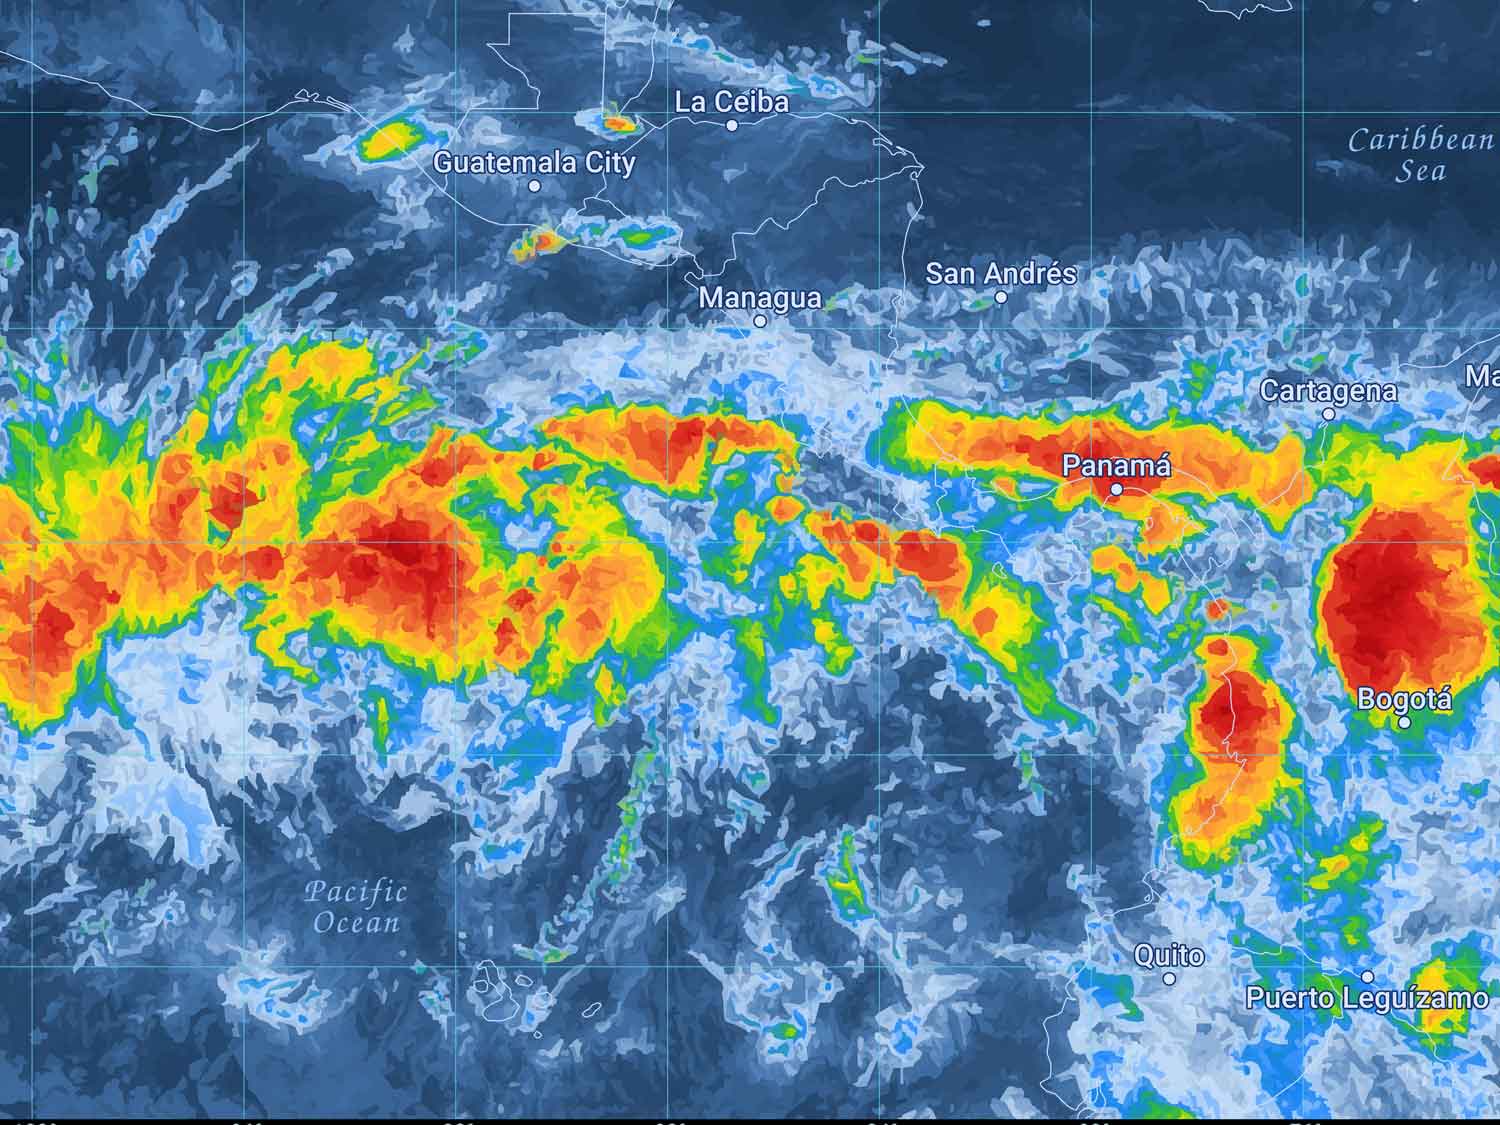
The developing El Niño pattern creates risks at both ends of the supply chain. Its effects are forecast to peak during the fourth quarter of 2026 and first quarter of 2027, coinciding with the Southern Hemisphere harvest season.

Parts of South America could experience alternating drought and coastal flooding, threatening agricultural production and export flows. Chile, Colombia and Peru are among the markets considered particularly exposed. 

Demand for food does not disappear when production is disrupted. Buyers may instead need to switch sourcing regions, creating sudden changes in trade flows and demand for refrigerated equipment and vessel capacity.

The Panama Canal adds another complication. Falling water levels and tighter transit restrictions can reduce vessel intake and disrupt schedules on an important route connecting Latin American production with Northern Hemisphere markets.

Heat increases the risks in transit

Climate pressure does not end once produce has been harvested. Higher ambient temperatures increase the thermal load on refrigerated containers, warehouses and transport equipment. Refrigeration systems work harder, energy consumption rises and equipment operating close to its limits becomes more vulnerable to reduced efficiency or failure.

The points between temperature-controlled environments become particularly important. Loading, unloading and other handling processes expose cargo to ambient conditions, reducing the margin for delay when outside temperatures rise.

Extreme weather can simultaneously close roads, disrupt ports, interrupt power supplies or delay vessels. For temperature-sensitive food, an extended journey is not simply an inconvenience: it can affect quality, shelf life and ultimately product viability.

Reefer capacity is already under pressure

These risks are developing against an already firm refrigerated freight market. Reefer plug availability remains limited in some locations, alongside supporting equipment such as chassis gensets. Elevated fuel costs and strong overall container demand are also adding pressure.

The composite refrigerated freight index for the third quarter of 2026 is 20% higher than a year earlier. 

For lower-value agricultural commodities, freight inflation can become particularly significant because logistics represents a greater proportion of the product's value.

Weather disruption could tighten the equation further. Changes in harvest volumes, sourcing locations and shipping routes can create sudden demand for reefer equipment in places where it was not originally positioned.

Cold chains need to become more adaptable

As historic weather patterns become less reliable, cold-chain planning increasingly needs to account for conditions outside traditional assumptions.

Real-time temperature monitoring can identify excursions before they compromise cargo, while greater visibility across transport legs helps businesses respond when delays occur.

Contingency routing and alternative sourcing can reduce dependence on individual gateways or production regions. Reviewing refrigeration performance, backup power and thermal protection can also help identify vulnerabilities before extreme conditions expose them.

For importers, the objective is increasingly to understand the entire cold chain – from changing conditions at origin through ocean transport and port handling to final delivery.

The coming El Niño cycle provides a timely reminder that temperature control alone does not create cold-chain resilience. Sourcing, capacity, routing, equipment, monitoring and contingency planning all need to work together.

Protecting temperature-sensitive supply chains

Metro has extensive experience supporting the food and beverage sector and managing complex temperature-controlled supply chains from origin to final delivery. 

Our global network, cold-chain expertise and access to alternative carriers, routes and solutions give customers the flexibility to respond when weather changes production, capacity or transit conditions. 

When product integrity and shelf life leave no room for error, EMAIL Andrew Smith, Metro’s Managing Director, about building a cold chain designed to keep performing when conditions do not.
Rhine low water levels

Falling Rhine levels put European supply chains under growing pressure

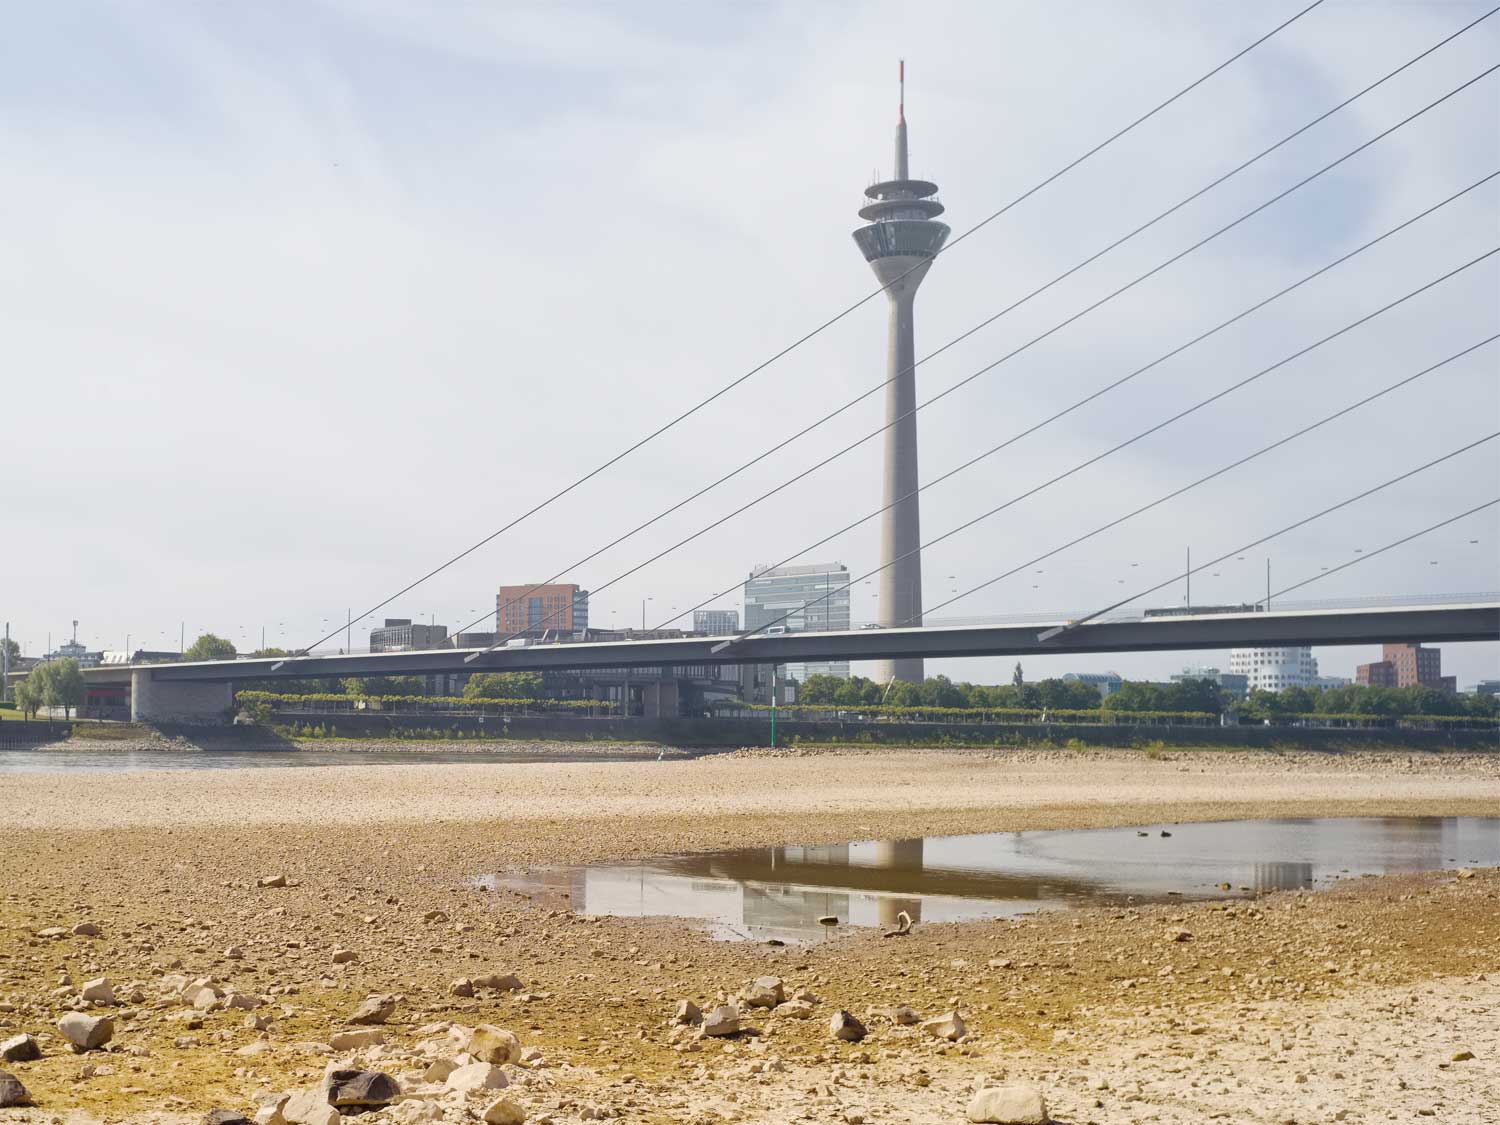
Record-low water levels on the Rhine are creating another significant challenge for European supply chains, restricting barge capacity, increasing transport costs and putting additional pressure on already constrained road and rail networks.

The Rhine is one of Europe's most important freight arteries, connecting Rotterdam and Antwerp-Bruges with industrial centres across Germany, France and Switzerland. Around 35% of containers moving between Rotterdam and their hinterland travel by inland waterway, making reliable barge operations an important part of the region's freight infrastructure.

Persistent heat and drought have pushed water levels to exceptional lows, particularly around Kaub in Germany, a critical point for navigation on the Middle and Upper Rhine. Conditions have deteriorated to the point where some operators have suspended bookings beyond Kaub and sections of the river have become extremely difficult for container traffic.

The immediate problem is not simply whether barges can sail. Lower water levels dramatically reduce the amount of cargo they can safely carry.

Capacity disappears as the Rhine falls

Water levels at key Rhine gauges have fallen as low as 7cm at critical points, severely restricting barge operations and the impact on effective capacity is dramatic. 

Some mid-sized container barges with a nominal capacity of around 300 TEU are reportedly able to carry only about 20% of their normal capacity, while larger barges offering around 400 TEU of capacity have been completely unable to navigate some river stretches.

That creates an unusual form of supply chain disruption. The physical infrastructure remains in place, but much of its freight capacity has effectively disappeared.

Costs are rising accordingly. Low-water surcharges on the most severely affected sections have reached €1,350 per TEU around Kaub and €895 per TEU around Cologne, adding 

potentially substantial costs to container movements into Germany and Central Europe.

The disruption also threatens cargo flows through Europe's two largest container gateways. Around 35% of containers moving between Rotterdam and its hinterland travel by inland waterway, illustrating the scale of the potential problem if barge capacity remains restricted.

If containers cannot move inland quickly enough, they can accumulate at terminals in Rotterdam and Antwerp, potentially transferring congestion from the Rhine back towards the deep-sea ports.

Road and rail cannot simply replace barges

Shippers are increasingly turning to road and rail, but neither mode has enough spare capacity to replace lost barge movements quickly.

The scale of the substitution challenge is significant. Moving the containerised cargo carried by one barge can require more than 200 trucks. Replicating barge capacity by road would therefore place considerable additional pressure on trucking networks while increasing cost, congestion and emissions.

Available capacity is already tightening. In the most constrained areas, securing a truck can reportedly take up to two weeks, while additional rail capacity can require as much as six weeks' advance notice.

Rail also faces infrastructure constraints. Major renovation work on the Troisdorf–Wiesbaden corridor is restricting capacity on an important freight connection between Germany's inland regions and its European seaport gateways, just as demand for alternatives to barge transport is increasing.

The additional pressure is now feeding directly into transport costs. From 20 August, new congestion surcharges are being applied to selected container movements from Rotterdam and Antwerp, including €44 per container for trucking and €50 per container for rail and combined rail-road movements to and from affected German and Alsace locations.

For shippers, low Rhine levels are therefore no longer simply an inland-waterway issue. They are increasing costs and reducing available capacity across barge, road and rail simultaneously, while extending lead times and increasing the risk of missed delivery windows.

Weather is becoming a global supply chain variable

Extreme weather is increasingly affecting freight networks across different regions and modes. European heatwaves and drought are restricting inland waterways, while typhoons have recently disrupted Chinese ports and contributed to container and vessel-space shortages. Drought and water-management measures are also restricting vessel loading through the Panama Canal.

These events may be thousands of miles apart, but their supply chain effects are remarkably similar: effective capacity falls, schedules become less reliable, alternative routes become congested and transport costs increase.

As Metro recently highlighted in its analysis of how climate is becoming one of the biggest supply chain risks, extreme low-water events on the Rhine have reportedly occurred more frequently during the past decade than in the preceding five decades.

Contingency planning can no longer focus solely on recovering from an exceptional event. Shippers increasingly need supply chains designed to accommodate weather-related disruption as an ongoing operational risk.

Recovery could create another bottleneck

Rainfall would improve the situation, but higher water levels would not produce an immediate return to normal operations.

Barges and equipment displaced by weeks of disruption need to return to their scheduled rotations. A rapid recovery could also result in vessels arriving simultaneously at Rotterdam and Antwerp, transferring congestion from the river back towards the ports.

Shippers therefore need to consider both the immediate disruption and the recovery period that follows it.

Metro builds resilience beyond the port

When a major transport artery loses capacity, waiting for conditions to improve is rarely enough. Shippers need visibility of the disruption, early access to alternative capacity and the ability to switch between barge, rail and road before those alternatives become constrained.

Metro works across the supply chain to identify vulnerabilities and develop contingency options around individual cargo flows. By considering port choice, inland routing, available capacity, lead times and total transport cost together, Metro can help customers protect deliveries when established routes come under pressure.

Weather may be increasingly unpredictable, but your response does not have to be. Metro helps build flexibility into your European supply chain, giving you the options to keep cargo moving when critical links cannot operate as planned.

To learn more, EMAIL Managing Director Andrew Smith today

Bangladesh label

India and Bangladesh exporters face capacity squeeze

Exporters across India and Bangladesh are facing a difficult combination of strong demand, restricted vessel space, equipment shortages and weather-related disruption, with pressure particularly acute on westbound services to Europe and North America.

Although the underlying causes vary between the two markets, the consequences are similar. Shippers are competing harder for vessel allocations, paying significantly more for available capacity and allowing additional time for cargo to reach its destination.

The situation also illustrates a wider shift in global supply chains. Extreme weather is increasingly interacting with existing capacity constraints, port congestion and geopolitical disruption, turning what might once have been relatively isolated events into much broader operational problems.

Bangladesh loses capacity as carriers prioritise stronger markets

Bangladesh exporters are experiencing a sharp reduction in available ocean capacity as carriers allocate more vessel space and equipment towards China ahead of Golden Week.

One carrier indicated that its Bangladesh booking allocation had fallen from around 2,000 containers to 1,500, a 25% reduction. Equipment is also being repositioned towards China, leaving exporters from Chattogram competing for fewer containers and mother-vessel slots.

Bangladesh is particularly exposed because most exports do not move directly to Europe or North America. Containers typically travel by feeder to hubs including Colombo, Port Klang and Singapore before connecting with larger vessels. When capacity tightens at these transhipment points, Bangladesh allocations can quickly come under pressure.

Continuing Middle East disruption is adding to the problem. Longer vessel rotations around the Cape of Good Hope are absorbing capacity, with Asia–Europe rates reported to be 25% to 40% higher and Asia–US East Coast rates 15% to 25% higher.

For Bangladesh exporters, the increases have been considerably greater. Chattogram–US freight has risen by nearly 130% in a month, while reported pricing to Hamburg has increased by around 140%.

Some shipment bookings are also facing an additional two to three weeks in lead time. Businesses operating under Delivered Duty Paid terms have the greatest immediate financial exposure, although FOB exporters still face the commercial consequences of restricted capacity and delayed deliveries.

Airfreight offers an alternative for urgent cargo, but capacity from Dhaka is also tightening. Europe-bound shipments face particularly strong demand, making early booking and selective use of airfreight increasingly important for protecting critical delivery dates.

India–Europe demand pushes vessel space to a premium

India’s westbound market is experiencing its own capacity squeeze as export demand strengthens faster than available vessel space.

Indian containerised exports to Europe reached an estimated 518,000 TEU during the first half of 2026, while some key carrier services are already fully allocated through August and, on selected sailings, into early September.

Spot freight rates from Nhava Sheva and Mundra to major UK and European gateways have increased by approximately 10% to 15% since late July, reaching their highest levels in around four years. With guaranteed space increasingly valuable, shippers are also facing premiums where they need firm allocations.

Part of the constraint reflects carrier network decisions, including the reallocation of some India–Europe capacity towards growing Latin American flows. Blank sailings, rolled cargo and fluctuating allocations are adding further pressure.

But operational disruption at India’s major gateways is also playing an important role. Congestion at Nhava Sheva and Mundra has reduced vessel productivity and complicated cargo flows, while active monsoon conditions create further uncertainty for port operations and inland road and rail connections.

That matters because weather disruption is increasingly becoming an interconnected supply chain risk rather than simply a temporary port problem. Across Asia, tropical storms and extreme rainfall are affecting manufacturing, inland transport, terminals and vessel schedules simultaneously. A disruption at origin can then propagate through subsequent port calls and connections long after local conditions improve.

For exporters in India and Bangladesh, that combination makes early planning increasingly important. Securing space, allowing realistic lead times and retaining flexibility over gateways, routings and transport modes can provide valuable protection when capacity tightens or weather interrupts established schedules.

Metro combines extensive operations in India and Bangladesh to give shippers more options when ocean capacity becomes constrained. From securing vessel space and monitoring equipment availability to alternative routings, airfreight and air/sea solutions, we can identify pressure points early and build the flexibility your supply chain needs to keep critical cargo moving.

When capacity is scarce and disruption can develop quickly, talk to Metro before your shipment becomes urgent. EMAIL Managing Director Andrew Smith today

Suez MSC vessel

Red Sea return gathers pace, but risks remain

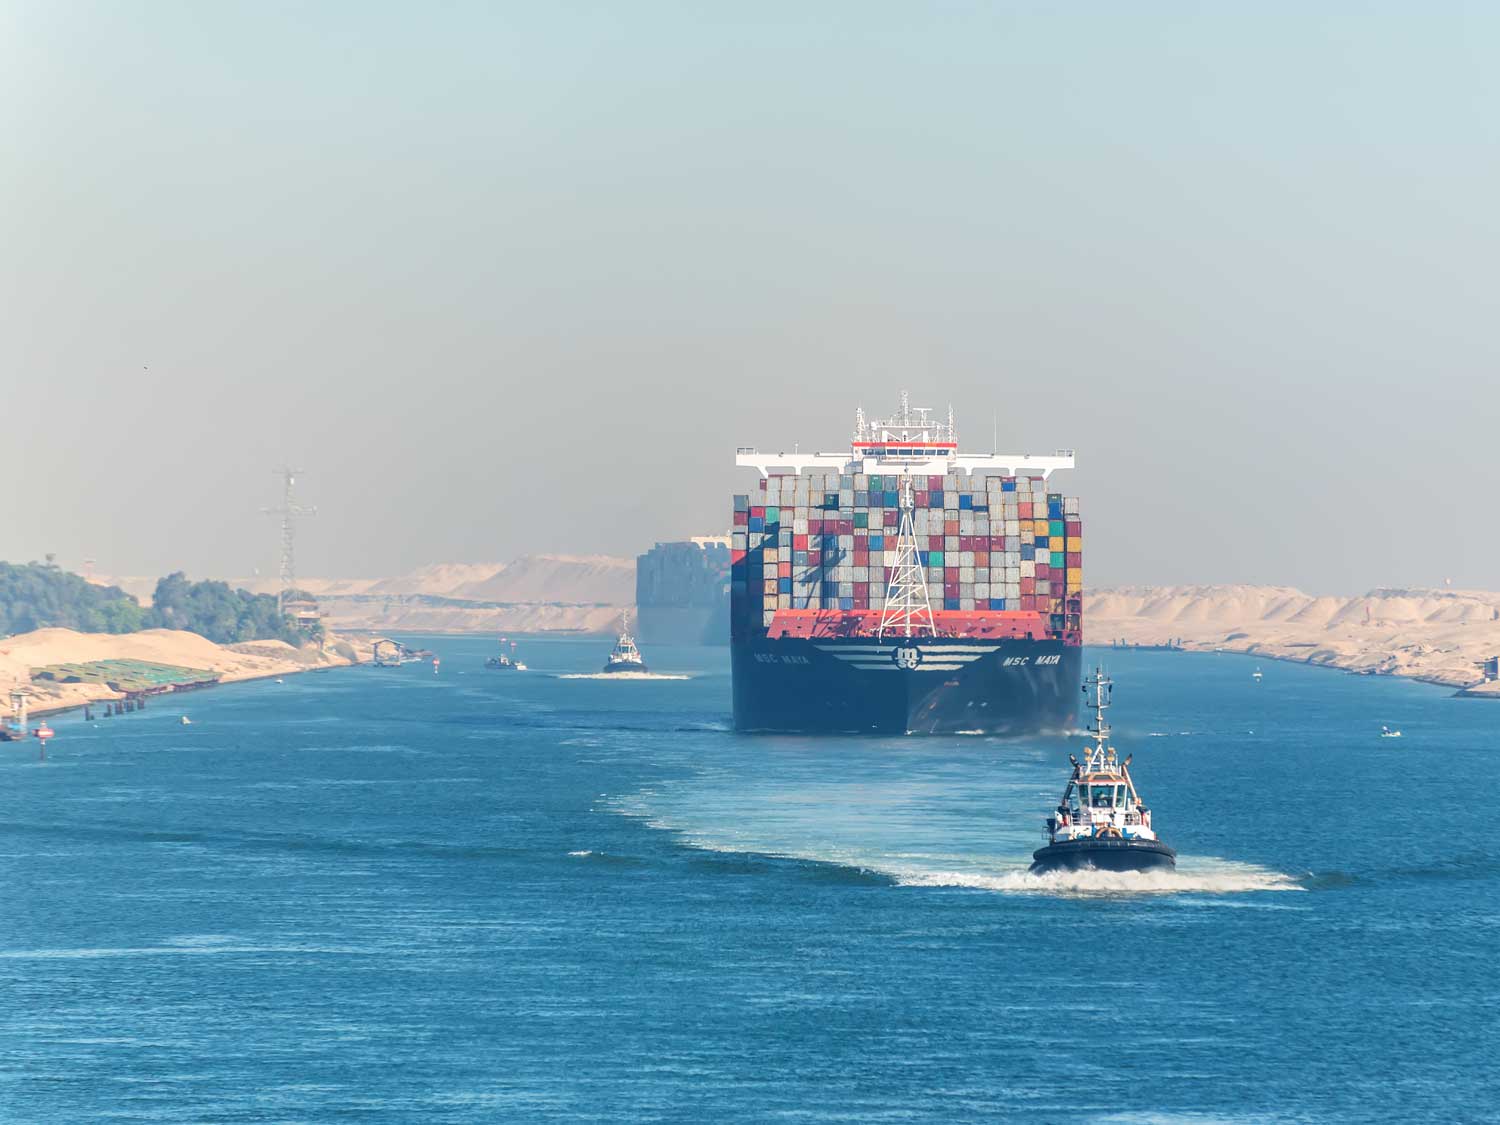
Container shipping through the Red Sea and Suez Canal is gradually increasing as major carriers test a return to the shorter Asia–Europe route, potentially signalling an important change for global supply chains.

But this is far from a return to normal. Recent deadly attacks demonstrate that security conditions remain volatile, while carriers are assessing individual sailings carefully and retaining the option to divert around the Cape of Good Hope at short notice.

For shippers, the potential benefits of shorter transit times must therefore be weighed against continuing routing uncertainty, war-risk insurance costs and the possibility that a broader return to Suez could create new congestion elsewhere in the network.

Carriers cautiously increase Suez transits

Maersk currently has four services passing through the Bab el-Mandeb Strait in both directions each week, equivalent to around one-third of its normal service pattern. The carrier believes current intelligence and security assessments support a gradual return, although every sailing remains subject to an individual risk assessment.

Hapag-Lloyd is taking a similarly cautious approach and expects any increase in Suez services to happen progressively rather than through an immediate network-wide switch.

Other carriers are also adding capacity. Cosco has reopened bookings for Red Sea services and is preparing a Far East–Red Sea rotation through Bab el-Mandeb, while CMA CGM already operates several services using Suez. The Gemini network has also moved additional Asia–Mediterranean services back towards the Red Sea.

The operational attraction is significant. Restoring the Suez route reduces the additional sailing distance created by Cape diversions and could ultimately release vessel and container capacity into a market already experiencing equipment and space constraints.

That is particularly relevant following severe weather disruption in China. Typhoon Dolphin closed operations at Ningbo and Shanghai during 7–8 August, leaving more than 2.4 million TEU of capacity across networks affected by the shutdown and subsequent congestion. With backlogs potentially taking weeks to clear, shorter vessel rotations could help carriers make more effective use of constrained fleets and equipment.

However, recent traffic data highlights how quickly sentiment can change. Total Red Sea/Suez transits fell from 255 vessels to 222 in a week, as operators adopted a more cautious approach following the renewed Houthi attacks.

Security risk translates directly into costs

The biggest obstacle to a sustained return remains security. A deadly attack on a commercial vessel off Yemen in August reinforced the wider and continuing threat to shipping, while missile and drone attacks have maintained uncertainty around the Bab el-Mandeb corridor.

Carriers are consequently treating Red Sea routings as conditional rather than permanent. A deterioration in security could prompt individual sailings, entire services or wider networks to return to the Cape route with relatively little notice.

For cargo owners, that uncertainty has an important financial dimension. Standard marine cargo policies typically exclude war risks, meaning shipments entering designated high-risk areas may require specific endorsements. Current market indications suggest Red Sea war-risk cover can cost approximately 0.5% to more than 1% of insured cargo value per voyage. Carriers may also pass additional security and operating expenses to customers through specialised risk surcharges.

Insurance availability itself can vary according to the cargo, vessel and parties involved. Some underwriters may restrict or refuse particular risks, while routing changes need to be declared correctly to avoid potential coverage issues.

Shippers should therefore consider the total cost and risk of the routing, rather than assuming that a shorter Suez transit automatically produces a cheaper supply chain.

A return could create another wave of disruption

There is another complication. A large-scale return to Suez could initially increase congestion rather than improve schedule reliability.

Cape diversions have fundamentally altered vessel arrival patterns. Switching significant numbers of ships back to the shorter route would change those patterns again, potentially creating bunching as vessels reach European terminals earlier and in different sequences.

That is particularly important while European ports are already managing congestion and inland transport constraints that are heightened by limited barge availability. Carriers are therefore planning phased returns partly to avoid overwhelming terminals.

For shippers, the next phase of the Red Sea situation could consequently bring both opportunity and uncertainty. Shorter routings may improve transit times and eventually release capacity, but security assessments, insurance premiums, surcharges and rapidly changing schedules will remain important considerations.

Metro monitors carrier routings, security developments, insurance implications and schedule changes across the Red Sea, Suez and Cape alternatives, helping customers understand the true cost and operational impact of each option. With conditions capable of changing from one sailing to the next, talk to Metro before booking critical cargo so we can assess the routing, timing, cost and risk that best protect your supply chain.

To learn more, EMAIL Managing Director Andrew Smith today.