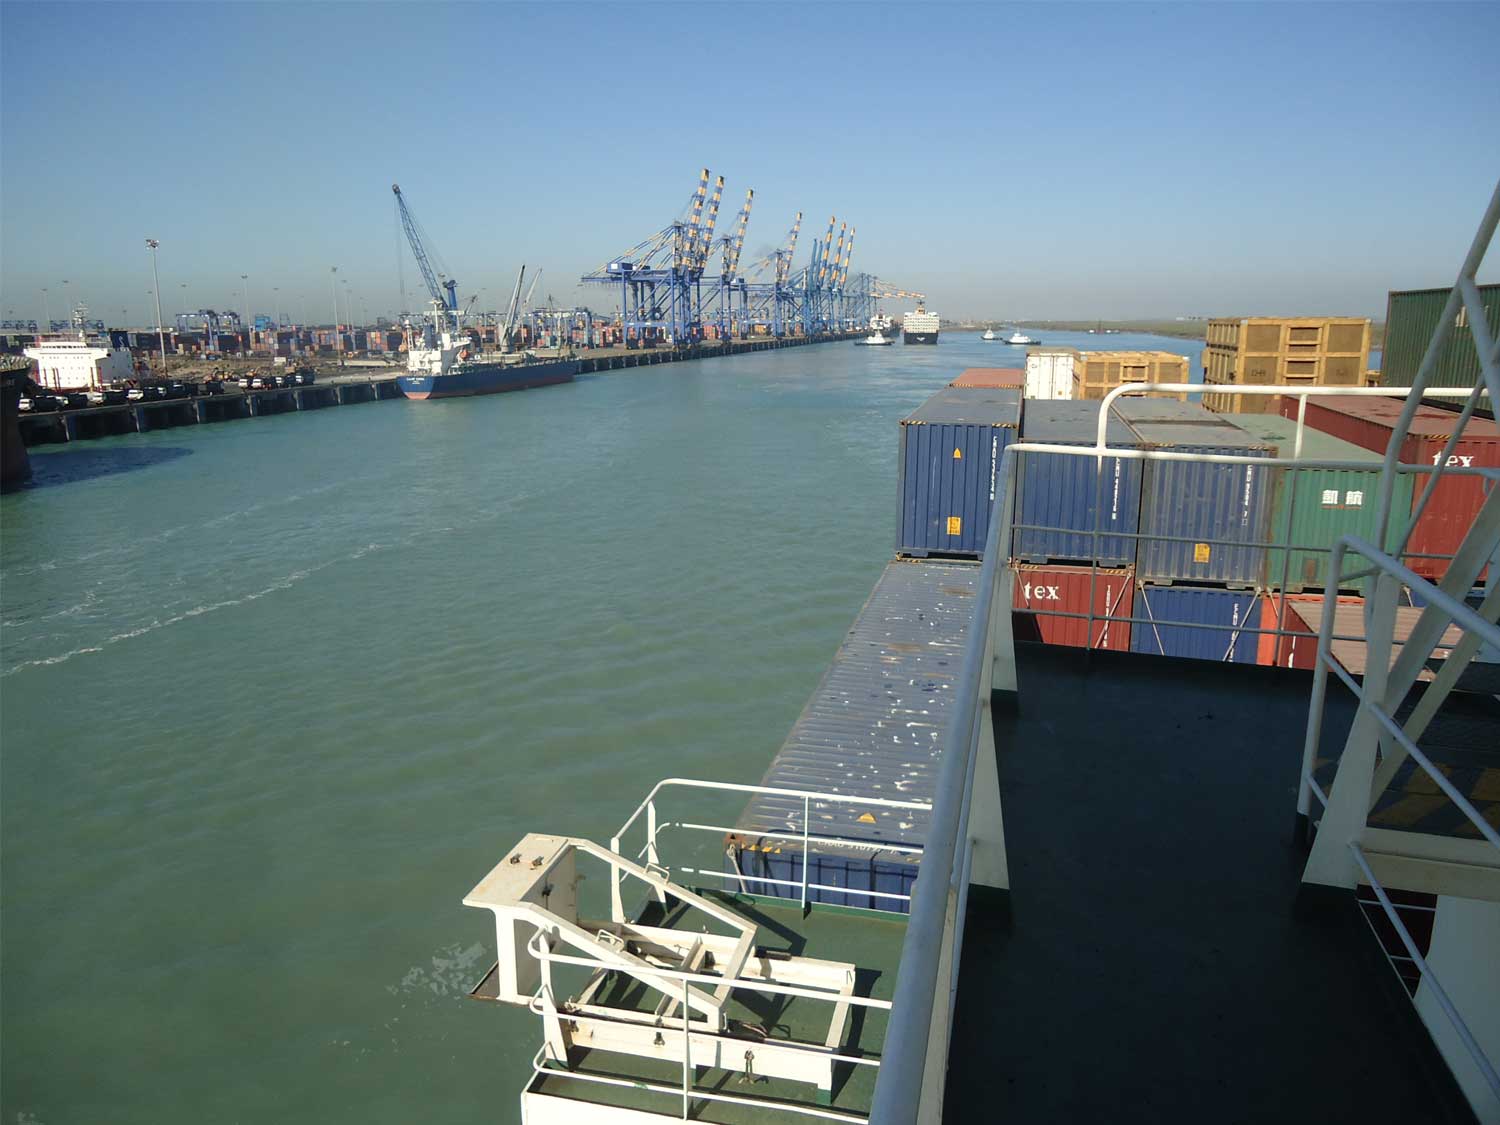
Nhava Sheva

India’s changing shipping networks add pressure to US supply chains

Congestion across South Asia's container shipping network is increasing costs and disrupting connections for US-bound cargo, while surging China–India demand and changing Middle East trade flows accelerate India's emergence as a regional transhipment hub.

India's expanding manufacturing economy and the disruption of established Middle East shipping routes are reshaping container movements across the Indian Ocean.

Freight rates from China to India have more than doubled since July, while congestion at Colombo, Nhava Sheva and Mundra is adding uncertainty to regional connections.

For US importers sourcing from India, these developments potentially create upstream cost pressures and increase the importance of reliable feeder services, transhipment connections and inland logistics.

At the same time, India's ports are handling growing volumes of cargo previously routed through Middle Eastern hubs, creating opportunities to strengthen the country's position in international shipping networks.

China–India demand drives freight rates higher

Strong demand for Chinese components, machinery and consumer goods is placing sustained pressure on container capacity into India.

Spot rates on China–India routes have more than doubled since July, with Shanghai–Nhava Sheva rates increasing approximately 20% since late August and Shanghai–Chennai rising around 25%.

The increases reflect growing import demand alongside the redeployment of vessels to higher-yielding east–west trades.

China remains India's largest trading partner, with Indian imports increasing 16% in the 2025–26 financial year. Growth accelerated further during the first five months of the current financial year, with import values rising approximately 27%.

Much of this demand comes from Indian manufacturers importing intermediate components, electronics and capital equipment to support domestic production.

Seasonal consumer demand and advance purchasing ahead of regulatory changes have added further pressure.

The cost increases extend across the wider intra-Asia market. Drewry's Intra-Asia Container Index remained 209% above year-earlier levels in early October, despite easing 1% during China's Golden Week holiday. Six consecutive weekly increases before the holiday underline the sustained cost pressure facing regional supply chains.

Carriers are responding with additional intra-Asia services, but expanding coverage has yet to offset the combined impact of demand and constrained vessel space.

Colombo congestion threatens India–US connections

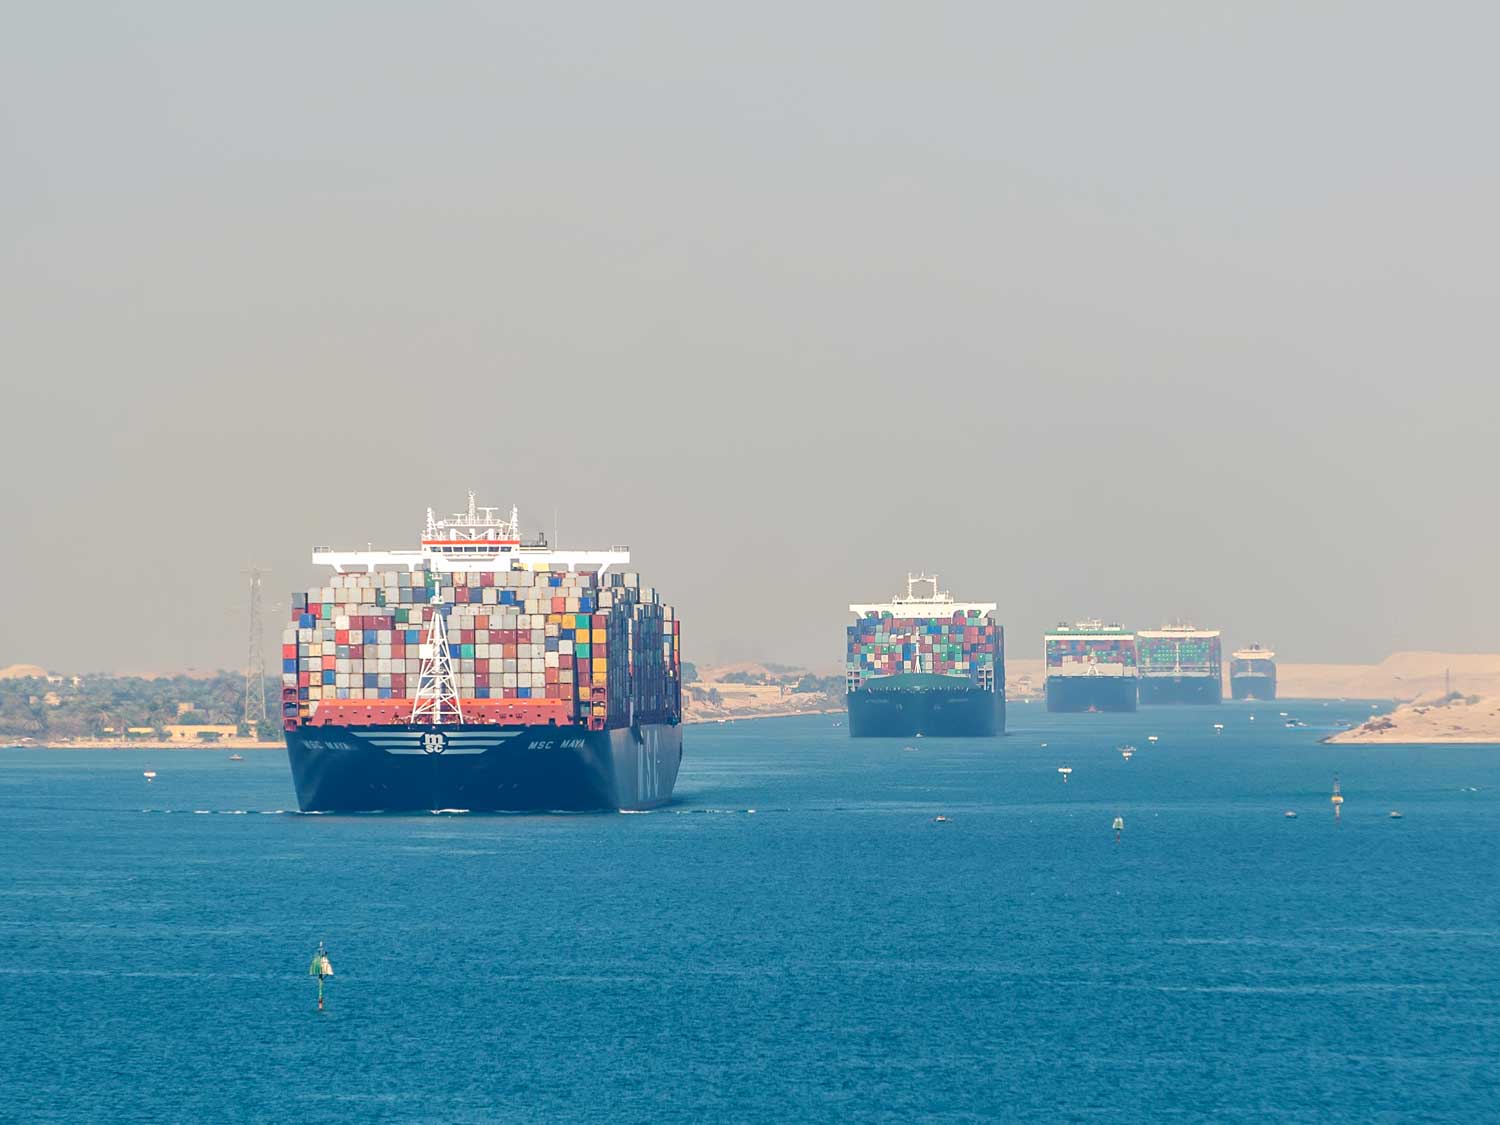
Sri Lanka's Colombo port has become an increasingly important transhipment hub as shipping lines divert cargo away from traditional Middle Eastern gateways.

The additional traffic is placing considerable pressure on terminal operations. Colombo's transhipment volumes increased 7.8% year on year in August and now account for more than 82% of total port throughput.

Terminal yard utilisation has exceeded 130%, with vessel delays of two to three days reported and container turnaround times extending beyond six days at some facilities.

For Indian exporters, particularly those shipping through southern gateways such as Chennai, Tuticorin and Cochin, the consequences extend beyond port delays.

Securing space on a mainline vessel does not guarantee that cargo will make its intended sailing. Feeder schedules, container availability, transhipment dwell times and mainline port calls must all align. When vessels omit Colombo to recover schedules, containers can miss connections even when space remains available on the onward service.

For US-bound cargo, these missed connections can extend transit times, increase storage and handling costs, and disrupt delivery schedules.

Pressure is also evident at other regional transhipment hubs. While freight rates from China to several Asian destinations eased during Golden Week, rates to Singapore and Tanjung Pelepas increased 2%, reflecting uneven conditions across regional shipping corridors.

Congestion at India's Nhava Sheva and Mundra ports adds another layer of uncertainty, making coordination across the complete transport chain increasingly important.

India emerges as an alternative regional hub

While congestion is creating immediate operational challenges, changing shipping patterns are also opening longer-term opportunities for Indian ports.

Middle East disruption has encouraged carriers to use India's west coast terminals to relay cargo previously handled through established Gulf hubs.

The shift now extends beyond Asia–Middle East shipments, with Indian ports increasingly handling Gulf-bound cargo originating in the US, Europe and Africa.

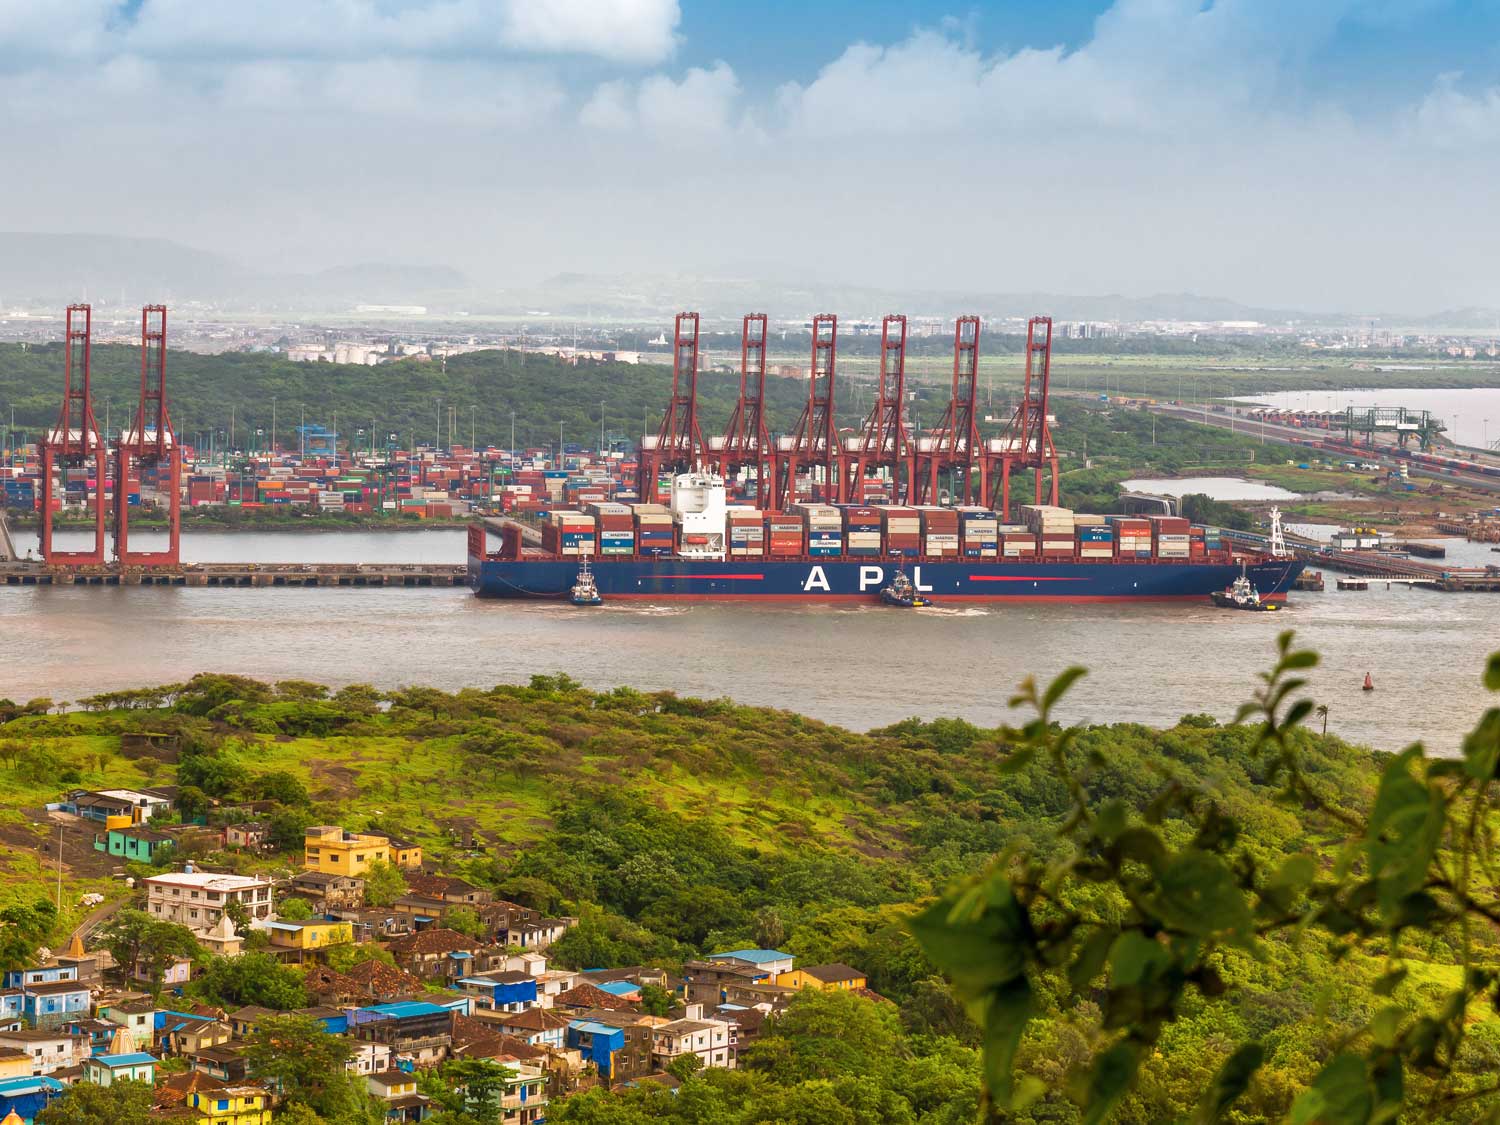
Nhava Sheva has become central to this development. The port handled more than 703,000 TEU of transhipment cargo between March and August, compared with approximately 513,000 TEU during the entire previous financial year.

At Mundra, transhipment volumes increased approximately 18% year on year between April and July.

These increases demonstrate how quickly carriers have adapted their networks, but the additional volumes are also contributing to terminal congestion and inland transport delays.

Both ports are developing additional storage and container-handling infrastructure to accommodate growing demand.

Regional networks are also being reconfigured. Four Asian carriers are removing Singapore calls from their joint China–India service, illustrating how shipping lines are reassessing established port rotations and connections.

Other gateways, including India's Vizhinjam and Sri Lanka's Hambantota, are attracting interest as carriers seek alternative transhipment options.

India's ability to retain this additional business will depend on whether its ports can deliver competitive costs, reliable feeder connections and consistent operational performance once Middle Eastern shipping patterns stabilise.

Connecting India and the USA with greater control

For US importers, the interaction between rising upstream costs, port congestion and changing shipping networks makes supply-chain planning increasingly complex.

China–India transport costs can affect Indian manufacturers before finished goods begin their export journey, while missed transhipment connections introduce further delays and expense.

A shipment's reliability now depends as much on feeder connections, terminal conditions and inland coordination as it does on securing mainline vessel space.

As India becomes an increasingly important sourcing and manufacturing partner for US businesses, effective coordination between origin and destination markets is essential.

Metro India and Metro USA provide connected expertise at both ends of this developing trade corridor, combining local market intelligence, carrier relationships and international freight capabilities to identify practical routing and transport options.

From managing origin arrangements and assessing alternative gateways to coordinating US imports and inland delivery, Metro helps customers maintain visibility and control across the complete supply chain.

Contact Metro UK, India or USA to review your shipping requirements, identify potential cost and transit-time risks, and build more reliable connections between India and the United States.
double stack container train

India export surge puts pressure on inland networks

India’s export surge is tightening ocean capacity, creating equipment shortages and increasing pressure on the inland road and rail networks that support its container gateways.

Premier carrier sailings from West India, including Nhava Sheva and Mundra, remained largely sold out through September on key trades, with market conditions expected to stay firm as exporters compete for available capacity.

The pressure is particularly evident at JNPA, where exporters are reporting growing difficulties securing empty containers. Forty-foot equipment is proving especially scarce, while shortages have also been reported at inland container depots (ICDs) across northern India.

The result is a supply chain challenge extending well beyond ocean freight availability.

Record exports tighten the equipment cycle

JNPA handled a record 832,000 TEU in August, rising approximately 12% month on month and 20% year on year.

More unusually, export containers exceeded imports during the month. India traditionally operates as a container-deficit market and relies heavily on repositioned equipment and boxes arriving from the Far East to replenish stocks.

Stronger exports are therefore consuming available equipment faster, while disrupted vessel schedules are making it harder for shipping lines to return empty containers to the locations where exporters need them.

Freight stations around JNPA have reported vehicles waiting in long queues at container yards without being able to collect equipment. Similar problems are emerging inland, with difficulties securing empty boxes reported at several northern Indian ICDs.

With Indian exporters traditionally increasing shipments during the January-March final fiscal quarter to meet annual targets, equipment positioning and advance planning could become increasingly important over the coming months.

Port performance shifts attention inland

The pressure also highlights a broader issue facing India's rapidly expanding container trade, because moving a box through a port efficiently is only one part of the journey.

Around 20,000 TEU leave JNPA by road each day, compared with approximately 2,000 TEU by rail. As port throughput increases, that imbalance places additional pressure on highways, container freight stations and other supporting infrastructure around the Mumbai region.

Earlier disruption caused by trailer-driver shortages demonstrated how quickly the land-side network can become constrained, slowing container movements between terminals and CFS facilities even when quayside operations continue normally.

Mundra has faced its own challenges. Container train operators reported significant congestion earlier this year, including more than 16,000 TEU awaiting movement and a rail pipeline exceeding 60 trains at one stage.

More recent disruption affecting empty-container yards has reinforced the importance of looking at the complete land-side operation when planning Indian shipments.

Rail investment and demand is growing

The completion of the Western Dedicated Freight Corridor (DFC) connection to JNPA in September represents an important development.

The 1,506km corridor connects the Mumbai gateway with northern India's major industrial and logistics regions, allowing freight trains to bypass much of the conventional passenger railway network.

Together with the Eastern DFC, India now has almost 2,850km of dedicated freight railway. However, demand is building rapidly.

The two corridors averaged around 438 trains a day in August against nominal capacity of 480, representing approximately 91% utilisation. The Western corridor was operating at around 88%, while the Eastern corridor was approaching 95%.

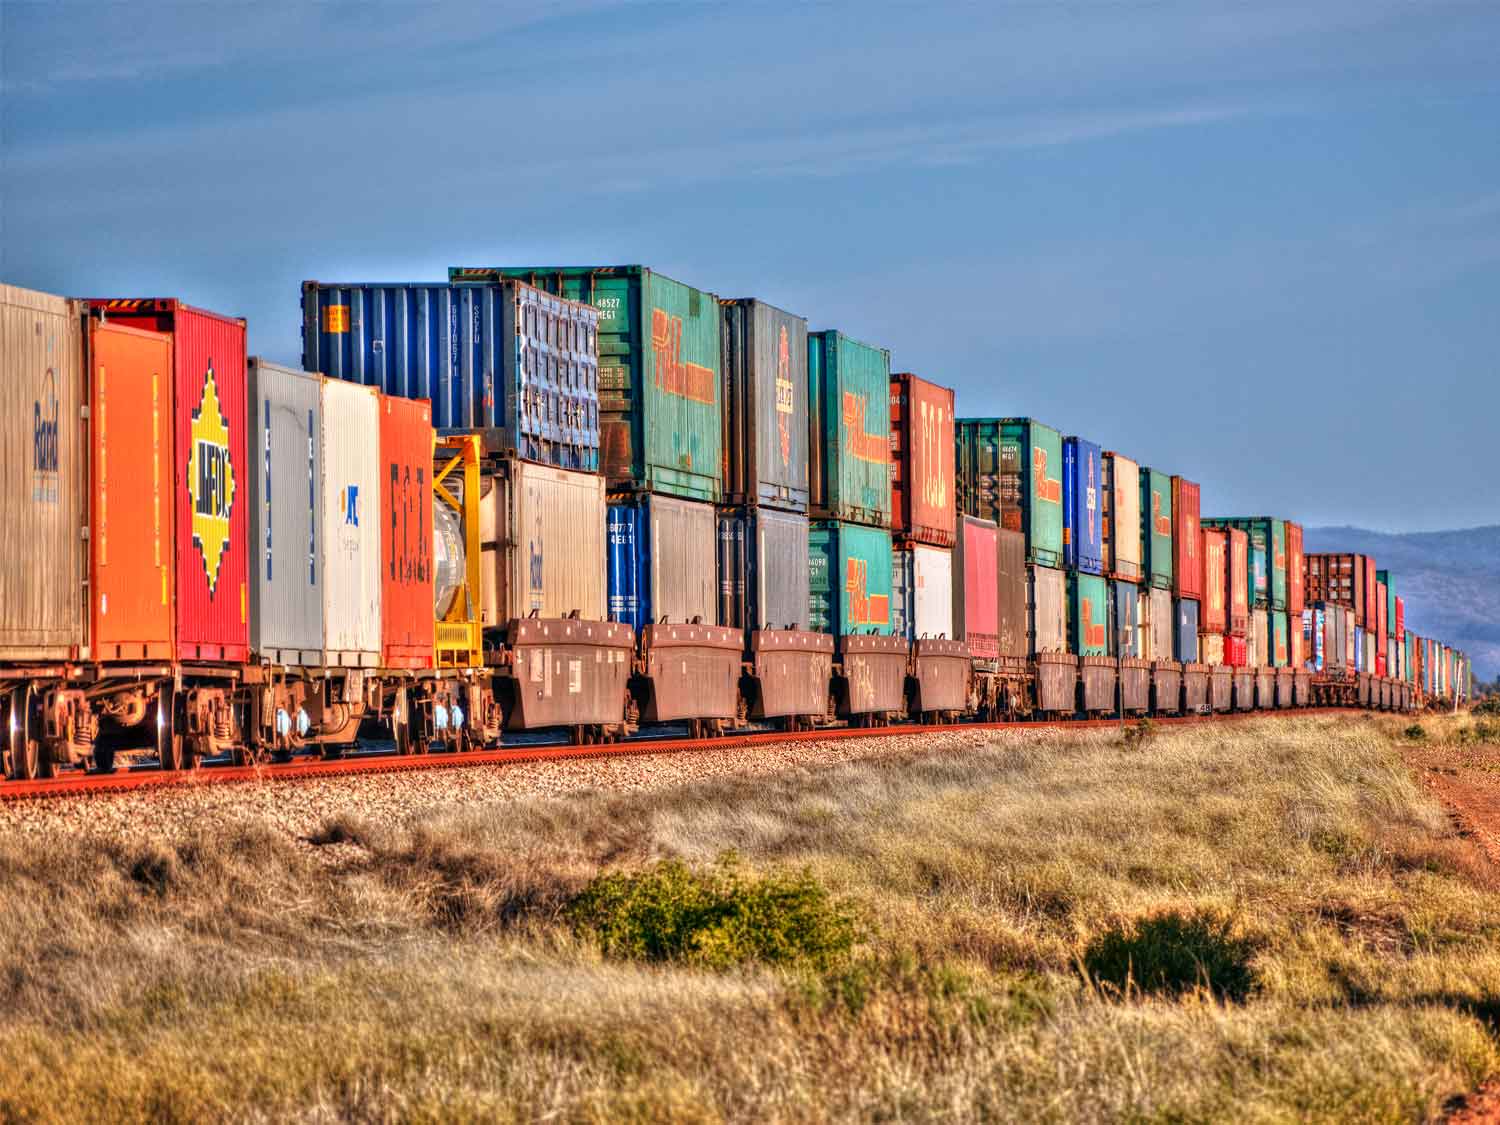
Double-stack and longer trains provide additional throughput potential, but the figures illustrate how quickly India's expanding trade is absorbing new infrastructure.

Meanwhile, other gateways are working to increase rail's share of inland movements. Chennai has restored its container rail connection with ICD Sanathnagar in Hyderabad and is exploring further inland services, potentially providing shippers with additional gateway and routing choices.

India movements require end-to-end planning

India's expanding ports and dedicated freight corridors are transforming the country's logistics infrastructure, but the current export surge demonstrates that capacity cannot be considered in isolation.

Sold-out sailings, shortages of export equipment, pressure at container yards, busy inland terminals and congested road connections can all influence whether cargo reaches its vessel as planned.

For importers and exporters, that increases the value of booking early, maintaining visibility of equipment and inland conditions and considering alternative gateways, routings and consolidation options where appropriate.

Metro India: local reach, global options

Metro's extensive footprint across India connects customers with the country's principal ports, ICDs, manufacturing regions and logistics centres, supported by established global carrier relationships and an international freight network.

Our local teams combine ocean and air freight, consolidation and inland transport capabilities to manage the complete movement. When capacity, equipment availability or congestion affects established supply chains, we can assess alternative carriers, gateways, routings, modes and consolidation options to help keep cargo moving.

If you have shipments moving to, from or across India, talk to Metro about current conditions and the options for protecting your upcoming movements.

Mundra Port

Container trade stays strong as disruption reshapes east–west markets

Global container trade is proving remarkably resilient, but record volumes mask a more complicated picture across the major east–west trades. Congestion, blank sailings and inland constraints are increasingly determining the conditions shippers experience.

July set a new monthly record for global container shipping, with 17.3 million TEU moved worldwide. Volumes were 4.5% higher than July 2025 and are running 5.1% ahead year to date.

That underlying strength matters. Despite geopolitical disruption, changing tariffs and widespread port delays, international containerised trade continues to grow.

But demand alone does not explain current freight conditions. Carrier capacity management, severe congestion at Asian ports and pressure on destination transport networks are creating increasingly different conditions by trade lane.

East–west markets move apart

The clearest divergence is between Asia–Europe and the transpacific.

Asia–Europe spot rates have continued to soften, with Shanghai–Rotterdam falling another 2% and Shanghai–Genoa 3% in the latest weekly data. The traditional peak appears to have passed, although congestion and blank sailings are preventing a more rapid correction.

Across the Pacific, the picture is very different. Transpacific demand strengthened as the US peak season extended later than initially expected, with west coast volumes rising 9% week on week in early September and east coast volumes increasing 3%.

Rates have consequently remained firm. Shanghai–Los Angeles increased another 2% in the latest week and Shanghai–New York 1%, following larger gains the previous week.

However, demand is only part of the explanation. Carriers are becoming increasingly active in managing available space through blank sailings, vessel rotations and capacity deployment as China’s Golden Week approaches.

Across the major east–west trades, around 11% of scheduled sailings between mid-September and mid-October are currently expected to be cancelled. More than half of those cancellations are concentrated on the eastbound transpacific, with a further third affecting Asia–North Europe and Mediterranean services.

The pace of change is significant. Announced blank sailings for the four weeks leading into Golden Week jumped almost 56% in just one week, and further cancellations remain possible as carriers adjust networks around the Chinese holiday.

The overall level remains manageable, with almost nine in ten scheduled sailings still expected to operate. But the acceleration in cancellations points to a more active phase of capacity management.

For shippers, softer demand will therefore not necessarily translate directly into lower rates or easier access to space. How aggressively carriers remove capacity before Golden Week and how quickly demand returns afterwards could determine the balance between available space and pricing through October.

Congestion is moving through the network

Capacity management is only one part of the east–west picture. Four successive typhoons have left major Chinese ports working through substantial backlogs.

Between early July and late August, almost 5.8 million TEU of vessel capacity arrived more than seven days late at Chinese ports, which is around three times the level recorded before the storms.

The impact on schedule reliability has been dramatic. According to figures from Sea-Intelligence, global reliability fell over 6% in July to 56.4%, its sharpest monthly deterioration in more than five years, while late vessels were arriving an average of over six days behind schedule.

Conditions became particularly challenging on east–west services during the typhoon period. Asia–Europe on-time performance fell to around 10%, while Asia–North America dropped to 23%.

Although congestion is gradually easing, the network has yet to recover fully. The combination of existing backlogs, the pre-Golden Week export push and subsequent factory closures could prolong disruption into October, with bunched vessel arrivals then feeding through to European and North American ports.

That is particularly relevant in the US, where pressure is already building beyond the quayside.

The National Drayage Spot Market Index is 8.2% higher year on year as driver availability, equipment constraints, terminal turn times and appointment availability tighten the market.

Import containers are waiting six to seven days on average for inland transport at some locations and up to 14 days at individual terminals. Pressure has been reported around Los Angeles/Long Beach, Houston, Chicago, Memphis, Savannah and other inland gateways.

For US importers, securing ocean space is therefore only one part of the challenge. Drayage and inland capacity need to be planned earlier, particularly when disrupted schedules result in several vessels and large volumes of cargo arriving within a compressed period.

India disruption continues beyond Mundra strike

The end of the 13-day dispute affecting empty container yards at Mundra has not brought an immediate return to normal operations.

The strike officially ended on 10 September, but Metro’s team in India continues to report around 5,000 containers delayed each day, with empty container flows particularly affected.

The scale of Mundra makes those continuing delays significant. The port accounts for around 35% of India’s container trade, so disruption can quickly affect equipment availability, exports and wider regional supply chains.

The situation also highlights India’s growing importance within international sourcing strategies as businesses diversify their supply chains and increase manufacturing and procurement activity across the subcontinent.

Metro India continues to scale strategically in response. The business is expanding across seven locations, creating a stronger platform for sourcing, consolidation, origin management and exports across the Indian subcontinent.

Overall, ocean markets remains stronger and more complicated than headline rate movements suggest. Global container volumes are setting records, but where carriers deploy capacity, how quickly Asian ports clear backlogs and whether inland networks can absorb arriving cargo will shape conditions through Golden Week and into October.

We may return to examine these developing themes in more detail, as the impact of Golden Week becomes clearer.

Metro combines global ocean freight buying power with local expertise across key origin and destination markets, including our expanding operation in India and established US network. We monitor capacity, blank sailings, port conditions, equipment availability and inland constraints throughout the journey, giving customers the intelligence and routing options to act before disruption reaches their supply chain.

Image: Adapted from The port of Mundra in Gujarat by Felix Dance, via Wikimedia Commons, CC BY 2.0.

India industrial revolution 1440x1080 1

India’s sourcing growth creates pressure at both ends of the supply chain

UK businesses sourcing from India face rising logistics costs before and after production, as more expensive Asian imports combine with tight westbound capacity and strong India–Europe demand.

India continues to strengthen its position as a manufacturing and sourcing alternative for UK and European businesses. But the cost of moving goods through the supply chains supporting that growth is rising.

The pressure starts well before finished products leave India. Many manufacturers rely on machinery, components, chemicals, electronics and other inputs imported from China and neighbouring Asian markets. Freight costs on those inbound routes have risen sharply, increasing the cost base for Indian production.

At the same time, strong exports are tightening India–Europe container capacity and pushing westbound freight costs higher.

For UK buyers, that creates a potential double freight squeeze, with logistics inflation entering the product cost upstream before another layer is added on the journey to Europe.

Asian imports into India become more expensive

The first pressure point is emerging on eastbound services into India.

During August, Shanghai–Nhava Sheva spot rates have almost doubled compared with July, while Shanghai–Chennai rates have increased by around 60%. Costs from other Asian origins, including Singapore, have also risen significantly.

Strong seasonal imports ahead of India's festival period are contributing to demand, while congestion at major Asian hubs has disrupted schedules and tightened available capacity.

For Indian importers, the impact extends beyond freight rates. Changing schedules and less predictable transit times make it harder to manage inbound inventory and maintain reliable production flows.

Higher freight feeds into manufacturing costs

The significance for UK buyers comes from China's deep integration into Indian manufacturing.

Rising transport costs for the raw materials and components feeding Indian factories may initially be absorbed through manufacturer margins. If elevated costs persist, however, some will inevitably feed into production costs and finished-product pricing.

That creates a supply-chain exposure that may be difficult to see when procurement decisions focus primarily on the factory price.

An Indian-made product can already contain significant logistics costs before it enters a container for its journey to the UK.

Strong exports tighten the westbound market

The second pressure point is India–Europe shipping.

Indian containerised exports to Europe reached an estimated 518,000 TEU during the first half of 2026, with stronger-than-expected demand creating a pronounced capacity squeeze.

Westbound rates increased again during August and are approaching levels last experienced around four years ago. Space has become increasingly difficult to secure, with some leading India–Europe services selling out several weeks ahead and additional spot capacity appearing only as carriers release allocations.

The problem is not simply growing demand. Available capacity has struggled to keep pace.

Blank sailings, congestion and rolled cargo at Nhava Sheva and Mundra are reducing effective space, while some capacity has been redirected towards growing Latin American flows using Indian ports for transhipment.

For cargo owners, guaranteed space can therefore command a premium, while less flexible shipments face greater rollover and delay risks.

Look beyond the supplier price

India's manufacturing scale and expanding trade relationships continue to make it an important sourcing market. But the changing freight environment reinforces the need to assess the complete landed cost of sourcing there.

A product assembled using Chinese or other Asian components may now carry substantially higher inbound logistics costs. Moving the finished goods from India to the UK then adds a second layer of freight inflation.

For lower-margin or freight-intensive products in particular, those combined costs could materially affect sourcing economics.

Timing matters too. With strong westbound bookings and constrained capacity, waiting for cheaper freight could leave importers competing for even tighter space.

Businesses can reduce that exposure by understanding upstream supply flows, consolidating shipments where appropriate and planning westbound capacity earlier.

Manage the whole supply chain, not just the final leg

The growing relationship between Chinese inputs, Indian manufacturing and European demand means these movements cannot always be managed effectively in isolation.

Metro can connect the complete Asia–India–UK supply chain, providing visibility from upstream suppliers through Indian production and onward to the UK. 

With extensive Indian based capabilities, global carrier relationships, consolidation and alternative routing options, we can identify where cost and capacity pressures are building and act before they reach your bottom line. EMAIL Andrew Smith, Metro’s Managing Director, to learn about protecting your landed cost from origin to destination.