ships at anchor

Middle East Conflict Is Rewriting the Airfreight Peak

Airfreight has always played a dual role in supply chains, providing a reliable core mode for some flows and a pressure‑relief valve when ocean networks clog up. 

The current Middle East crisis has upended that safety‑valve function; because instead of a short, sharp bottleneck, the market has shifted into a higher‑cost, more volatile place, that is already reshaping the 2026 peak season.

The initial fear was that conflict around the Gulf would trigger a sudden collapse in air capacity and an uncontrollable spike in jet fuel costs. That fearful initial phase has now passed, but pricing has not returned to pre‑crisis norms. Freight indices show global air rates holding well above early‑2026 levels, with some Asia–Europe spot rates doubling by April and still sitting nearly 75% above pre-war levels.

Fuel surcharges are no longer climbing week by week, but they remain dramatically higher than at the start of the year. The air cargo market is not spiralling upward, but it has clearly found a new, elevated pricing floor.

Capacity returns, but on new terms

Freighter lift grew around 3% month‑on‑month in April, reversing earlier declines, although week‑on‑week growth has slowed as airlines add capacity cautiously. Gulf carriers have been rebuilding their schedules, with strong month‑on‑month growth on Asia–Middle East and Europe–Middle East lanes, and major integrators have restored intercontinental flights into Bahrain, Dubai and other Gulf hubs from Europe and Asia.

Regional airspace is open again, albeit with corridors, pre‑approvals and routing constraints. Network operators have re‑established connections that link Europe, Asia and Africa through the Middle East, and are gradually extending services deeper into the region. Backup hubs in places such as Riyadh and Muscat remain in use while the security picture stabilises, but some carriers have also found alternative “mid‑points” in India and South‑East Asia to recover Asia–Europe capacity.

Other operators remain more cautious. Some European freighter airlines are still avoiding most Middle East stops, citing airspace and security concerns, and are waiting on further guidance from aviation security authorities before fully reopening networks. Major Asian carriers have delayed the resumption of certain passenger and freighter services into Riyadh and Dubai, even as they add freighter capacity into Bangkok, Vietnam and other South‑East Asian gateways.

Recent rate data shows some easing out of major Asian hubs and on Europe–US and Europe–Gulf routes, but pricing remains historically high. Outbound Heathrow rates, for example, are still more than 40% above last year. Refineries in Europe, the US and West Africa have shifted output towards aviation fuel, airlines have rerouted networks and trimmed weaker services, and capacity is being deployed with unusual discipline. Together, these factors are preventing a rapid collapse in pricing.

What this means for the “traditional” air peak

In a normal year, shippers would expect a relatively quiet summer followed by a steady build‑up into the late‑Q3/Q4 peak. Middle East disruption has scrambled that pattern in three important ways:

  • The market has already experienced “mini peaks” in Q2, as conflict‑related diversions and fuel shocks pushed rates to levels normally associated with peak season.
  • With airspace constraints, elevated fuel costs and tight capacity discipline, the system has less slack than usual. The ability to “pivot to air” from ocean at short notice is weaker.
  • Geopolitical risk now appears to be permanently repriced into airfreight. Even if the Gulf situation stabilises, fuel surcharges and base rates are likely to remain volatile, and the industry is planning around that assumption with more frequent surcharge adjustments.

For UK shippers, the implication is that 2026’s airfreight peak is less about one clear season and more about a longer period of heightened risk, with short, unpredictable demand spikes layered onto an already expensive base. Treating the whole second half of the year as potentially “peak‑like”, budgeting for higher air costs, and pre‑booking critical flows on key lanes will be essential to avoid being caught out.

Metro works closely with airlines and partners to secure capacity, identify alternative routings and maintain reliability in a disrupted market. If your supply chain depends on airfreight, EMAIL our Managing Director, Andrew Smith, to protect space, manage cost exposure and keep your cargo moving.
refinery

Fuel shocks across ocean, air and road freight

With the Strait of Hormuz effectively closed, crude oil can still exist within the region, but refined products, which includes marine fuel, jet fuel and diesel, can no longer move freely to key consumption markets, which has triggered a sharp divergence in pricing and availability across all modes. 

For shippers, this creates a higher cost floor, as transport fuels are no longer moving in line with crude. Marine bunker, jet fuel and diesel each have their own supply chains and crack spreads (the margin between crude and refined products), and are now behaving independently of Brent. This is driving bunker-led cost pressure in ocean, jet fuel-driven inflation in air, and diesel-driven cost escalation in road. 

Ocean freight: bunker costs reset the pricing floor

In ocean freight, bunker fuel has become the dominant cost driver. Asian fuel hubs, particularly Singapore, are experiencing significant pressure as rerouted vessels increase demand while supply remains constrained.

This has created a disconnect between traditional pricing mechanisms and real-time costs. 

Emergency bunker surcharges are being applied across major trade lanes, while standard adjustment factors lag behind market conditions and may only catch up with current fuel inflation later in the year.

The result is a structurally higher cost base, with ocean rates now reflecting fuel volatility rather than underlying demand alone. 

Air freight: jet fuel shortage tightens capacity

Air freight is facing the most acute fuel-driven pressure. Gulf refineries, which typically supply jet fuel to Europe and Asia, are unable to export at normal levels, creating a shortage of refined product.

This has driven a sharp increase in jet fuel prices, with crack spreads widening dramatically from around $16 per barrel pre-crisis to approximately $100 in some regions. 

This regional price divergence means that Asia and Middle East jet fuel benchmarks sit substantially above North American levels, meaning that every kilo of freight uplifted is starting from a materially higher fuel cost base. 

As a result, airlines are adjusting networks, reducing marginal capacity and prioritising fuel efficiency, tightening available uplift and sustaining elevated airfreight rates.

Road freight: diesel inflation feeds through to transport costs

Road freight is also seeing significant cost pressure, with diesel prices rising independently of crude due to refinery constraints and regional supply dynamics.

Fuel accounts for roughly 30% of total truck operating costs, meaning sustained diesel inflation is already feeding through into pricing. 

At the same time, increased reliance on overland routes across the Middle East is adding further demand pressure, compounding both cost and capacity challenges.

What this means for shippers

  • Expect fuel-driven cost volatility across all modes
  • Plan for longer and less predictable transit times
  • Build flexibility into routing and inventory strategies
  • Monitor surcharge mechanisms

Fuel disruption, routing constraints and capacity pressure are now closely linked. Managing one without the others is no longer effective.

Metro works with customers to model alternative routes, balance mode selection and manage cost exposure in real time. If you are seeing rising costs, delays or uncertainty in your supply chain, EMAIL managing director, Andrew Smith, to secure the most effective solution for your cargo.

Hong Kong X ray costs and delay fears

Airfreight rates remain elevated with disruption likely to delay recovery

Airfreight markets have undergone a prolonged period of elevated pricing since the start of Middle East hostilities and despite softer demand in recent weeks spot rates have continued to rise sharply. 

Global spot rate indices are up by more than 35% year on year and have increased by over 40% since the onset of the Middle East crisis, highlighting the extent to which supply-side disruption, rather than demand, has been driving the market.

This reflects a structural shift, where fuel availability, routing complexity and network disruption are now setting the baseline for pricing.

Fuel supply constraints begin to tighten capacity further

The next phase of disruption is already emerging. The UK has taken delivery of the final shipments of jet fuel that transited the Strait of Hormuz before the conflict escalated, meaning supply constraints are now expected to intensify.

Jet fuel availability is becoming a defining factor in airline operations, with rising costs and limited supply forcing carriers to reassess schedules. Flight cancellations have already begun, and reinstating these services is not straightforward. Aircraft, crew availability, regulatory approvals and network coordination all create barriers to a rapid return of capacity.

As a result, even where demand softens, supply is tightening again, reinforcing upward pressure on rates.

Capacity recovery remains uneven and fragile

While global capacity has recovered from the initial shock, when supply fell by around 20% at the start of the crisis, it remains below previous levels and unevenly distributed.

Capacity from Middle East and South Asia origins is still significantly constrained, with reductions of around 20% year on year, limiting the availability of key transit routes. At the same time, global demand has softened, falling by approximately 8% year on year, but this has not yet translated into lower pricing.

This imbalance highlights a key market dynamic: capacity is returning, but not necessarily where it is needed, and operational constraints continue to limit how effectively it can be deployed.

Trade lane volatility reflects shifting network priorities

Rate movements are now highly variable by trade lane, reflecting how airlines are repositioning capacity.

From some origins, rates have increased by more than 50% year on year, while others have seen more moderate gains or even short-term declines. European outbound routes remain mixed, with strength on certain long-haul lanes offset by weaker demand elsewhere.

At the same time, airlines are redeploying aircraft to higher-yield routes rather than simply rebuilding pre-conflict networks, creating further imbalance across global capacity.

Recovery will take time, even under stable conditions

Even if conditions stabilise, a rapid return to normal is unlikely.

Airlines will be cautious about reinstating routes through the Middle East, given the fragility of the ceasefire and ongoing geopolitical risk. Airspace restrictions, insurance considerations and operational planning will all slow the recovery process.

Passenger networks, vital for critical belly-hold capacity, may also take time to rebuild, as demand for travel into the region recovers gradually. This will further constrain available cargo capacity.

Even with weaker volumes in some regions, rates are holding firm or increasing, and any downward correction is likely to be gradual rather than immediate.

Secure capacity in a constrained market

With fuel supply tightening, capacity uneven and recovery uncertain, airfreight is entering a period where access and planning matter more than ever.

Metro works closely with airlines and partners to secure capacity, identify alternative routings and maintain reliability in a disrupted market. If your supply chain depends on airfreight, EMAIL our Managing Director, Andrew Smith, to protect space, manage cost exposure and keep your cargo moving.
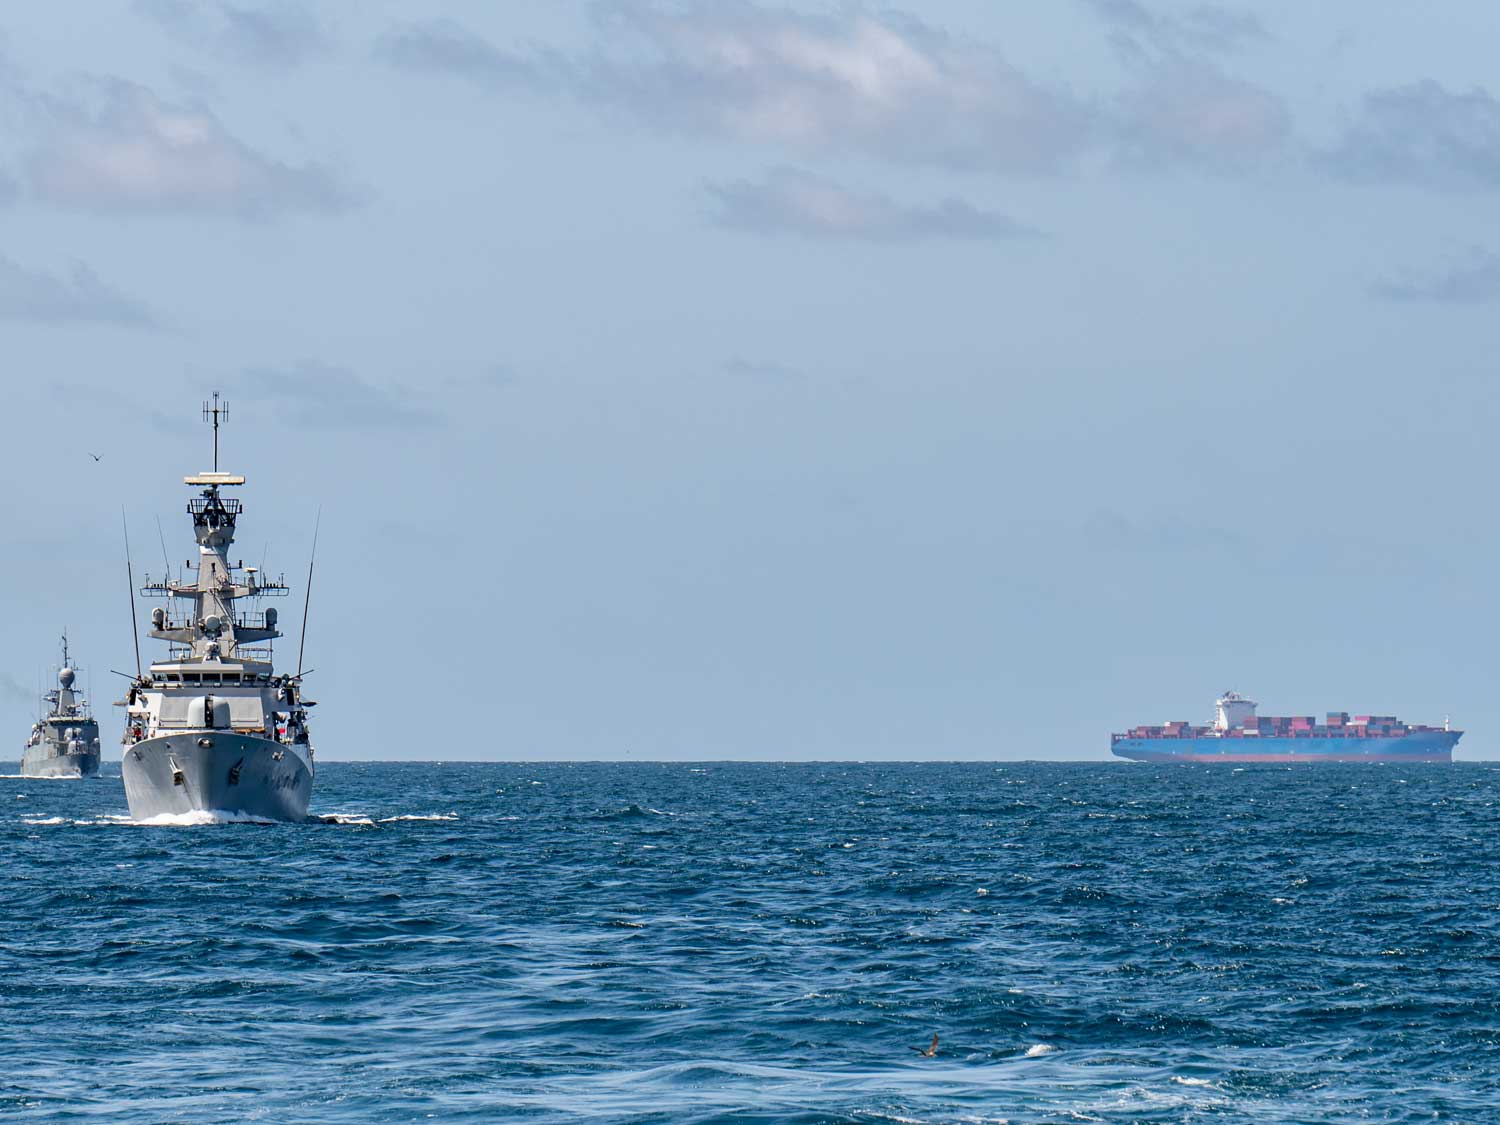
container ship and naval escort

Supply chain disruption continues despite US/Iran ceasefire

Global supply chains are operating in a more stable position than at the peak of the Iran war, but conditions remain far from normal. 

President Trump’s announcement of a ceasefire, tied to the opening of the Strait of Hormuz, has reduced immediate geopolitical tension. However, logistics networks are still dealing with the after-effects of six weeks of disruption across one of the world’s most critical trade corridors.

Shipping activity through the Strait has resumed in limited form, but not at levels that would support a full return to pre-conflict operations. Carriers, insurers and cargo owners continue to treat the region as high risk, and that caution is shaping how goods are moved globally.

A clear indicator is the sustained level of Gulf container diversions to alternative gateways due to risk or congestion. Weekly diversions have risen from under 2,000 to consistently above 9,000 since early March. The UAE still receives 42% of diverted cargo, while Saudi Arabia’s share has climbed from 4% to 24% in five weeks. The 6 April attack on Khawr Fakkan has also removed a key alternative hub, adding further pressure to the network.

Congestion and cost pressures extend beyond the Gulf

The impact of these diversions is now being felt well beyond the Middle East. As cargo is redirected through alternative routes, pressure is building at ports not designed to handle sustained increases in transhipment volumes.

Navi Mumbai transhipment volumes have surged more than 1,300%, while import dwell times peaked at 23 days and remain elevated at around 20 days. Transhipment dwell has also increased, reaching 11 days and continuing to rise.

These developments underline a broader point: while flows have not stopped, the network has become less efficient. Transit times are longer, routing is less direct, and the risk of delay has increased at multiple points along the supply chain.

Energy disruption remains a central factor. The Strait of Hormuz has been functionally constrained for several weeks, removing an estimated 7–10% of global oil supply once partial workarounds are considered. This is feeding directly into transport costs across ocean, air and inland networks, while also increasing volatility in fuel pricing.

Global economies face different but connected pressures

The IMF have issued their updated global economic outlooks, with global GDP expected to slow to 3.1% in 2026 and 3.2% in 2027, while UK growth for 2026 has slowed from 1.3% to 0.8%, reflecting reliance on imported energy and the wider inflationary effects of sustained disruption. 

As energy-driven inflation persists and interest rate cuts are delayed, businesses are seeing pressure on margins, reduced order volumes and tighter working capital, while influences procurement and inventory strategies.

In the United States, supply chains are tightening rather than slowing. The Logistics Manager’s Index rose to 65.7 in March, its highest level since May 2022, with transportation, warehousing and inventory costs all increasing. Diesel prices have risen by almost 50% since late February, pushing trucking fuel surcharges to their highest levels since 2022.

A key difference compared to previous disruptions is the lack of buffer in the system. Inventories are leaner and fleet capacity has already been reduced, leaving less room to absorb further shocks. This increases the risk of stock-outs or service disruption if conditions deteriorate.

Business response: cautious planning and greater resilience

Across sectors, businesses are taking a measured but cautious approach. The ceasefire has improved sentiment, but expectations remain grounded. One retail CEO described it as a positive step that should gradually improve logistics planning and route reliability, while warning that supply chains would take time to rebalance. Another business leader noted that while freight costs had already increased, the business had anticipated this and planned accordingly, although any sustained rise in oil prices would create further pressure.

There are also early signs of upstream impact. In manufacturing supply chains reliant on imported energy, lead times have extended by up to six weeks in some cases. Textile production is reported to be down by around 15–20%, indicating that disruption is beginning to affect output at source. These effects typically take time to filter through to finished goods, but they highlight the potential for delayed disruption later in the supply chain.

In response, businesses are shifting from efficiency towards resilience, with greater emphasis on flexibility in routing, supplier selection and inventory management.

Short-term outlook: stabilisation without normalisation

In the near term, the most likely scenario is continued stabilisation without a full return to normal conditions. Vessel backlogs have eased and airspace restrictions eased, with some capacity redeployed, but diversion levels remain high and alternative hubs are under pressure. The loss of key secondary ports and ongoing uncertainty around the Strait mean carriers are unlikely to revert quickly to previous routing patterns.

For supply chains, this translates into a more complex operating environment. Costs remain elevated, transit times are less predictable, and planning cycles need to account for ongoing disruption rather than a rapid recovery.

In an environment where stability cannot be assumed, the ability to adapt quickly is critical and the right logistics partner can make the difference between maintaining flow and losing control.

With critical market insights, flexible routing options and proactive supply chain management, Metro helps customers overcome the most challenging conditions. 

EMAIL our Managing Director Andy Smith.