Lloyds Market Matters

Metro CEO joins Lloyds Bank to examine the changing global trade outlook

Metro CEO Grant Liddell joined Lloyds Bank’s Markets Matter briefing to examine how geopolitical disruption, changing sourcing strategies and rising transport costs are reshaping global supply chains and why underlying trade remains surprisingly resilient.

The Lloyds Bank’s Markets Matter series brings together its economists and market specialists with business leaders to give corporate and commercial clients practical insight into the economic, financial and operational issues affecting their businesses.

For its latest briefing, Navigating Markets Beyond Monetary Policy, Grant joined Lloyds Bank specialists to bring a logistics perspective to a discussion spanning interest rates, inflation, energy prices, government finances and the wider risks facing UK businesses.

With freight costs among the channels through which geopolitical disruption and higher energy prices can feed into inflation, the discussion turned to what Metro is seeing across international supply chains and how businesses are responding.

Global trade is proving resilient

Global logistics provides an unusually immediate barometer of international trade, and Grant highlighted the contrast between the economic headlines and what is actually moving through supply chains.

Global container volumes reached a record level during July, while containerised trade continued to grow year on year. Intra-Asia and Asian export trades have been particularly strong, despite tariffs, geopolitical tensions and changing sourcing patterns. 

The picture is not uniform. European demand remains relatively subdued compared with the US, Far East and some emerging markets, while India is experiencing particularly strong growth.

That demand has consequences. Freight operates as a highly responsive market, with rates capable of rising or falling rapidly as available capacity moves out of balance with cargo demand. Grant highlighted dramatic increases on some Indian ocean and airfreight trades this year, while transpacific ocean rates have returned towards levels last experienced during the pandemic. 

Those increases do not stop with the freight invoice. Components and raw materials frequently cross borders several times before a finished product reaches its customer. Higher transport costs can therefore enter the production process at multiple stages, creating an indirect inflationary effect as well as increasing the final cost of distribution. 

From just in time to ‘just given time’

One of Grant’s most interesting observations concerned the way businesses are responding to disruption.

The highly optimised just-in-time model used across many manufacturing and industrial sectors has become much harder to maintain as Red Sea diversions, geopolitical conflict, closed airspace and port congestion extend and destabilise transit times.

Grant described the reality as increasingly becoming “just given time” with businesses adapting their inventory and production strategies to supply chains where predictable lead times can no longer always be assumed. 

That change is also accelerating interest in alternative sourcing locations. India is attracting manufacturing in sectors including technology and electronics, while Metro customers are increasingly considering production in the UK and Europe. North Africa is becoming more prominent and Turkey has attracted manufacturing across garments, automotive and engineering.

Some businesses had already begun reducing their dependence on China before the pandemic. Subsequent disruption has pushed resilience and diversification much higher up the agenda.

Yet this does not necessarily mean less international trade. Goods may travel shorter distances or move by truck rather than deep-sea container or airfreight, while rapidly expanding intra-Asian trade demonstrates how changing manufacturing footprints can create new freight flows rather than eliminate them. 

Reliability becomes the critical supply-chain risk

Asked what businesses should be considering as they plan for 2027, Grant put reliability high on the list.

Strong demand is combining with congested ports, delayed vessels, weather disruption and geopolitical uncertainty. The resulting challenge is not simply securing a competitive freight rate, but ensuring components reach production lines and finished products reach markets when required. 

That reinforces a theme running throughout the Lloyds discussion.

Higher freight and energy costs matter, but their wider economic impact depends partly on how businesses respond: whether costs are absorbed, reflected in pricing, influence wage decisions or become embedded in future contracts.

For supply-chain managers, the equivalent challenge is building enough flexibility into sourcing, inventory and transport strategies to withstand disruption without creating excessive cost.

Suez could change the equation again

There are also reasons why the freight outlook could change during 2027.

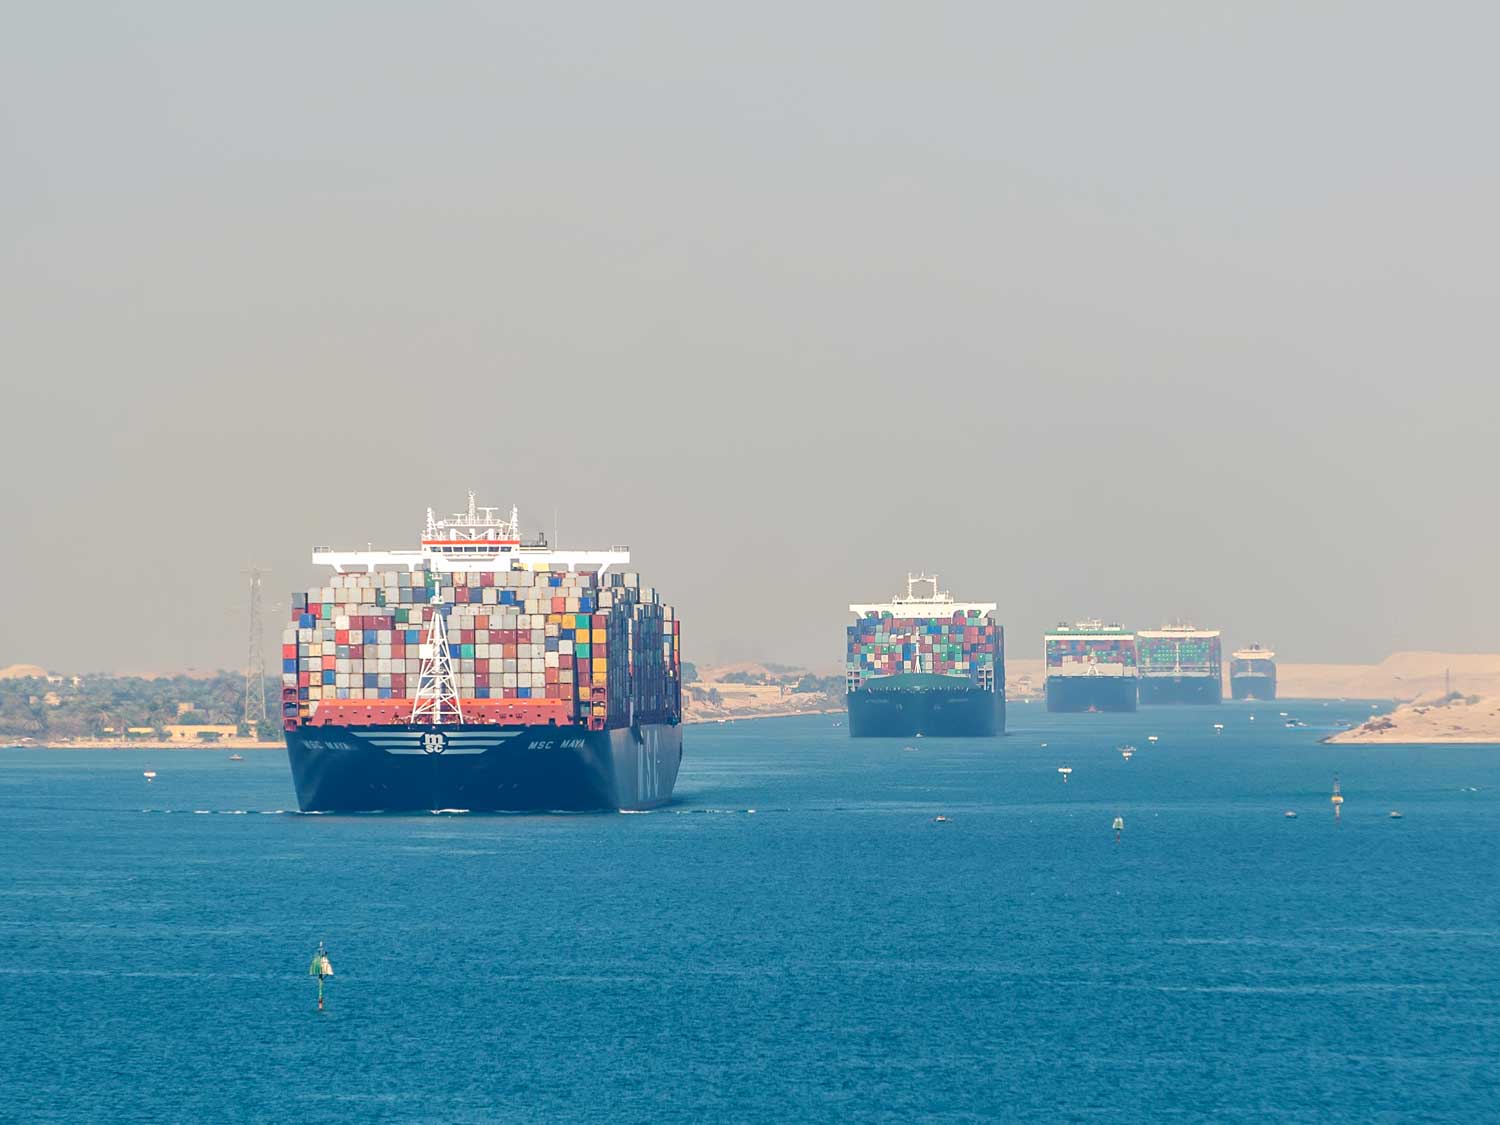
Grant highlighted the increasing use of the Red Sea and Suez route by carriers serving Asia, with several lines already using the route regularly.

A wider return would release effective vessel capacity because ships would no longer require the additional 15+ days associated with Cape of Good Hope diversions. That could improve supply and place downward pressure on freight rates. 

But the outlook remains complicated by energy prices, aviation fuel costs and continuing geopolitical risk.

Near-shoring can provide another layer of protection, but changing a manufacturing footprint is neither quick nor straightforward. Establishing new suppliers and supply chains can take months or years.

The result, as Grant characterised it, is a mixed picture for 2027, and while significant risks remain businesses are actively changing how and where they source, manufacture and move products to manage them. 

Turning global risk into practical supply-chain decisions

Perhaps the clearest message from the discussion was that geopolitical and economic uncertainty has not stopped global trade. Instead, it is changing its routes, costs and priorities.

With businesses already planning for 2027, the discussion provides useful context for understanding how economic and geopolitical risks could affect costs, sourcing and supply-chain decisions in the months ahead.

Click HERE to catch up with the full Lloyds Banking Group Markets Matter recording.
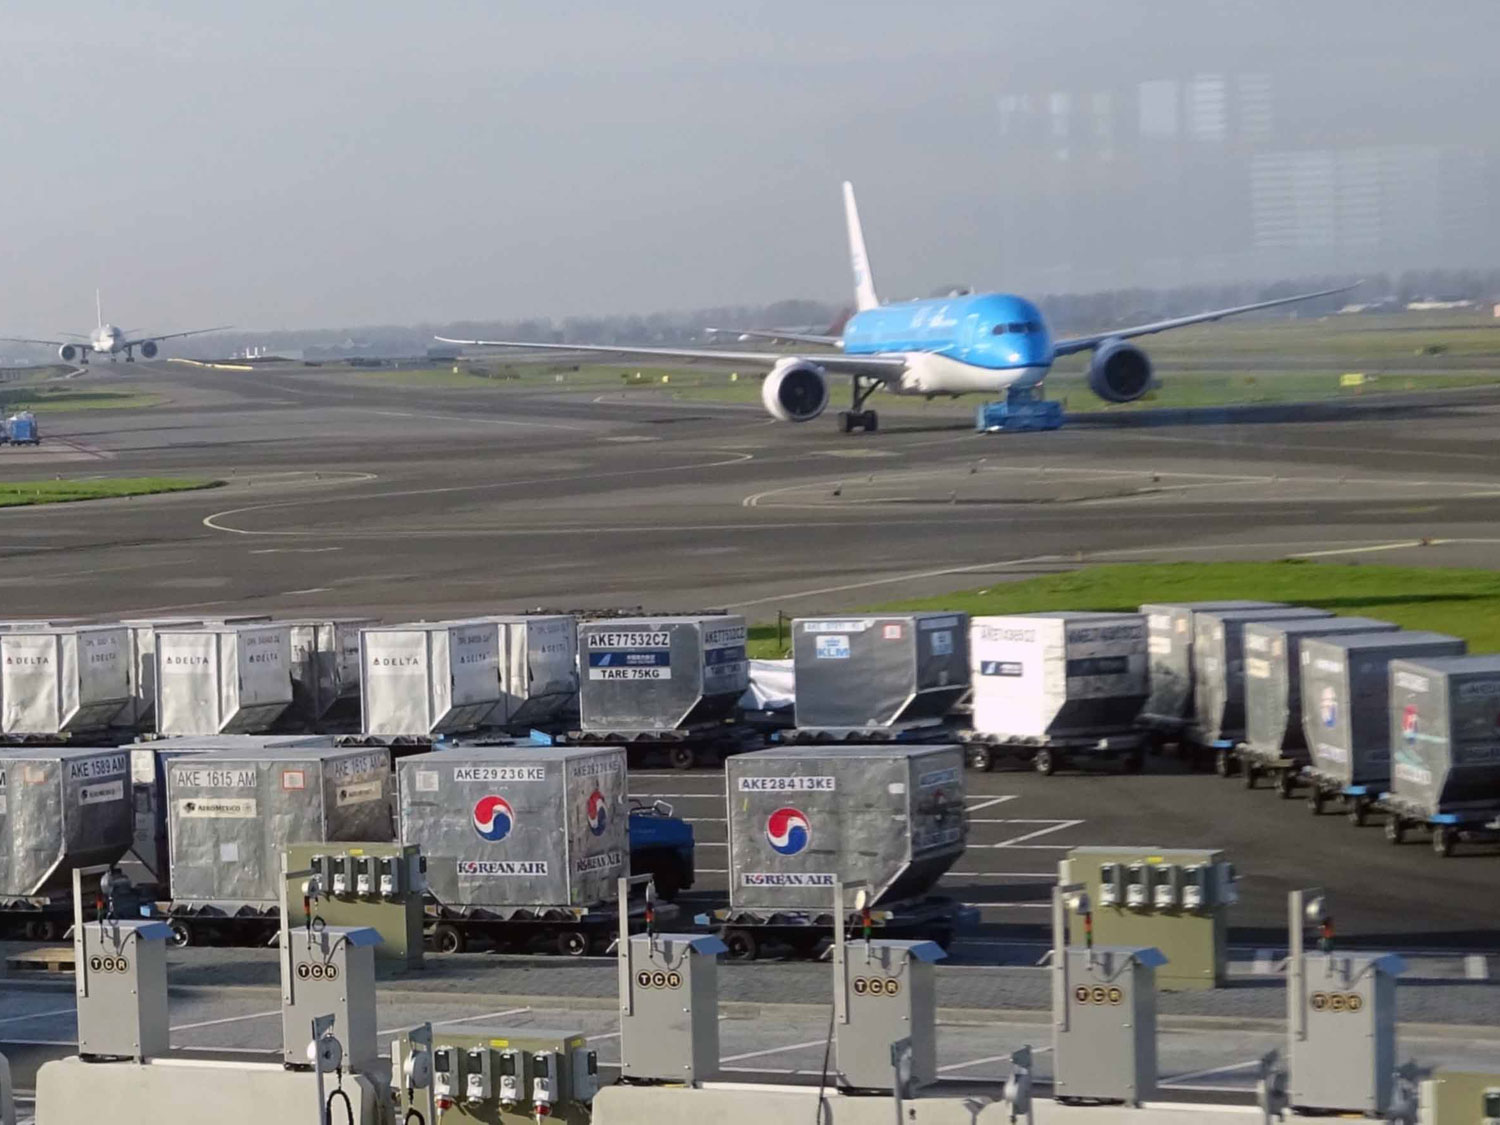
ULD on tarmac

Air freight market tightens ahead of autumn peak

Air freight enters the traditional peak-season build-up with a finely balanced market, as capacity reductions and resilient pricing create the potential for rapid tightening when Asian export demand accelerates.

The usual late-September surge may still be several weeks away, but UK importers have good reason to start planning now.

Asia–Europe demand softened during August, yet rates have shown little corresponding weakness. Airlines and freighter operators are adjusting capacity as cargo flows change, while higher fuel costs and stronger demand on alternative trade lanes are providing additional support.

That leaves limited spare capacity to absorb the traditional autumn increase – particularly if ocean freight disruption pushes urgent shipments towards air.

Softer demand is not delivering cheaper capacity

Asia Pacific–Europe chargeable weight fell 5% week on week and 14% year on year in week 33, continuing the softer trend evident since late June.

Changing e-commerce flows have contributed to the decline. China–Europe volumes were 8% lower year on year in week 32, while Hong Kong–Europe traffic fell 29%.

Despite that weakness, Asia Pacific–Europe spot rates remained flat in week 33 after rising 1% the previous week. China was particularly resilient, recording a 6% increase despite lower volumes.

The explanation lies partly on the supply side. Asia Pacific capacity contracted 2% in week 33 after declining 1% the previous week, limiting the downward pressure on rates.

Freighter deployment may tighten the market further. Stronger transpacific demand provides operators with an incentive to allocate aircraft towards the US, potentially reducing the capacity available for European cargo as peak season approaches.

China shows how quickly conditions can change

Recent disruption around Shanghai illustrates the vulnerability of available capacity.

Typhoon Dolphin caused more than 1,000 flight cancellations and contributed to an 8% weekly reduction in chargeable weight from Shanghai, while Shanghai–Europe volumes fell 7%.

The immediate disruption has eased, but severe weather and congestion across Chinese ocean gateways remain relevant to the air freight outlook. When container schedules become unreliable, urgent and time-sensitive cargo can quickly switch from ocean to air.

Even a relatively small modal shift can have a disproportionate effect on air freight capacity and pricing.

Golden Week could mark the turning point

The next significant test comes around China's Golden Week.

Factories traditionally accelerate production before the holiday, followed by another increase as operations resume and backlogs clear. October also brings the start of the main pre-Christmas replenishment cycle.

Demand then typically intensifies through November as retailers and e-commerce businesses prepare for Black Friday, Cyber Monday and Christmas.

This year, however, the market enters that period with capacity already responding closely to demand. That could make the transition from today's relatively balanced conditions to a tighter market particularly rapid.

Fuel costs, severe weather, changing freighter deployment and disruption to ocean services provide additional variables.

The opportunity is before the peak

For shippers, softer August volumes could offer a useful planning window rather than a reason to wait for lower rates.

Businesses with visibility of their autumn requirements can secure allocations earlier, consider alternative origins and gateways, and decide which shipments genuinely require premium air services.

Booking ahead of cargo-ready dates will become increasingly important as demand builds, particularly from China and other major Asian export markets. Flexible routing can also provide valuable alternatives when individual gateways or direct services tighten.

The key consideration is not simply today's air freight rate, but the availability of the right capacity when cargo needs to move.

Metro combines extensive Asian origin coverage with global airline relationships, flexible routing and multiple service levels to keep UK supply chains moving when peak-season capacity tightens. 

Share your autumn forecasts with Metro now and we can secure the capacity, routing and service strategy your cargo needs before the peak takes hold.

EMAIL Andrew Smith, Metro’s Managing Director.

India industrial revolution 1440x1080 1

India’s sourcing growth creates pressure at both ends of the supply chain

UK businesses sourcing from India face rising logistics costs before and after production, as more expensive Asian imports combine with tight westbound capacity and strong India–Europe demand.

India continues to strengthen its position as a manufacturing and sourcing alternative for UK and European businesses. But the cost of moving goods through the supply chains supporting that growth is rising.

The pressure starts well before finished products leave India. Many manufacturers rely on machinery, components, chemicals, electronics and other inputs imported from China and neighbouring Asian markets. Freight costs on those inbound routes have risen sharply, increasing the cost base for Indian production.

At the same time, strong exports are tightening India–Europe container capacity and pushing westbound freight costs higher.

For UK buyers, that creates a potential double freight squeeze, with logistics inflation entering the product cost upstream before another layer is added on the journey to Europe.

Asian imports into India become more expensive

The first pressure point is emerging on eastbound services into India.

During August, Shanghai–Nhava Sheva spot rates have almost doubled compared with July, while Shanghai–Chennai rates have increased by around 60%. Costs from other Asian origins, including Singapore, have also risen significantly.

Strong seasonal imports ahead of India's festival period are contributing to demand, while congestion at major Asian hubs has disrupted schedules and tightened available capacity.

For Indian importers, the impact extends beyond freight rates. Changing schedules and less predictable transit times make it harder to manage inbound inventory and maintain reliable production flows.

Higher freight feeds into manufacturing costs

The significance for UK buyers comes from China's deep integration into Indian manufacturing.

Rising transport costs for the raw materials and components feeding Indian factories may initially be absorbed through manufacturer margins. If elevated costs persist, however, some will inevitably feed into production costs and finished-product pricing.

That creates a supply-chain exposure that may be difficult to see when procurement decisions focus primarily on the factory price.

An Indian-made product can already contain significant logistics costs before it enters a container for its journey to the UK.

Strong exports tighten the westbound market

The second pressure point is India–Europe shipping.

Indian containerised exports to Europe reached an estimated 518,000 TEU during the first half of 2026, with stronger-than-expected demand creating a pronounced capacity squeeze.

Westbound rates increased again during August and are approaching levels last experienced around four years ago. Space has become increasingly difficult to secure, with some leading India–Europe services selling out several weeks ahead and additional spot capacity appearing only as carriers release allocations.

The problem is not simply growing demand. Available capacity has struggled to keep pace.

Blank sailings, congestion and rolled cargo at Nhava Sheva and Mundra are reducing effective space, while some capacity has been redirected towards growing Latin American flows using Indian ports for transhipment.

For cargo owners, guaranteed space can therefore command a premium, while less flexible shipments face greater rollover and delay risks.

Look beyond the supplier price

India's manufacturing scale and expanding trade relationships continue to make it an important sourcing market. But the changing freight environment reinforces the need to assess the complete landed cost of sourcing there.

A product assembled using Chinese or other Asian components may now carry substantially higher inbound logistics costs. Moving the finished goods from India to the UK then adds a second layer of freight inflation.

For lower-margin or freight-intensive products in particular, those combined costs could materially affect sourcing economics.

Timing matters too. With strong westbound bookings and constrained capacity, waiting for cheaper freight could leave importers competing for even tighter space.

Businesses can reduce that exposure by understanding upstream supply flows, consolidating shipments where appropriate and planning westbound capacity earlier.

Manage the whole supply chain, not just the final leg

The growing relationship between Chinese inputs, Indian manufacturing and European demand means these movements cannot always be managed effectively in isolation.

Metro can connect the complete Asia–India–UK supply chain, providing visibility from upstream suppliers through Indian production and onward to the UK. 

With extensive Indian based capabilities, global carrier relationships, consolidation and alternative routing options, we can identify where cost and capacity pressures are building and act before they reach your bottom line. EMAIL Andrew Smith, Metro’s Managing Director, to learn about protecting your landed cost from origin to destination.

White House 1440x1080 1

US tariff uncertainty is becoming a permanent supply chain challenge

US importers face another period of significant trade policy change as the Trump administration expands its use of tariffs across countries, commodities and industries.

The immediate challenge is understanding which measures apply and how they interact. The wider issue is more fundamental: Section 301 is developing into a broad mechanism for imposing additional tariffs, while stricter customs enforcement increases the financial consequences of getting classification, valuation or origin wrong.

For importers, tariff exposure can no longer be treated as a temporary disruption. It increasingly needs to form part of sourcing, landed-cost and customs compliance decisions.

New tariffs broaden importer exposure

The latest changes follow the expiry of temporary Section 122 tariffs introduced in February 2026 after the Supreme Court overturned the administration’s earlier use of emergency powers for its ‘Liberation Day’ tariffs.

On 24 July, the administration introduced new tariffs on 59 countries and the European Union following a Section 301 investigation into goods allegedly produced using forced labour. The measures effectively restored a 10%–12% minimum tariff across economies responsible for around 99% of US imports, although significant product exemptions remain.

The UK was placed in the 10% group rather than the 12.5% tier applied to many other countries. There are product-specific exemptions under the UK-US Economic Prosperity Deal, so the 10% does not apply universally.

UK automotive exports benefit from a 10% tariff within the agreed 100,000-vehicle quota, aerospace goods have preferential treatment, and UK pharmaceutical exports secured 0% tariffs in April 2026. Different Section 232 or other measures can also apply depending on the commodity.

These duties can also stack on top of existing measures, helping push the estimated overall US effective tariff rate to approximately 10.8%.

Some individual measures go considerably further. Selected Brazilian goods face additional tariffs of 25%, while certain Canadian products have been targeted with duties of 50%. From 31 July, some pharmaceutical imports also became subject to tariffs reaching 100%.

More measures could follow. An investigation into excess industrial capacity covers 16 economies, including China, India, Japan and the EU, while further action targeting digital policies and specific industries remains possible.

The near-term outlook therefore points towards continued volatility rather than simplification. Importers should expect tariffs to change by country, product and policy objective, making total landed-cost calculations increasingly important when comparing suppliers and sourcing locations.

Enforcement raises the cost of getting customs wrong

Tariffs are only one part of the financial exposure. US Customs and Border Protection is also moving towards more aggressive enforcement.

Importers face increased scrutiny of the three areas fundamental to duty assessment: tariff classification, customs valuation and country of origin. Errors can result not only in additional duty assessments but potentially penalties where authorities believe tariffs have been avoided.

The scope for mitigating penalties may also be narrowing. Industry analysis indicates that reductions which historically could reach 90% are becoming less readily available, with mitigation potentially limited to around 50% for trusted traders able to demonstrate effective written controls and robust compliance procedures.

This makes customs governance increasingly important. Importers should review classifications, origin determinations and valuation methodologies before goods arrive rather than relying on retrospective corrections.

Procurement contracts also deserve attention. Businesses may need clearer provisions determining which party absorbs new tariffs and what happens if government action materially changes the economics of an existing sourcing agreement.

Tariffs are likely to remain part of the landscape

Legal challenges continue, including action involving 25 US states, but importers should be cautious about building their strategy around the prospect of tariffs disappearing.

Section 301 has expanded well beyond its previous association with China and is increasingly being used across different countries and policy objectives. Further investigations are expected, suggesting additional tariff announcements remain possible.

Even successful legal challenges may not deliver lasting certainty if the administration replaces overturned measures using alternative statutory authority.

For importers, this changes the emphasis from reacting to individual tariff announcements to building greater resilience into customs and sourcing strategies. That means modelling landed costs under different tariff scenarios, reviewing alternative origins and suppliers, maintaining accurate customs data and identifying opportunities to use legitimate duty-management mechanisms.

Metro’s growing US footprint combined with customs brokerage capability at every US gateway gives importers the support they need as tariff and enforcement requirements become more complex. Our teams can review classification, valuation, origin and duty exposure before cargo moves, identify potential customs risks and help you understand how changing tariffs affect your true landed cost.

With US trade policy changing quickly, don’t wait for a new tariff or customs intervention to expose a problem. Talk to Metro now about reviewing your imports, customs compliance and duty exposure. EMAIL Managing Director Andrew Smith.