Cathay tailfins 1440x1080 1

Asia air freight enters autumn with momentum intact

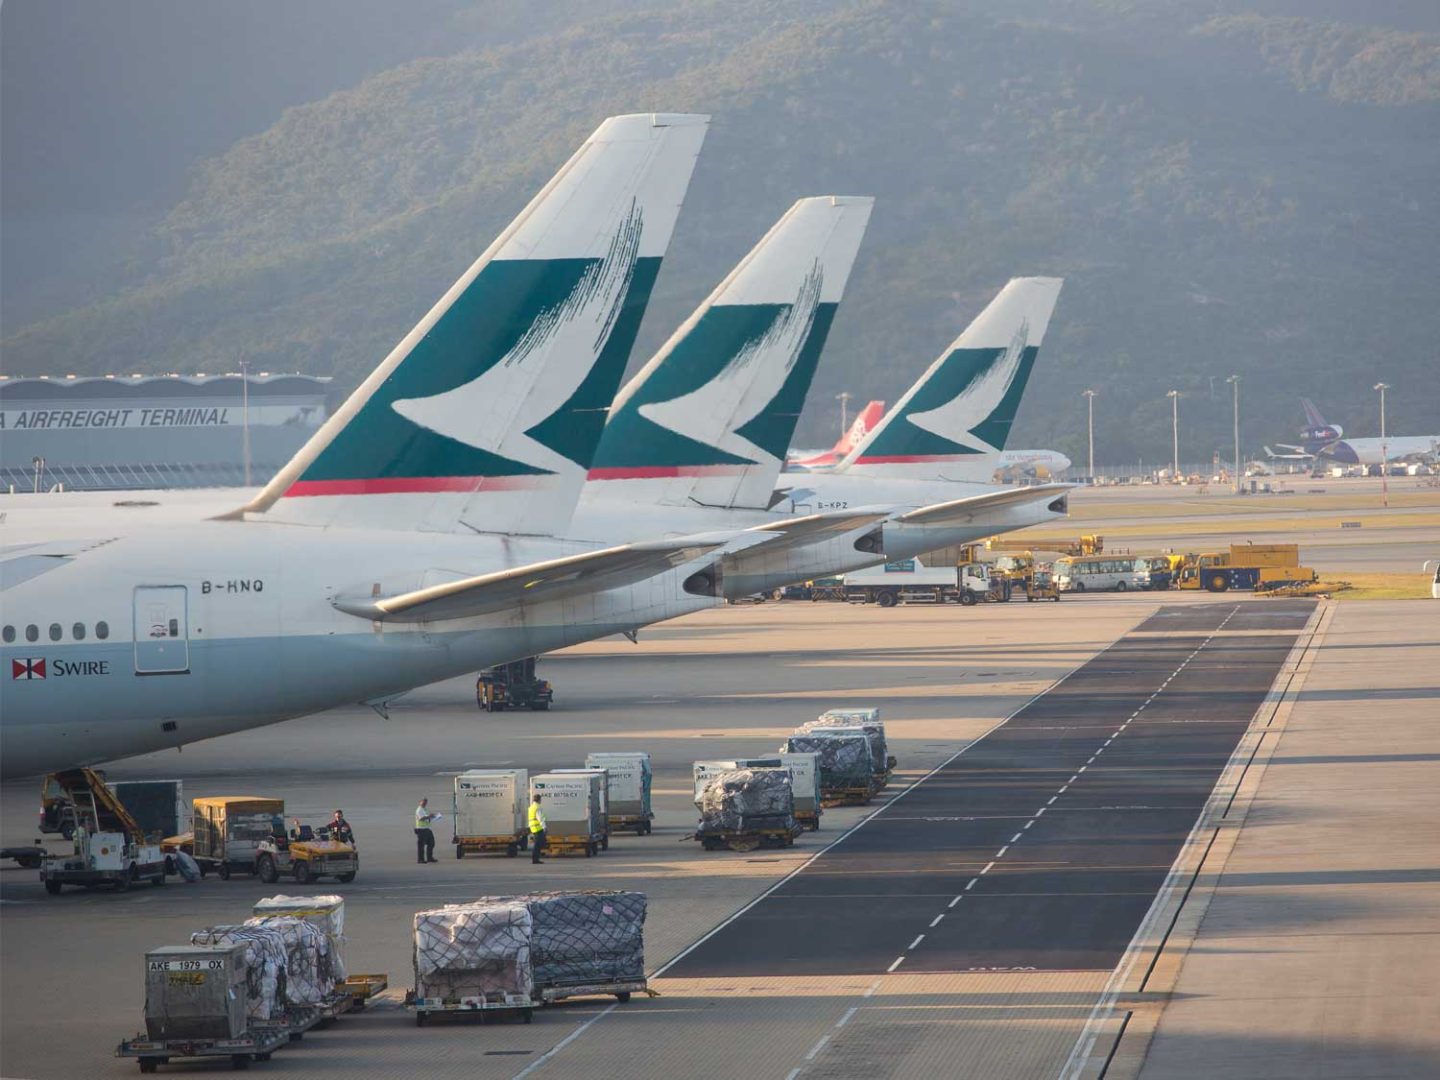
Air cargo’s traditional summer slowdown has failed to significantly loosen the market, with resilient demand, constrained capacity and renewed growth on key ex-Asia lanes keeping pressure on space and pricing as autumn begins.

Global air cargo volumes were 6% higher year on year in August, following 5% growth in July. More recent data shows that momentum continuing into September, with worldwide chargeable weight in week 36 still 7% above the same period last year.

Asia remains central to that strength. High-tech exports, AI and data-centre equipment, manufacturing activity and e-commerce continue to support demand, while available lift has struggled to grow at the same pace.

The result is an ex-Asia market that is increasingly defined by individual origins and trade lanes rather than a single regional trend.

Capacity remains the critical constraint

Global air cargo capacity was flat year on year during August, pushing capacity utilisation three percentage points above August 2025 levels. Dedicated freighters are carrying much of the additional demand, with freighter traffic having increased almost 14% year on year in July.

Adding substantial new lift remains difficult. Delayed new aircraft deliveries and passenger-to-freighter conversion programmes are restricting expansion, while carriers have been quick to redeploy freighters towards stronger markets.

That flexibility became particularly visible following changes to European low-value import rules. Falling e-commerce traffic initially weakened China and Hong Kong–Europe volumes, prompting some freighter capacity to move towards the stronger transpacific market.

However, the European picture is now showing signs of stabilisation. China–Europe volumes returned to modest week-on-week growth during August, while Hong Kong–Europe traffic increased 6% in week 36, its third consecutive weekly rise. Mainland China volumes have also been growing by low single-digit percentages since early August.

This recovery is significant as the market moves beyond the summer period and towards the traditional fourth-quarter peak.

Ex-Asia pricing reflects a tighter market

Although global spot pricing has gradually eased from its earlier highs, it remained 24% above last year during August. The latest weekly figures also point to renewed upward pressure from Asia.

In week 36, Asia Pacific spot rates increased 3% week on week to Europe and 2% to the US. China and Thailand to Europe both rose 6%, while Taiwan increased 7%.

Across Asia Pacific as a whole, pricing to Europe stood 15% above last year, while rates to the US were 40% higher.

High-tech manufacturing hubs remain particularly firm. Recent year-on-year increases included around 25% from South Korea and Taiwan, 22% from Vietnam, 32% from Thailand and 42% from Malaysia.

The transpacific remains especially strong. AI-related equipment and other technology exports continue to support demand from Northeast and Southeast Asia, while China and Hong Kong volumes to the US have remained resilient despite significant changes to low-value import rules.

There are also signs that the initial shock from Europe's new e-commerce rules may be passing. China’s low-value exports to Europe fell sharply after the July changes, but the subsequent improvement in China and Hong Kong tonnage suggests the market is beginning to find a new balance.

That does not necessarily mean a conventional peak season is developing. Instead, shippers face a more fragmented market in which capacity can move quickly between corridors and individual origins can tighten independently.

Further pressure could come from fuel. Rising oil prices are increasing aviation fuel costs, creating the prospect of higher surcharges just as autumn demand begins to build.

For businesses moving time-sensitive cargo from Asia, the combination of resilient demand, limited capacity growth and rapidly changing trade-lane conditions makes early planning increasingly important.

Metro combines local expertise across Asia with global air freight buying power and real-time market intelligence to identify pressure before it reaches your supply chain. 

Whether you need secured capacity, alternative gateways, flexible routings or support through the autumn peak, our air freight specialists can build the right solution around your priorities and keep critical cargo moving.
Metro model truck 1440x1080 1

Road freight resilience starts before the truck arrives

UK haulage is entering a period in which access to the right vehicle, route and transport option could become increasingly important. For shippers, that makes planning and flexibility just as important as the rate agreed for an individual movement.

More than half of UK HGV drivers are aged between 50 and 65, while fewer than 2% are under 24. Replacing an ageing workforce brings recruitment, training, insurance and employment costs at the same time as operators manage wider pressure on vehicle operating expenses.

That does not mean the UK is heading inevitably towards a nationwide shortage of trucks. But it is going to make availability more variable by location, vehicle type and periods of peak demand.

For shippers, the response is to look beyond simply finding a truck when one is needed for UK or international movements and consider the strength, flexibility and resources behind their transport solution.

More ways to keep freight moving

Access to multiple transport options provides an important buffer when individual parts of the market tighten.

Metro combines its own commercial fleet with a wider UK and European road freight network, giving customers access to dedicated domestic transport, groupage, less-than-truckload (LTL) and full-truckload (FTL) solutions.

Dedicated vehicles can operate on fixed routes, with GPS tracking providing visibility throughout the journey. Different equipment, security and service options also allow the transport solution to be matched more closely to the cargo, delivery environment and required transit time.

Metro’s UK road freight teams are strategically located close to major manufacturing and transport hubs, supporting both domestic movements and international connections.

That capability extends across Europe, with established groupage services connecting customers with France and Germany, including the industrially important Ruhr region, with further services into the Netherlands, Poland, Iberia and Turkey. Frequent departures and established partner networks provide further options for both inbound and outbound freight.

This breadth matters when availability changes. Rather than depending on one mode of road transport or a narrow pool of vehicles, shippers can combine dedicated, groupage, LTL and FTL services according to shipment size, urgency and destination.

Plan capacity, not individual movements

The other side of road freight resilience is using available capacity efficiently.

Booking transport at the final stage of a shipment can leave logistics teams with fewer choices if the required vehicle or departure is already constrained. Earlier visibility of inbound and outbound requirements creates more opportunity to plan collections, consolidate freight, secure equipment and select alternative services.

It can also help businesses avoid treating domestic or European haulage as an isolated final step.

A container arriving at a UK port, an urgent movement into Germany or several smaller consignments moving into continental Europe all create different transport requirements. Connecting those movements with the wider supply chain makes it easier to choose the right solution before capacity becomes critical.

That could mean consolidating smaller shipments into groupage, moving time-sensitive cargo on a dedicated vehicle, using LTL where greater flexibility is available or securing FTL capacity earlier for larger movements.

The objective is not simply to source the lowest rate for today’s shipment. It is to create enough options to keep freight moving efficiently as demand, availability and operating costs change.

For UK and European shippers, the resources behind a road freight provider are therefore becoming increasingly important. Its own fleet, access to additional capacity, range of service options, network coverage and ability to adapt routes when circumstances change.

Metro combines its own commercial fleet with an extensive UK and European road freight network, giving customers the flexibility to move from dedicated vehicles to groupage, LTL and FTL solutions as requirements change. 

With strategically located teams, MVT supply chain management platform, GPS-tracked services and strong connections across key European markets, we can build road freight solutions around your cargo, keeping goods visible, capacity accessible and supply chains moving.

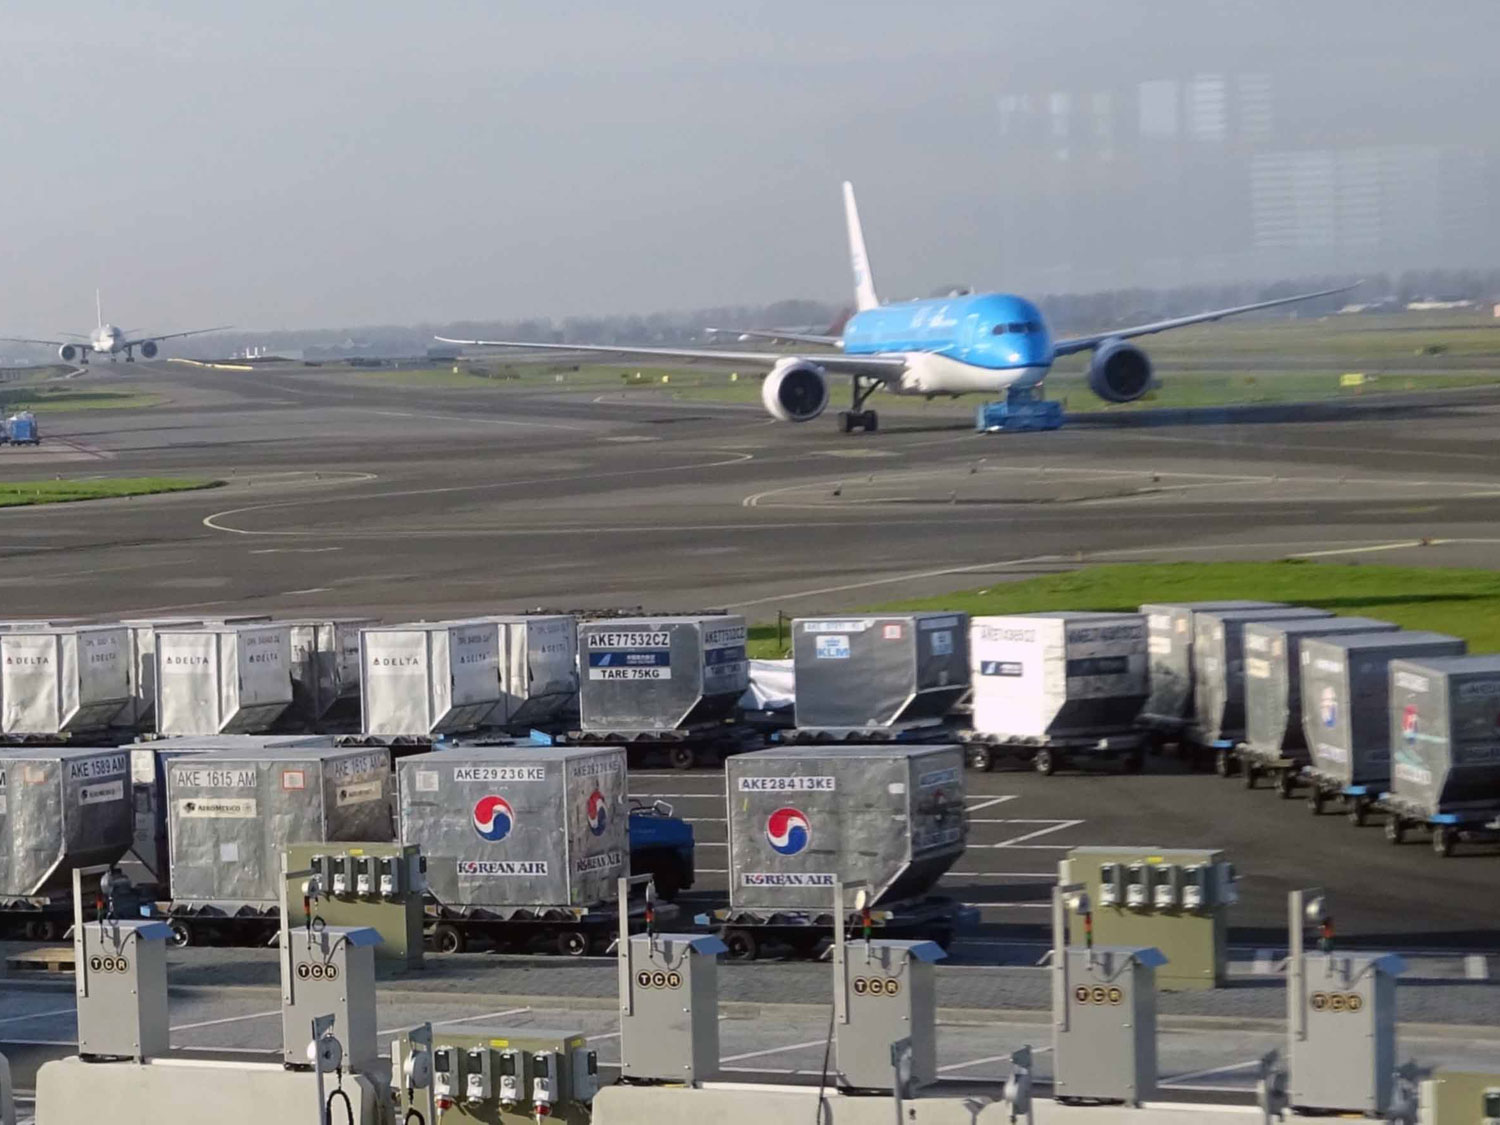
ULD on tarmac

Air freight market tightens ahead of autumn peak

Air freight enters the traditional peak-season build-up with a finely balanced market, as capacity reductions and resilient pricing create the potential for rapid tightening when Asian export demand accelerates.

The usual late-September surge may still be several weeks away, but UK importers have good reason to start planning now.

Asia–Europe demand softened during August, yet rates have shown little corresponding weakness. Airlines and freighter operators are adjusting capacity as cargo flows change, while higher fuel costs and stronger demand on alternative trade lanes are providing additional support.

That leaves limited spare capacity to absorb the traditional autumn increase – particularly if ocean freight disruption pushes urgent shipments towards air.

Softer demand is not delivering cheaper capacity

Asia Pacific–Europe chargeable weight fell 5% week on week and 14% year on year in week 33, continuing the softer trend evident since late June.

Changing e-commerce flows have contributed to the decline. China–Europe volumes were 8% lower year on year in week 32, while Hong Kong–Europe traffic fell 29%.

Despite that weakness, Asia Pacific–Europe spot rates remained flat in week 33 after rising 1% the previous week. China was particularly resilient, recording a 6% increase despite lower volumes.

The explanation lies partly on the supply side. Asia Pacific capacity contracted 2% in week 33 after declining 1% the previous week, limiting the downward pressure on rates.

Freighter deployment may tighten the market further. Stronger transpacific demand provides operators with an incentive to allocate aircraft towards the US, potentially reducing the capacity available for European cargo as peak season approaches.

China shows how quickly conditions can change

Recent disruption around Shanghai illustrates the vulnerability of available capacity.

Typhoon Dolphin caused more than 1,000 flight cancellations and contributed to an 8% weekly reduction in chargeable weight from Shanghai, while Shanghai–Europe volumes fell 7%.

The immediate disruption has eased, but severe weather and congestion across Chinese ocean gateways remain relevant to the air freight outlook. When container schedules become unreliable, urgent and time-sensitive cargo can quickly switch from ocean to air.

Even a relatively small modal shift can have a disproportionate effect on air freight capacity and pricing.

Golden Week could mark the turning point

The next significant test comes around China's Golden Week.

Factories traditionally accelerate production before the holiday, followed by another increase as operations resume and backlogs clear. October also brings the start of the main pre-Christmas replenishment cycle.

Demand then typically intensifies through November as retailers and e-commerce businesses prepare for Black Friday, Cyber Monday and Christmas.

This year, however, the market enters that period with capacity already responding closely to demand. That could make the transition from today's relatively balanced conditions to a tighter market particularly rapid.

Fuel costs, severe weather, changing freighter deployment and disruption to ocean services provide additional variables.

The opportunity is before the peak

For shippers, softer August volumes could offer a useful planning window rather than a reason to wait for lower rates.

Businesses with visibility of their autumn requirements can secure allocations earlier, consider alternative origins and gateways, and decide which shipments genuinely require premium air services.

Booking ahead of cargo-ready dates will become increasingly important as demand builds, particularly from China and other major Asian export markets. Flexible routing can also provide valuable alternatives when individual gateways or direct services tighten.

The key consideration is not simply today's air freight rate, but the availability of the right capacity when cargo needs to move.

Metro combines extensive Asian origin coverage with global airline relationships, flexible routing and multiple service levels to keep UK supply chains moving when peak-season capacity tightens. 

Share your autumn forecasts with Metro now and we can secure the capacity, routing and service strategy your cargo needs before the peak takes hold.

EMAIL Andrew Smith, Metro’s Managing Director.

Shanghai Hongqiao Airport 1440x1080 1

Regional airfreight demand and capacity diverge

The global airfreight market is becoming increasingly difficult to predict through headline averages. While worldwide volumes remain above last year’s levels, conditions are diverging sharply between individual origins and trade lanes as de-minimis regulation, technology demand, weather disruption and capacity shifts reshape cargo flows.

For UK, European and US shippers, this means the availability and cost of airfreight increasingly depend on exactly where cargo originates and which carrier networks it uses. Asia may appear relatively balanced overall, while individual gateways can experience much tighter capacity or rapidly changing rates.

The latest WorldACD data reinforces that picture. Global tonnage fell 4% in the latest reporting week, but remained 1% higher year on year, while individual Asian origins recorded movements ranging from double-digit growth to double-digit declines. 

Asia–Europe adjusts to e-commerce changes and shifting capacity

Asia–Europe is undergoing a significant adjustment following changes to the EU’s treatment of low-value e-commerce shipments.

The introduction of a €3 charge on packages valued below €150 at the beginning of July has affected one of air cargo’s most important sources of recent growth. By week 32, China–Europe e-commerce volumes were 8% lower year on year, while Hong Kong–Europe volumes were down almost 30%.

Overall Asia Pacific–Europe tonnage fell, yet rates moved in the opposite direction on some important lanes, with Asia Pacific–Europe spot pricing increasing 1%, led by a 6% increase from China and 3% from Hong Kong.

This apparent contradiction reflects changes in available capacity. Freighter capacity previously deployed for e-commerce traffic appears to be moving between markets, allowing pricing to strengthen even as overall volumes soften.

Weather is adding another variable. Typhoon Dolphin caused more than 1,000 flight cancellations in Shanghai, contributing to an 8% week-on-week decline in total air cargo from the gateway. Disruption to Chinese seaports could subsequently generate some modal shift from ocean to air as businesses try to recover delayed shipments.

“Airfreight is becoming much more localised,” says Phil Morris, Metro’s Head of Airfreight. “A regional average can suggest that capacity is plentiful, but that may not reflect what is happening at an individual origin. Shippers increasingly need to look at the cargo mix, available capacity and conditions at specific gateways rather than relying on the headline market.”

Transpacific technology demand creates localised pressure

The transpacific market presents a different picture. Asia Pacific–US tonnage declined 4% week on week in early August and spot rates fell 3%, suggesting a relatively balanced market at regional level. But significant variations sit beneath those figures.

Japan–US volumes increased 12% in a single week, while Taiwan and Indonesia’s volumes were down around 10%. High-value technology cargo is also supporting demand from Japan, South Korea, Taiwan, Thailand and Vietnam.

AI servers, semiconductors, electronics and associated data-centre infrastructure are particularly important because these products are high-value, time-sensitive and often linked to fixed deployment schedules. Airfreight can therefore remain the preferred mode even when ocean capacity is available.

That demand can have consequences for businesses outside the technology sector. Cargo moving through the same airports, using the same freighter capacity or competing for uplift during concentrated production periods can encounter tighter availability and firmer pricing.

“For shippers, it is important to understand what else is moving from their origin,” Phil adds. “A surge in one high-value vertical can tighten an airport very quickly. That makes early conversations about capacity and alternative routings particularly valuable, especially as we approach Q4.”

Further typhoon activity across Asia could amplify these localised pressures if flight cancellations or airport disruption coincide with peaks in technology exports.

Transatlantic capacity remains comparatively accessible

The transatlantic market currently offers a more stable environment, with capacity generally available as the summer passenger schedule provides substantial belly-hold space.

WorldACD data shows North America–Europe volumes fell 5% over the latest two-week comparison, while European exports to North America increased 3%. This creates different conditions depending on direction rather than a single transatlantic trend.

The current availability provides an opportunity for shippers with flexible requirements, but the position could change as passenger schedules transition from summer to winter and belly capacity reduces.

The broader lesson is that airfreight has moved away from a market where one global trend reliably describes conditions everywhere. Regulation is reshaping e-commerce demand, technology is concentrating demand around particular Asian origins, weather can remove capacity with little warning and seasonal passenger schedules continue to influence individual corridors.

Shippers can respond by separating genuinely time-critical freight from cargo with greater delivery flexibility, securing capacity earlier on constrained origins and maintaining alternative gateway and routing options.

Metro’s global airfreight network gives shippers the visibility and flexibility to respond to these increasingly localised conditions. Our airfreight teams monitor capacity, rates, weather disruption and demand at origin level, identifying where space is tightening and where alternative gateways, carriers or routings can provide an advantage. 

Whether you are moving cargo from Asia to the UK, Europe or US, or across the Atlantic, talk to Metro early so we can secure the capacity and routing that best protects your cost, transit time and delivery commitments.

To learn more, EMAIL Managing Director Andrew Smith today