Aircraft and moon

Airfreight market strengthens as peak season nears

Global air cargo demand and rates are strengthening ahead of the traditional peak season, with rising volumes, firm pricing and higher fuel costs creating a more robust market as October begins.

The latest TAC Index and WorldACD data point to increasing momentum as the industry moves towards its busiest months, although conditions continue to vary significantly by trade lane.

The global Baltic Air Freight Index gained a further 0.6% in the seven days to 28 September, extending a series of modest weekly increases and leaving rates nearly 22% above the same point last year.

Meanwhile, WorldACD recorded a fourth consecutive weekly increase in global chargeable weight in week 38, with tonnages rising 2% week on week and 8% year on year.

Demand builds across major origin markets

The underlying demand picture is increasingly positive. Asia Pacific remained one of the strongest contributors, with origin tonnages 11% higher year on year. North American volumes increased 14% week on week following the Labor Day dip and were 8% above last year's level, while European origin volumes were 6% higher year on year.

Rates are also substantially above 2025 levels. WorldACD's average worldwide full-market rate was 24% higher year on year in week 38, while average spot rates were 33% higher.

Asia Pacific spot rates were 30% above last year, with Europe up 29% and North America 34%.

TAC Index data for the following week suggests that firmness continued into the end of September, with its global index extending its year-on-year increase to 21.7%.

The backdrop is being reinforced by significantly higher fuel costs. TAC reported that jet fuel prices were 106% above their level a year earlier by 25 September, adding another source of upward pressure as the market approaches peak.

Asia markets gather momentum

Asia is likely to be central to the developing peak-season picture. TAC recorded a 3% weekly increase in its Hong Kong outbound index during the week to 28 September, taking it 20.6% above last year. Rates from India also increased strongly, while China-Europe pricing continued to firm as the market adjusted following changes affecting low-value parcel traffic.

WorldACD similarly recorded further increases in Asia Pacific-Europe spot rates during week 38, including gains from mainland China, Hong Kong, Japan and South Korea.

The transpacific remains particularly strong. Asia Pacific-US demand was 13% higher year on year, including significant growth from South Korea, Japan and China. Average spot rates on the trade were broadly stable week on week but approximately 40% above their level a year earlier.

The picture towards Europe is more mixed. China and Hong Kong volumes have yet to recover fully from the disruption that followed the removal of the EU de minimis exemption in July, but pricing has begun moving higher on several key origins.

Golden Week adds to peak-season pressure

Attention is now turning to China's National Day Golden Week (1–7 October), which follows closely behind the Mid-Autumn Festival (25–27 September) and compresses production, export handovers and freight planning into a short period.

Metro’s local partners are already reporting stronger general cargo demand from North China as shippers move goods before the holiday, while transpacific demand from Southern China is also increasing.

Available capacity and additional charter operations have so far helped contain more dramatic rate movements. However, the combination of recovering volumes, firm year-on-year pricing, higher fuel costs and the traditional Q4 uplift creates the potential for conditions to tighten further as October progresses.

Worldwide international capacity was only 4% higher year on year in week 38, compared with an 8% increase in tonnage. Capacity also remains constrained in some markets affected by geopolitical disruption, particularly the Gulf.

Early planning for the Q4 peak

The latest figures do not point to a uniform capacity squeeze, but they do suggest that the airfreight market is entering peak season from a considerably stronger position than a year ago.

With demand building, rates already elevated year on year and conditions varying sharply between origins and trade lanes, access to the right capacity at the right time will become increasingly important through the final quarter.

Metro's global airfreight network, carrier relationships and flexible routing options help customers secure capacity and respond quickly as market conditions change. 

If you have time-critical, high-value or peak-season shipments planned for Q4, talk to our airfreight team about protecting capacity and keeping cargo moving.
HKG port

Asian port congestion could disrupt supply chains well into 2027

Severe congestion across Asian container ports is tying up millions of TEU of capacity, driving schedule reliability to a four-year low and raising the prospect of disruption continuing well into 2027.

Repeated typhoons, strong Asian export demand and congestion spreading between ports have created disruption comparable in scale with the peak of the pandemic.

While conditions should improve as weather disruption eases, analysis of previous congestion cycles suggests clearing the accumulated vessel and container backlogs could take considerably longer.

Sea-Intelligence estimates it could take up to ten months for congestion to return to the levels recorded in June 2025, potentially leaving supply chains dealing with the consequences through the first half of next year.

Reliability falls as capacity gets trapped

The immediate impact is already visible in global shipping schedules. Schedule reliability fell another 5.9 percentage points in Sea-Intelligence's September report to 49.9%, its lowest level since September 2022 and the second consecutive significant monthly decline.

Late vessels are also getting later. Average delays increased by 0.6 days to 6.81 days, the highest since March 2022 and almost two days longer than a year earlier.

Estimates of the amount of capacity affected vary according to methodology and timing, but indicate the scale of the problem. Around 3.9m TEU is currently caught up in global port congestion, returning congestion volumes to levels last experienced in 2022.

Sea-Intelligence calculates the disruption is absorbing around 8.5% of the global containership fleet, effectively removing millions of TEU of usable vessel capacity from the market.

That helps explain why the industry's substantial influx of new vessels has yet to translate fully into available capacity. Ships waiting outside ports or arriving significantly behind schedule cannot provide the capacity their nominal deployment suggests.

Disruption spreads across Asian networks

Weather has been an important catalyst. Repeated typhoons have reduced effective port capacity at major Chinese gateways at the same time as strong export demand has increased pressure on terminals.

But congestion rarely remains confined to the port where the original disruption occurs.

Late vessels arrive together at subsequent calls, creating bunching and additional terminal pressure. Carriers may respond by omitting badly affected ports, but that can simply transfer containers and vessel calls to alternative gateways and transhipment hubs.

Some of that pressure is already shifting towards Southeast Asia and the Indian subcontinent.

The distortion can also make scheduled capacity figures misleading. Asia–North Europe deployment around Golden Week reached around 1.5m TEU over four weeks, approximately 27% higher year on year and 60% above pre-pandemic averages.

Rather than representing a straightforward increase in available space, part of that apparent capacity reflects vessels bunching as disrupted schedules overlap.

Rates reflect shrinking effective capacity

The consequences are particularly visible within Asia. Drewry's Intra-Asia Container Index has reached record territory as Golden Week demand meets restricted effective capacity. Shanghai–Laem Chabang increased 22% in its latest assessment, while Shanghai–Jakarta rose 12%.

The impact extends further afield. Asia–US rates remain close to pandemic-era records, while charter markets are also signalling exceptionally tight vessel availability.

This creates an important distinction for shippers: deployed capacity and usable capacity are not the same thing.

Even as carriers receive new vessels, congestion can absorb that additional capacity before customers see the benefit through improved availability, reliability or pricing.

The landside challenge could last longer

Port congestion also has consequences beyond vessel schedules. For individual shippers, reliability ultimately depends on when cargo actually becomes available and reaches its destination. Vessel bunching can create sudden surges in container volumes through terminals, rail connections, depots and road networks.

Those supporting networks cannot expand as quickly as vessel capacity.

Terminal, rail and road infrastructure requires long-term investment, while operators also need to maintain high asset utilisation. That leaves less spare capacity available to absorb sudden spikes following weather disruption or vessel bunching.

The result can be a second wave of delay after a vessel reaches port, particularly where terminals and inland networks are already operating close to capacity.

Chinese New Year becomes the next pressure point

The length of the potential recovery is therefore significant.

Based on recovery patterns following the pandemic and the initial Red Sea disruption, Sea-Intelligence estimates congestion could take six to eight months simply to return to conditions seen at the end of 2025, and 10 months to return to the much lower levels recorded in June 2025.

That timeline extends beyond Golden Week and potentially into the next major Asian shipping peak.

Chinese New Year falls on 6 February 2027, meaning the traditional pre-holiday cargo rush could arrive before networks have fully cleared today's disruption.

For shippers planning Q4 movements and early 2027 supply chains, advance bookings, realistic transit assumptions and flexibility around routing and gateways could therefore remain important well beyond the current congestion peak.

Keeping cargo moving when networks tighten

Metro combines established global carrier relationships with extensive origin, destination and inland capabilities, giving our teams the flexibility to respond when congestion disrupts established shipping patterns.

Through consolidation services, alternative carrier and routing options, gateway selection and coordinated inland transport, we can assess the complete movement rather than relying on a single service or routing.

With Asian congestion potentially affecting capacity and schedules well into 2027, talk to Metro about upcoming movements and the options available to protect space, maintain visibility and build greater flexibility into your supply chain.

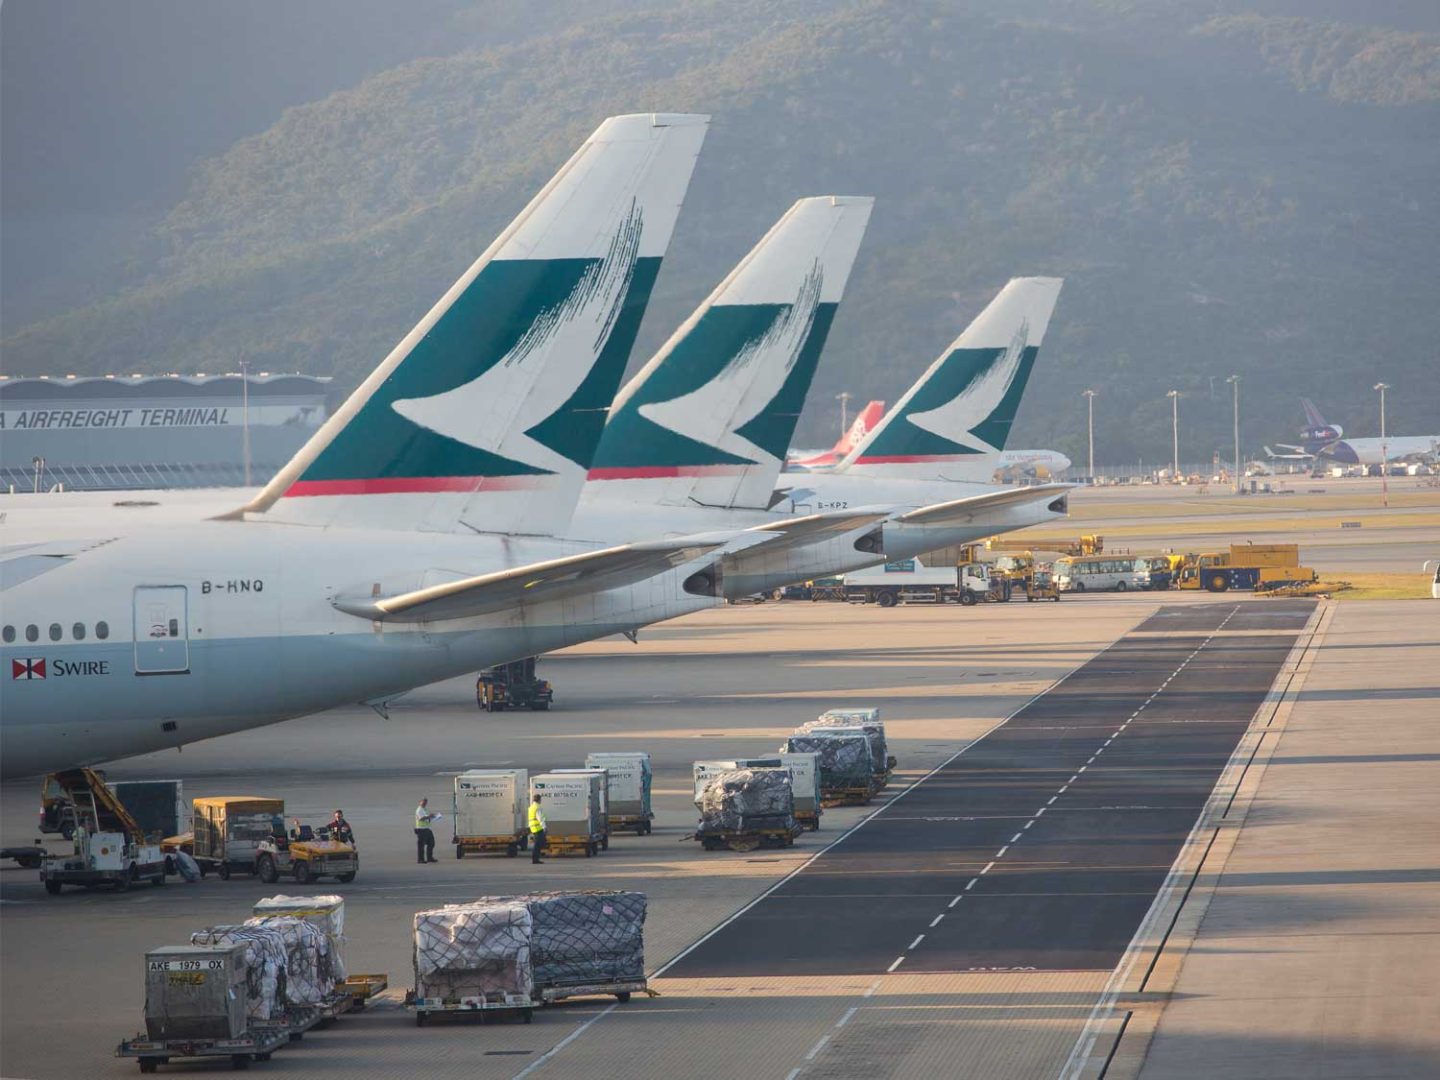
Cathay tailfins 1440x1080 1

Asia air freight enters autumn with momentum intact

Air cargo’s traditional summer slowdown has failed to significantly loosen the market, with resilient demand, constrained capacity and renewed growth on key ex-Asia lanes keeping pressure on space and pricing as autumn begins.

Global air cargo volumes were 6% higher year on year in August, following 5% growth in July. More recent data shows that momentum continuing into September, with worldwide chargeable weight in week 36 still 7% above the same period last year.

Asia remains central to that strength. High-tech exports, AI and data-centre equipment, manufacturing activity and e-commerce continue to support demand, while available lift has struggled to grow at the same pace.

The result is an ex-Asia market that is increasingly defined by individual origins and trade lanes rather than a single regional trend.

Capacity remains the critical constraint

Global air cargo capacity was flat year on year during August, pushing capacity utilisation three percentage points above August 2025 levels. Dedicated freighters are carrying much of the additional demand, with freighter traffic having increased almost 14% year on year in July.

Adding substantial new lift remains difficult. Delayed new aircraft deliveries and passenger-to-freighter conversion programmes are restricting expansion, while carriers have been quick to redeploy freighters towards stronger markets.

That flexibility became particularly visible following changes to European low-value import rules. Falling e-commerce traffic initially weakened China and Hong Kong–Europe volumes, prompting some freighter capacity to move towards the stronger transpacific market.

However, the European picture is now showing signs of stabilisation. China–Europe volumes returned to modest week-on-week growth during August, while Hong Kong–Europe traffic increased 6% in week 36, its third consecutive weekly rise. Mainland China volumes have also been growing by low single-digit percentages since early August.

This recovery is significant as the market moves beyond the summer period and towards the traditional fourth-quarter peak.

Ex-Asia pricing reflects a tighter market

Although global spot pricing has gradually eased from its earlier highs, it remained 24% above last year during August. The latest weekly figures also point to renewed upward pressure from Asia.

In week 36, Asia Pacific spot rates increased 3% week on week to Europe and 2% to the US. China and Thailand to Europe both rose 6%, while Taiwan increased 7%.

Across Asia Pacific as a whole, pricing to Europe stood 15% above last year, while rates to the US were 40% higher.

High-tech manufacturing hubs remain particularly firm. Recent year-on-year increases included around 25% from South Korea and Taiwan, 22% from Vietnam, 32% from Thailand and 42% from Malaysia.

The transpacific remains especially strong. AI-related equipment and other technology exports continue to support demand from Northeast and Southeast Asia, while China and Hong Kong volumes to the US have remained resilient despite significant changes to low-value import rules.

There are also signs that the initial shock from Europe's new e-commerce rules may be passing. China’s low-value exports to Europe fell sharply after the July changes, but the subsequent improvement in China and Hong Kong tonnage suggests the market is beginning to find a new balance.

That does not necessarily mean a conventional peak season is developing. Instead, shippers face a more fragmented market in which capacity can move quickly between corridors and individual origins can tighten independently.

Further pressure could come from fuel. Rising oil prices are increasing aviation fuel costs, creating the prospect of higher surcharges just as autumn demand begins to build.

For businesses moving time-sensitive cargo from Asia, the combination of resilient demand, limited capacity growth and rapidly changing trade-lane conditions makes early planning increasingly important.

Metro combines local expertise across Asia with global air freight buying power and real-time market intelligence to identify pressure before it reaches your supply chain. 

Whether you need secured capacity, alternative gateways, flexible routings or support through the autumn peak, our air freight specialists can build the right solution around your priorities and keep critical cargo moving.

Metro model truck 1440x1080 1

Road freight resilience starts before the truck arrives

UK haulage is entering a period in which access to the right vehicle, route and transport option could become increasingly important. For shippers, that makes planning and flexibility just as important as the rate agreed for an individual movement.

More than half of UK HGV drivers are aged between 50 and 65, while fewer than 2% are under 24. Replacing an ageing workforce brings recruitment, training, insurance and employment costs at the same time as operators manage wider pressure on vehicle operating expenses.

That does not mean the UK is heading inevitably towards a nationwide shortage of trucks. But it is going to make availability more variable by location, vehicle type and periods of peak demand.

For shippers, the response is to look beyond simply finding a truck when one is needed for UK or international movements and consider the strength, flexibility and resources behind their transport solution.

More ways to keep freight moving

Access to multiple transport options provides an important buffer when individual parts of the market tighten.

Metro combines its own commercial fleet with a wider UK and European road freight network, giving customers access to dedicated domestic transport, groupage, less-than-truckload (LTL) and full-truckload (FTL) solutions.

Dedicated vehicles can operate on fixed routes, with GPS tracking providing visibility throughout the journey. Different equipment, security and service options also allow the transport solution to be matched more closely to the cargo, delivery environment and required transit time.

Metro’s UK road freight teams are strategically located close to major manufacturing and transport hubs, supporting both domestic movements and international connections.

That capability extends across Europe, with established groupage services connecting customers with France and Germany, including the industrially important Ruhr region, with further services into the Netherlands, Poland, Iberia and Turkey. Frequent departures and established partner networks provide further options for both inbound and outbound freight.

This breadth matters when availability changes. Rather than depending on one mode of road transport or a narrow pool of vehicles, shippers can combine dedicated, groupage, LTL and FTL services according to shipment size, urgency and destination.

Plan capacity, not individual movements

The other side of road freight resilience is using available capacity efficiently.

Booking transport at the final stage of a shipment can leave logistics teams with fewer choices if the required vehicle or departure is already constrained. Earlier visibility of inbound and outbound requirements creates more opportunity to plan collections, consolidate freight, secure equipment and select alternative services.

It can also help businesses avoid treating domestic or European haulage as an isolated final step.

A container arriving at a UK port, an urgent movement into Germany or several smaller consignments moving into continental Europe all create different transport requirements. Connecting those movements with the wider supply chain makes it easier to choose the right solution before capacity becomes critical.

That could mean consolidating smaller shipments into groupage, moving time-sensitive cargo on a dedicated vehicle, using LTL where greater flexibility is available or securing FTL capacity earlier for larger movements.

The objective is not simply to source the lowest rate for today’s shipment. It is to create enough options to keep freight moving efficiently as demand, availability and operating costs change.

For UK and European shippers, the resources behind a road freight provider are therefore becoming increasingly important. Its own fleet, access to additional capacity, range of service options, network coverage and ability to adapt routes when circumstances change.

Metro combines its own commercial fleet with an extensive UK and European road freight network, giving customers the flexibility to move from dedicated vehicles to groupage, LTL and FTL solutions as requirements change. 

With strategically located teams, MVT supply chain management platform, GPS-tracked services and strong connections across key European markets, we can build road freight solutions around your cargo, keeping goods visible, capacity accessible and supply chains moving.